just now


Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
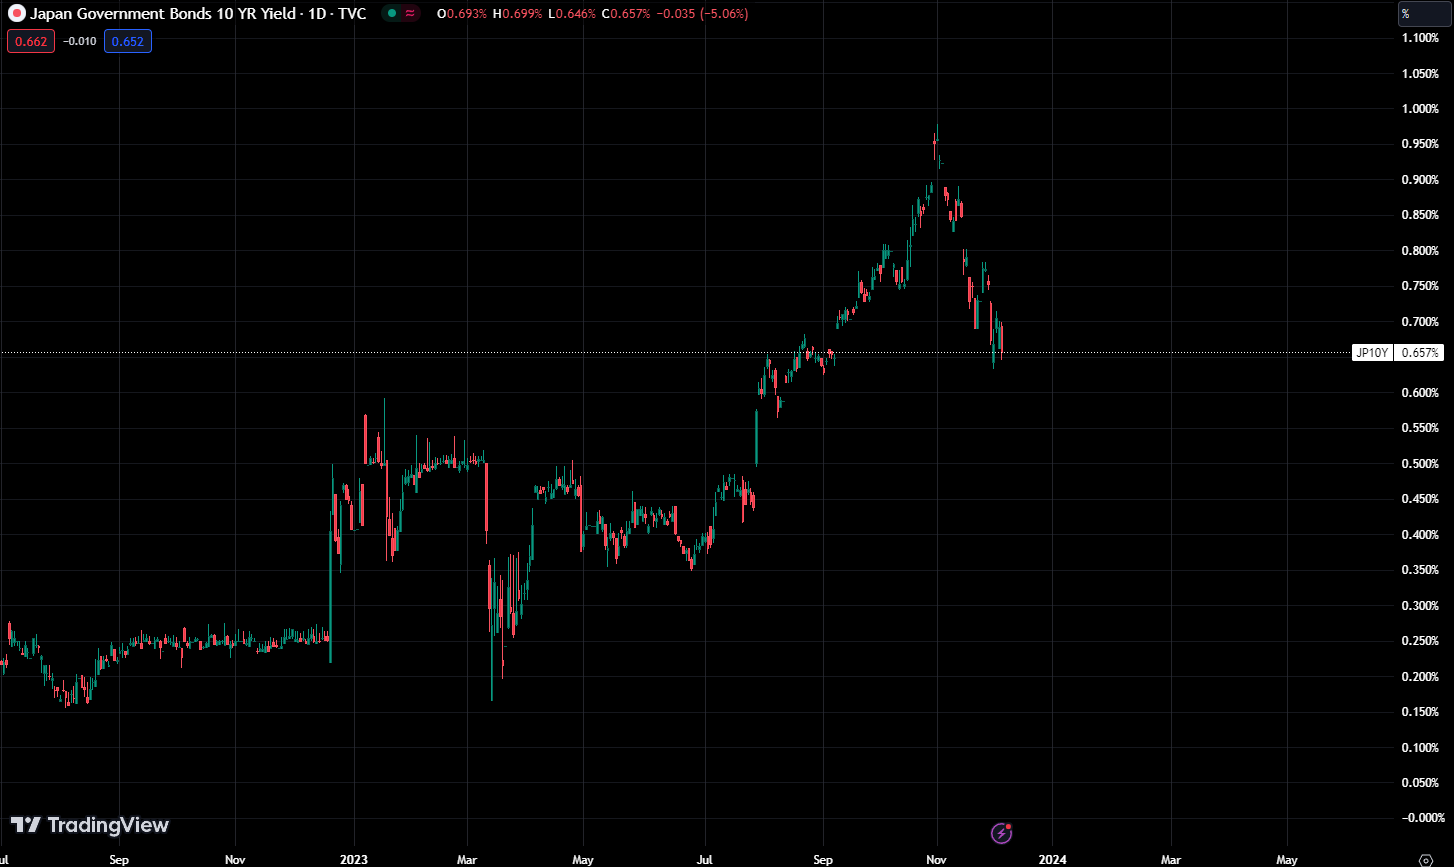
If the net domestic fund demand remains at approximately the current level of -0.4%, and the Bank of Japan (BoJ) acquires JPY7 trillion worth of Japanese Government Bonds (JGBs), the macro fair value for the 10-year JGB would hover around 0.7%. The current 10-year JGB yield in the market, remaining close to the macro fair value, suggests that it adequately incorporates the additional downward pressure on yields imposed by the BoJ's commitment to the existing easing framework. In essence, the current pricing reflects an absence of expectations for any imminent changes in the Yield Curve Control (YCC) or negative interest rate policy.
JP10Y
Source: TradingView
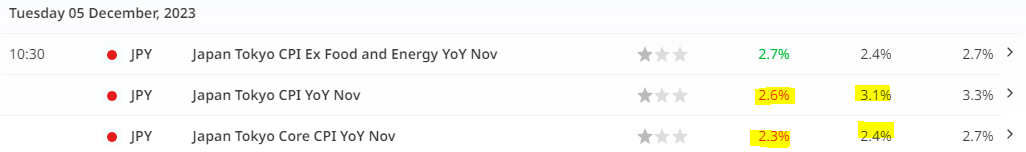
In November, the core-core Consumer Price Index (CPI) for Tokyo, excluding fresh food and energy, showed no growth, further decelerating compared to October. The weakening household fundamentals likely heightened households' sensitivity to price fluctuations. Over a 3-month period, the Tokyo core-core CPI decelerated from over 4% in March-April to 2.2% as of November. If the core-core CPI increases by only 0.1% month-on-month in December, it would fall below the BoJ's 2% target on a 3-month basis.
Japan CPI
Source: Finlogix Calendar
In the event of a slowdown in the US economy prompting the Federal Reserve to reduce its policy rate, the Japanese Yen (JPY) is likely to experience strong appreciation pressures. The BoJ has previously failed to fully lift Japan out of deflation by tightening policy during the global economic peak. The government may not declare victory in overcoming deflation until the corporate savings rate becomes negative, and structural deflationary forces vanish. Exiting the current monetary easing policies may not be feasible for the BoJ until these conditions are met.
Initiating the policy tightening process before inflation expectations rise sufficiently to sustain 2% inflation and in the face of a slowing global economy increases the risk of Japan slipping back into deflation. This scenario could result in a significant decline in long-term yields, mirroring past mistakes of tightening monetary policy at the global economic peak and failing to completely eradicate deflation in Japan.
Failing to lift Japan out of deflation for a third time would likely invite criticism from the government, especially given the central bank's commitment to overcoming deflation.
The modelling of 10-year Japanese Government Bond (JGB) yields involves various factors such as net domestic fund demand (as a percentage of GDP), the Bank of Japan's (BoJ) policy interest rate (call rate), the BoJ's long-term government bond purchases (as a percentage of GDP), the US 10-year government bond yield, and a dummy variable representing the negative interest rate and Yield Curve Control (YCC) policy framework (0 before Q425, 1 after Q116). Using these variables, the macro fair value of the 10-year JGB yield can be calculated on a quarterly basis since 1990. The formula is as follows:
10YJGByield (%) = 0.26 + 0.69 Domestic O / N interbank call rate + 0.2710YUSTyield (%) − 0.04Net domestic fund demand (%GDP) − 0.02BoJJ GB purchases (annualized rate, % GDP) − 0.40NIRP・YCC dummy + 0.51 Up dummy −0.45 Down dummy; R2= 0.99
Given the decline in US treasury yields, the BoJ is reducing its monthly purchases of JGBs from JPY9 trillion to JPY7 trillion to ease the strain on the JGB market caused by the existing monetary easing program. The BoJ, committed to expanding the monetary base until the 2% inflation target is achieved, is unlikely to decrease JGB purchases below JPY6 trillion, accounting for the redemption of JGBs held by the central bank.
Assuming net domestic fund demand remains at the current level of -0.4% and the BoJ purchases JPY7 trillion of JGBs, the macro fair value of the 10-year JGB yield would be approximately 0.7%. The current market 10-year JGB yield staying close to the macro fair value indicates that it fully incorporates the additional downward pressure on yields exerted by the BoJ through its commitment to the current easing framework. In simpler terms, the existing pricing reflects no expectations of changes in the Yield Curve Control or negative interest rate policy soon. This conclusion holds, even considering market expectations related to the government's economic stimulus package of around JPY17 trillion (3% of GDP) and a potential return of BoJ purchases to around JPY9 trillion per annum.
In November, the Tokyo core-core Consumer Price Index (CPI), excluding fresh food and energy, recorded zero growth, further decelerating compared to October. Deteriorating household fundamentals likely increased sensitivity to price changes, leading households to respond more strongly to price increases by reducing consumption. Over a 3-month period, the Tokyo core-core CPI decelerated from over 4% in March-April to 2.2% in November. Retailers might consider lowering prices to stimulate demand during the holiday season, potentially causing core-core CPI to fall below the BoJ's 2% target on a 3-month basis if it grows by only 0.1% month-on-month in December.
A potential slowdown in the US economy and a Fed policy rate cut could result in strong appreciation pressures on the Japanese Yen (JPY). A strengthened JPY increases the risk of the economy falling into deflation. The BoJ's previous attempts to lift Japan out of deflation by tightening policy during the global economic peak have been unsuccessful. The government is unlikely to declare victory over deflation until the corporate savings rate turns negative and structural deflationary forces dissipate. Exiting the current monetary easing policies is expected to be challenging for the BoJ until these conditions are met.
Initiating the policy tightening process before inflation expectations are sufficiently elevated and in the face of a global economic slowdown increases the risk of Japan falling back into deflation. This scenario could lead to a significant decline in long-term yields, repeating mistakes made by the central bank in previous decades, including tightening monetary policy at the global economic peak and failing to eliminate deflation in Japan. Failing to pull Japan out of deflation for a third time is likely to invite criticism from the government, especially given the central bank's commitment to overcoming deflation. Recent statements from BoJ policy board members indicate a growing awareness of such concerns within the central bank.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.

Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Brokers can offer LMAX perpetual futures alongside FX and CFDs through a single trading account. LMAX says brokers with existing credentials can go live in under five days.
24X National Exchange has filed a proposed rule change with the SEC to launch 24X Options, a general options market trading from 9:30 a.m. to 4:00 p.m. ET. The filing also covers binary KPI options on quarterly revenue, earnings per share and other metrics for 23 of the most actively traded U.S. companies.
cTrader Mobile 5.11 introduces Signals, a new app where traders can browse signals from leading providers and act on them directly in the platform.
ATFX Group has partnered with South Africa-based payment and digital asset infrastructure provider FiveWest to support institutional fund movements for ATFX Connect and add a cryptocurrency funding option for eligible retail clients. Both firms hold FSCA Over-the-Counter Derivative Provider licences.
UK inflation rose to 3.6% in October, keeping a December Bank of England rate rise likely, while the euro hit a fresh one-year low against the dollar ahead of tonight’s Fed minutes. Daily FX analysis from Equals.
GBPUSD has shifted decisively lower. After reaching 1.3228, the pair reversed and initially consolidated around the moving averages before breaking sharply below the 1.3180 area. It is now trading near 1.3169.
Nvidia shares jumped around 4% after hours after beating earnings and revenue expectations and raising its outlook for 75% year on year revenue growth through January 2028. The positive Nvidia results also lifted AI-related stocks, with CoreWeave up 8% and Nebius 10%.
Deutsche Börse Group has appointed Maximilian Weissenrieder as Head of Cash Market from 1 January 2027, succeeding Eric Leupold, who becomes CEO of Eurex. Weissenrieder has led Group M&A and Venture Investments since October 2024 and will retain those duties until a successor is named by the Group.
DEXA, the AI-powered risk management and analytics platform developed by TFB (Tools for Brokers), has connected with Match-Trader, bringing real-time trader analysis and toxic flow detection to brokers on the platform. DEXA classifies trader behaviour from as early as the third trade, with no change to execution systems.
Poland's financial markets regulator, the Polish Financial Supervision Authority (Komisja Nadzoru Finansowego, KNF), is preparing a new product intervention on contracts for difference (CFDs)