just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

Canada CPI
Source: Finlogix Calander
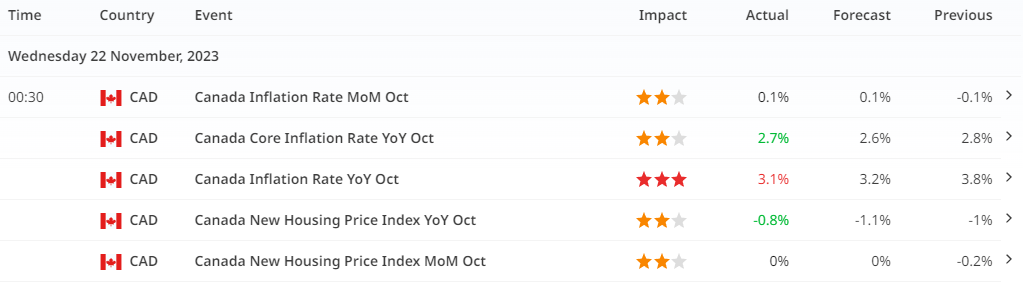
In the month of October, Canada witnessed a further moderation in annual inflation, with the pace standing at 3.1%, aligning with consensus expectations. This marked a significant deceleration from the previous month's 3.8%, primarily attributed to a decline in gasoline prices. However, notable contributors to annual inflation remained consistent, with mortgage interest costs (MIC), rent, and food prices continuing to exert significant influence.
Delving into the Bank of Canada's preferred inflation metrics, both the CPI-trim and median indicators exhibited deceleration, registering at 3.5% and 3.6% year-on-year, respectively. This trend suggests a concentration of price increases, particularly in shelter costs. Examining CPI excluding food, energy, and MIC, the figure remained at 2.2% year-on-year and decelerated to 1.8% in three-month annualized change terms. Looking ahead, the prevailing weak economic conditions are expected to exert further downward pressure on these measures, potentially paving the way for the Bank of Canada to consider rate cuts as early as the second quarter of the following year.
The acceleration in service price inflation, rising to 4.6% year-on-year from 3.9%, can be attributed to various one-off factors unrelated to underlying demand. Property taxes, typically priced annually in October, increased by 4.9% year-on-year, while electricity prices in Alberta witnessed a significant surge of 45% year-on-year. Travel tour prices also experienced an 11% year-on-year increase, although this pace may not be sustained due to consumer constraints arising from higher interest rates and a rise in the unemployment rate. Disinflationary signals were evident in the airline industry, as airfares declined by 19% year-on-year.
On the goods front, prices decelerated to 1.6% year-on-year from 3.6%, and even when excluding food and energy, a notable deceleration occurred, dropping to 1.7% year-on-year from 2.4%. This deceleration reflects ongoing improvements in supply, as the inventory-to-sales ratio surpassed its pre-pandemic level in the second quarter, likely to rise further as constraints on production ease in the coming months. The deceleration is also indicative of fading demand, with retail sales exhibiting lacklustre performance as consumers allocate a greater portion of their income to higher interest payments.
The rental market experienced a surge in costs, rising by 8.2% year-on-year, driven by population growth and elevated interest rates attracting new entrants. This surge in rental costs further solidifies shelter as the primary source of inflation, as CPI excluding shelter maintains a 1.9% year-on-year pace.
Implications & actions
Regarding the economic forecast, it is anticipated that the headline Consumer Price Index (CPI) index may not exhibit significant progress by the end of the year. This expectation is based on the influence of base effects, which could lead to a notable jump in December following a temporary reprieve in November. The anticipated drop in energy prices from a year ago is expected to be a significant factor in this annual calculation.
However, despite potential fluctuations in the headline CPI index, the Bank of Canada is expected to place greater emphasis on its preferred core measures of trim and median. These core measures are anticipated to continue decelerating, primarily due to weakened domestic demand. This ongoing deceleration in core measures could provide policymakers with the necessary conditions to contemplate and potentially implement interest rate cuts, with a potential timeline as early as the second quarter of the following year.
The consideration of core measures underscores the central bank's focus on underlying inflationary trends, providing a more nuanced and stable view compared to the headline CPI, which can be influenced by temporary factors. The expectation of interest rate cuts in the coming quarters reflects a proactive stance by policymakers in response to prevailing economic conditions, with an emphasis on addressing weak domestic demand as a key factor in their decision-making process.
Concerning the markets' response to the economic data, it is noteworthy that there was minimal reaction observed. This lack of significant movement can be attributed to the fact that the reported figures were in line with the consensus expectation. Despite the data aligning with market forecasts, there remains a prevailing sentiment that markets are assigning insufficient probability to potential Bank of Canada (BoC) interest rate cuts in the upcoming year, at least according to the perspective being presented.
The market's seemingly subdued reaction could be indicative of a certain level of complacency or an underestimation of the likelihood of future policy adjustments by the BoC. This perspective suggests that, even with data falling within anticipated ranges, there may be factors or trends not fully priced in by market participants, potentially impacting their expectations for central bank actions.
This interpretation implies that market sentiment might be overlooking certain economic indicators or risks that could influence the BoC's decisions in the future. It underscores the importance of considering a broader range of factors beyond just the immediate data release when gauging market reactions and expectations.
The notion of potentially insufficient odds being placed on BoC cuts in the upcoming year implies a potential divergence between market sentiment and the expectations of those advocating for a more dovish stance. It will be interesting to observe how this dynamic evolves in the coming months and whether there will be an adjustment in market expectations in response to changing economic conditions or shifts in central bank guidance.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.

Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Why did gold keep falling after reaching $3,880? See how a failed 4-hour retest confirmed weakness in XAUUSD and why $3,400 is the next weekly support to watch.
Reality television personality Aaron Chalmers and finfluencer Jason Agbodza have been fined after pleading guilty to illegally promoting an unauthorised foreign exchange trading scheme on social media.
UK retail sales rose a stronger-than-expected 0.7% in October, giving sterling some support, while a deepening tech sell-off pushed the dollar lower overnight against all major currencies. Thanim Islam, Head of FX Analysis at Equals, says the dollar remains in charge as the week ends, with the Fed expected to raise rates more than both the Bank of England and the ECB.
Nvidia beats expectations, reporting $115.8bn in revenue and raising its long-term growth outlook, but the stock still struggled to sustain its gains. AI remains fundamentally strong, but investor expectations are becoming more demanding, particularly around capex and profitability. Wall Street suffered a major sell-off, with the S&P 500 entering a six-session losing streak as rate concerns intensified.
iSAM Securities reviews the ris of weekend gold trading
Webull Corporation reported record third quarter 2026 revenue of $218.7 million, up 39% year-on-year, with customer assets reaching $32.4 billion and options contracts volume up 79%. Net income attributable to the company was $31.2 million, while margin debit balances passed $1 billion for the first time.
Anthropic, the company behind the Claude family of AI models, begins trading on the Nasdaq today under the ticker ANT. It priced its shares at $83 last night, above its marketed range of $70 to $78, and raised about $81.3 billion. That makes it the largest initial public offering on record, ahead of the roughly $75 billion SpaceX raised in June. This note covers what investors need to know: the terms, the business, how the company is governed, and what to watch.
Nvidia's first results without Jensen Huang answered the question that has hung over the AI trade since October. Revenue of $115.8 billion beat consensus by about $7 billion, fourth-quarter guidance of $130 billion came in roughly $5 billion above expectations, and the company raised its outlook for next fiscal year to around 75% growth. All of this assumes no data-centre sales to China.
Marex has entered the football financing market through a partnership with specialist sports investment and advisory firm Pinto Capital, targeting clubs in the Premier League and EFL Championship.
Around 110,000 UK retail investors have secured $300 million worth of Anthropic shares in its record-breaking $81 billion IPO. The heavily oversubscribed offer, coordinated by RetailBook, saw smaller investors prioritised, with 63% of applicants receiving their full allocation.