just now


Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

Headline CPI rose just 0.1% month-on-month in line with consensus, but the year-on-year figure softened to 2.4% against expectations for 2.5%. More notably, core CPI slowed to 2.8% YoY, missing the forecast of 2.9%. On a sequential basis, the 0.1% core MoM print helped confirm that inflation pressures while still present are not accelerating in the way some feared given the backdrop of newly reinstated tariffs.
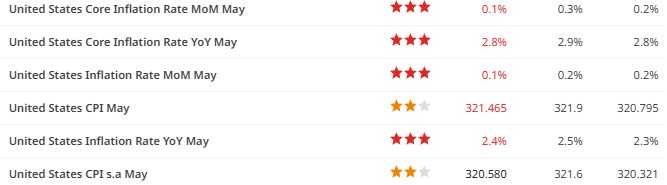
This data weakens the immediate argument for inflation-driven rate hikes and reinforces the idea that the Federal Reserve can remain patient. In response, the dollar (DXY) sold off modestly, particularly against lower-beta currencies, while long-end Treasury yields slipped. Markets will now be watching for how Fed speakers interpret this in the days ahead, particularly given the previously elevated concern over tariff passthrough and inflation anchoring.
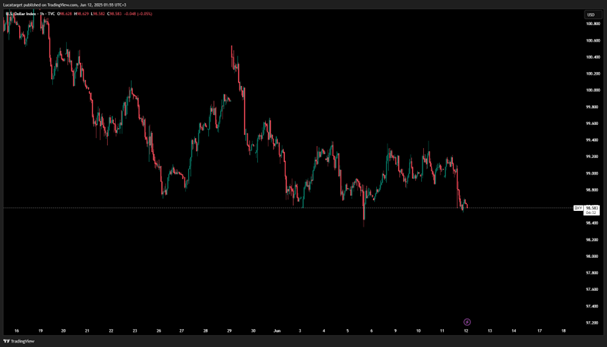
The lower CPI print is especially significant given it captures a full month of trade-related pricing pressures following the reintroduction of 10% reciprocal tariffs by the US administration. The absence of a significant price spike suggests businesses may still be absorbing cost increases or that the consumer’s willingness to tolerate higher prices is waning. Either way, the short-term inflation impulse from tariffs appears more muted than feared.
However, risks remain firmly on the table. The upcoming July 9 deadline for the expiration of the current tariff suspension could result in the US increasing reciprocal duties to 20% or even 50% on some EU goods. A court hearing scheduled for July 31 is unlikely to intervene in time, and as such, the inflation story is far from over. The market may have received temporary relief, but the structural backdrop is still one of fragility.
Meanwhile, demand for long-dated Treasuries continues to deteriorate. While Tuesday’s 3-year auction passed with only mild concern, the $39 billion 10-year and $22 billion 30-year auctions this week remain critical. Investor appetite is clearly thinning, driven by both inflation uncertainty and worsening debt sustainability sentiment. The sharp breakdown in correlation between 30-year yields and the US dollar which has fallen from +0.65 last year to near zero reflects this evolving risk perception.
On the currency front, two underperformers stand out.
The New Zealand dollar (NZD/USD) has weakened following confirmation that former RBNZ Governor Adrian Orr quietly resigned in March due to internal conflict regarding central bank funding. Although the change was not made public until now, it raises questions about the institution's internal stability and independence, particularly as the country navigates a high inflation environment with slowing growth.
The Japanese yen continues to drift lower, weighed down by speculation that the Bank of Japan will reduce the pace of its JGB purchases. While there were initial rumours of Ministry of Finance bond buybacks, these have since been denied. The JGB market remains broadly stable, and with inflation pressures building, there is a growing likelihood that the BoJ will adopt a more hawkish tone at next week’s meeting. While the yen may weaken in the near term due to dollar strength, we do not see significant scope for a sustained sell-off. A signal of another rate hike from the BoJ could quickly re-anchor the currency.
In Europe, the potential for a 50% reciprocal tariff on EU exports to the US remains a real concern. If enacted, it could accelerate the timing of ECB rate cuts and add downside pressure on the euro. As things stand, the ECB appears increasingly boxed in forced to weigh imported inflation risks against weakening domestic demand.
We are approaching a key inflection point. The combination of tariff-related inflation pressure, weakening bond demand, and deteriorating fiscal sentiment in the US has the potential to reprice the FX complex in a significant way. Today’s CPI print is not just another data point it is a temperature check on whether inflation expectations are becoming unanchored. If inflation surprises to the upside, we could see renewed USD strength, especially if rate cut expectations get pushed back.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplies by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS Feedjust now
Sign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Why did gold keep falling after reaching $3,880? See how a failed 4-hour retest confirmed weakness in XAUUSD and why $3,400 is the next weekly support to watch.
Reality television personality Aaron Chalmers and finfluencer Jason Agbodza have been fined after pleading guilty to illegally promoting an unauthorised foreign exchange trading scheme on social media.
UK retail sales rose a stronger-than-expected 0.7% in October, giving sterling some support, while a deepening tech sell-off pushed the dollar lower overnight against all major currencies. Thanim Islam, Head of FX Analysis at Equals, says the dollar remains in charge as the week ends, with the Fed expected to raise rates more than both the Bank of England and the ECB.
Nvidia beats expectations, reporting $115.8bn in revenue and raising its long-term growth outlook, but the stock still struggled to sustain its gains. AI remains fundamentally strong, but investor expectations are becoming more demanding, particularly around capex and profitability. Wall Street suffered a major sell-off, with the S&P 500 entering a six-session losing streak as rate concerns intensified.
iSAM Securities reviews the ris of weekend gold trading
Webull Corporation reported record third quarter 2026 revenue of $218.7 million, up 39% year-on-year, with customer assets reaching $32.4 billion and options contracts volume up 79%. Net income attributable to the company was $31.2 million, while margin debit balances passed $1 billion for the first time.
Anthropic, the company behind the Claude family of AI models, begins trading on the Nasdaq today under the ticker ANT. It priced its shares at $83 last night, above its marketed range of $70 to $78, and raised about $81.3 billion. That makes it the largest initial public offering on record, ahead of the roughly $75 billion SpaceX raised in June. This note covers what investors need to know: the terms, the business, how the company is governed, and what to watch.
Nvidia's first results without Jensen Huang answered the question that has hung over the AI trade since October. Revenue of $115.8 billion beat consensus by about $7 billion, fourth-quarter guidance of $130 billion came in roughly $5 billion above expectations, and the company raised its outlook for next fiscal year to around 75% growth. All of this assumes no data-centre sales to China.
Marex has entered the football financing market through a partnership with specialist sports investment and advisory firm Pinto Capital, targeting clubs in the Premier League and EFL Championship.
Around 110,000 UK retail investors have secured $300 million worth of Anthropic shares in its record-breaking $81 billion IPO. The heavily oversubscribed offer, coordinated by RetailBook, saw smaller investors prioritised, with 63% of applicants receiving their full allocation.