just now


Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

Wall Street Stocks Slump, BOJ, Global PMIs Up Next
Summary:
The Dollar Index (DXY), which gauges the value of the Greenback against a basket of 6 major currencies, eased to 105.40 from 105.55. US bond yields were mixed. The 10-year rate climbed to 4.49% while the 2-year yield fell 6 basis points to 5.14%.
The US Federal Reserve maintained the Fed Funds rate between 5.25% and 5.5% but the FOMC signaled that the central bank would raise rates again before end-2023.
Across the Atlantic, the Bank of England kept its policy rate unchanged, at 5.25%. The BOE’s Monetary Policy Committee (MPC) voted 5-4 in favor of holding rates steady. The British Pound (GBP/USD) eased to 1.2290 from 1.2320 yesterday.
The Greenback rallied modestly against the Swiss Franc (USD/CHF) to 0.9000 from 0.8977 after the Swiss National Bank kept its policy rate unchanged, at 1.75%. An increase of 25 basis points was widely expected.
Against the yield sensitive Japanese Yen, the US Dollar tumbled to 147.47 from 148.43 yesterday. The Bank of Japan meets today on interest rates and is expected to maintain its dovish stance despite some traders looking for a policy shift.
US economic data released yesterday saw Existing Home Sales fall to 4.04 million from 4.07 million, and forecasts at 4.10 million. The Philly Fed Manufacturing Index plummeted to -13.5 from 12.0.
Wall Street stocks slumped. The DOW finished at 34,040 against yesterday’s 34,440 while the S&P 500 lost 1.7% to 4,327 (4,403). Other global share markets fell. Australia’s ASX 200 plummeted 2.59% to 6,972 against 7,129 yesterday.
The Euro (EUR/USD) rebounded from its lows at 1.0617 to finish at 1.0658 in New York, up modestly from 1.0643 yesterday. The Australian Dollar (AUD/USD) dipped 0.36% to 0.6415 (0.6427).
Against the Asian and Emerging Market Currencies the Greenback was mixed. The USD/CNH pair (Dollar-Offshore Chinese Yuan) dipped to 7.3130 (7.3175). Against the Singapore Dollar the Greenback (USD/SGD) was little changed, at 1.3665 from 1.3670.
Other economic data released yesterday saw the UK Public Sector Net Borrowing climb to GBP 1.08 billion, higher than forecasts of GBP 9.8 billion, and GBP 3.5 billion previously.
US Weekly Claims for Unemployment Benefits fell to 201K from 220K previously, and lower than estimates at 224K. Canada’s National House Price Index (m/m) rose 0.1% up from -0.1% previously.
On the Lookout:
Economic data releases pick up today with the release of Global Manufacturing and Services PMIs. New Zealand kicks off today’s data releases with its NZ August Trade Balance ro(f/c -NZD 0.9 billion from -NZD 1.107 billion – ACY Finlogix).
Australia follows with its Preliminary S&P Flash Manufacturing PMI for September (f/c 49.5 from 49.6 – ACY Finlogix), Australia September Flash Services PMI 46.5 from 47.8 – ACY Finlogix).
Japan follows with its National Core CPI (y/y f/c 3.0% from 3.1% - The UK starts off Europe with its UK GFK September Consumer Confidence Index (f/c -27 from -25 – ACY Finlogix).
Japan follows with its August Headline Inflation Rate (m/m f/c 0.6% from 0.4%; y/y f/c 3.3% from 3.3% - ACY Finlogix), Japanese August Core Inflation Rate (y/y f/c 3% from 3.1% - ACY Finlogix).
Japan also releases its Jibun Bank September Flash Manufacturing PMI (f/c 49.9 from 49.7 – ACY Finlogix), Jibun Bank September Services PMI (f/c 54 from 54.3 – ACY Finlogix).
The UK follows with its UK August Headline Retail Sales (m/m f/c 0.5% from -1.2%; y/y f/c -1.2% from -3.2% - ACY Finlogix); UK August Core Retail Sales (m/m f/c 0.6% from -1.4% - ACY Finlogix).
France follows with its Flash September Manufacturing PMI (f/c 46 from 46 – ACY Finlogix), France Services PMI (f/c 46 from 46 – ACY Finlogix).
Germany follows with its Flash September Manufacturing PMI (f/c 39.5 from 39.1 – ACY Finlogix) and German September Services PMI (f/c 47.2 from 47.3 – ACY Finlogix).
The Eurozone releases its September Manufacturing PMI (f/c 44 from 43.5 – ACY Finlogix), Eurozone September Services PMI (f/c 47.7 from 47.9 – ACY Finlogix).
The UK releases its UK September Manufacturing PMI (f/c 43 from 43 – ACY Finlogix), UK September Flash Services PMI (f/c 49.2 from 49.5 – ACY Finlogix).
The UK releases its September CBI Industrial Trends Orders (f/c -18 from -15 – ACY Finogix). Canada starts off North America with its Canadian July Retail Sales (m/m f/c 0.4% from 0.1%; y/y f/c 0.5% from -0.6% - ACY Finlogix).
The US rounds up today’s economic data releases with its US S&P Flash September Manufacturing PMI (f/c 48 from 47.9) and US S&P Flash Services PMI (f/c 50.6 from 50.5 – ACY Finlogix).
Trading Perspective:
Expect more FX volatility today as we finish the week. Markets will focus on the release of global PMIs. The Dollar Index (DXY) dipped to 105.40 from 105.55 yesterday.
The Fed kept the Funds rate unchanged, between 5.25% and 5.5%, but signaled higher rates before the end of the year. This should keep a bid under the Greenback.
However, it is Friday and speculative long US Dollar positioning could be ripe for a pullback ahead of the weekend. Expect volatility to remain elevated today.
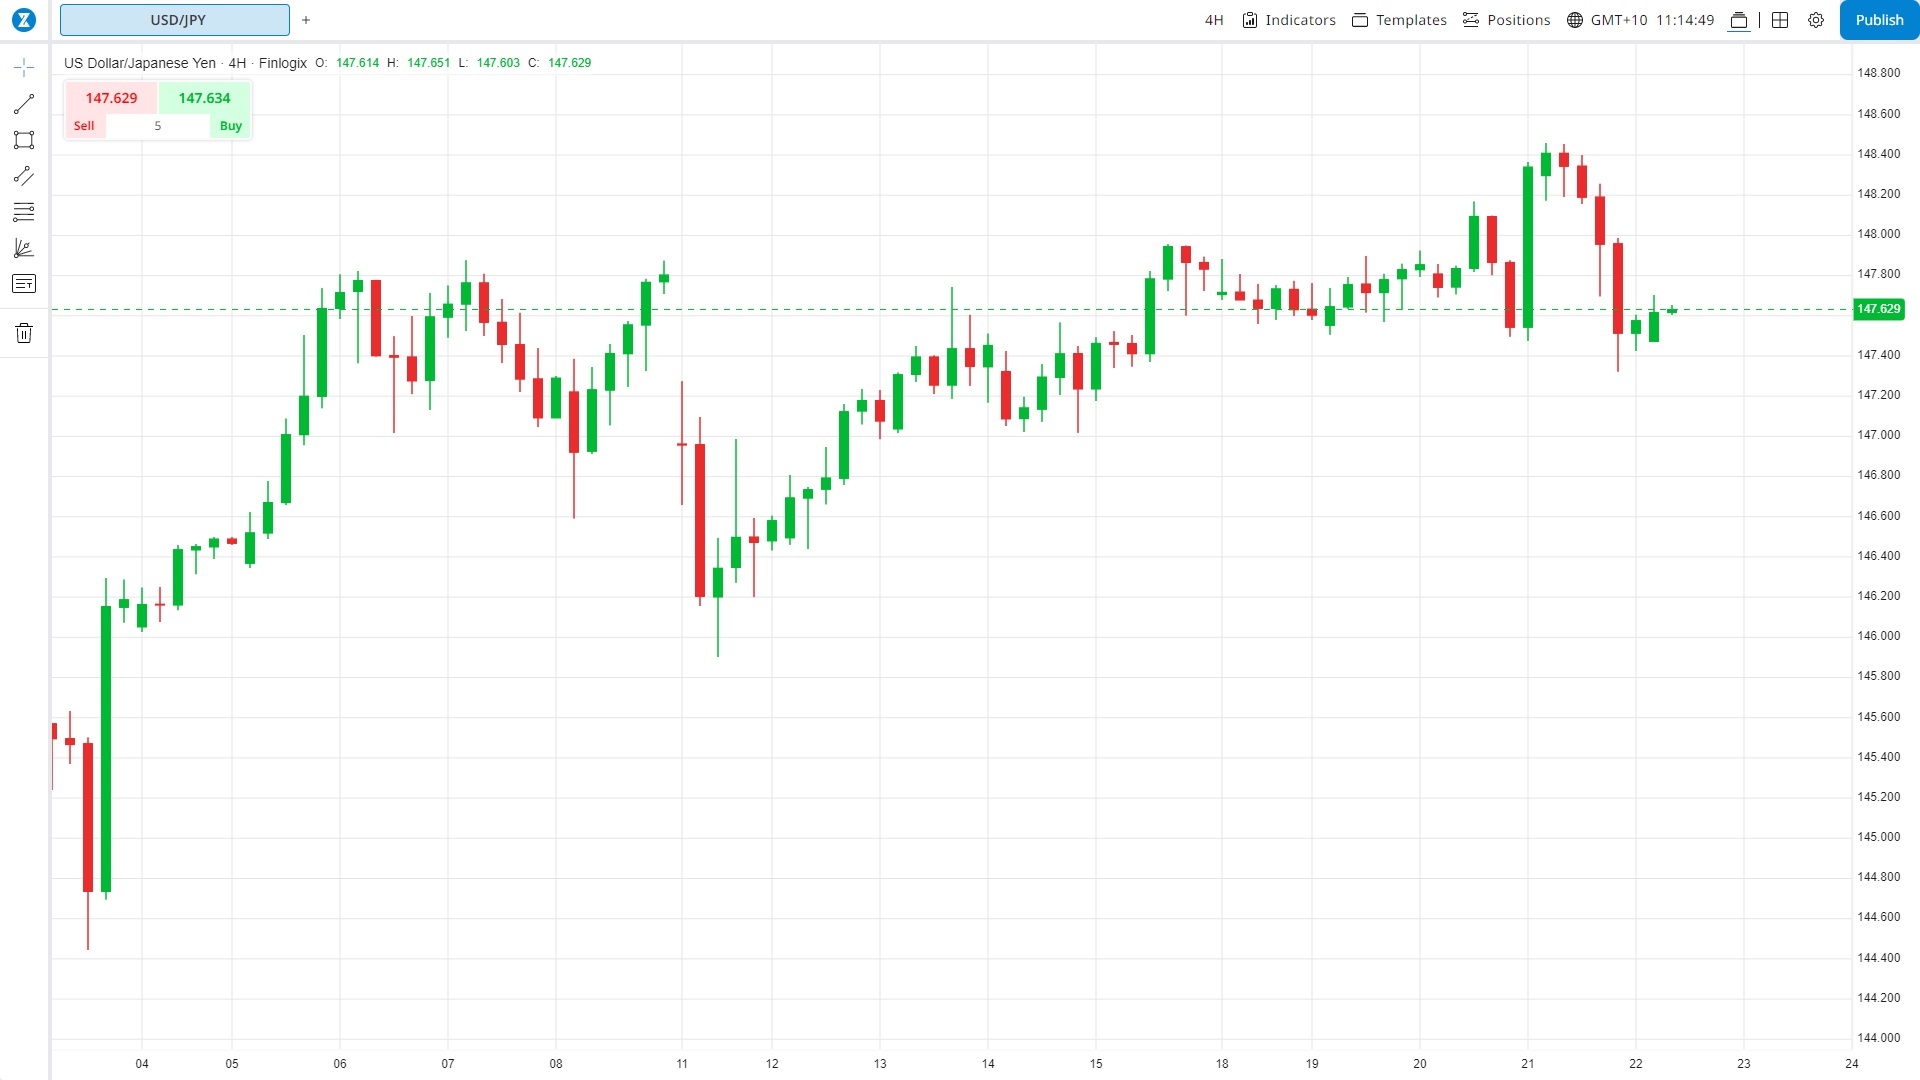
(Source: Finlogix.com)
Happy Friday and trading all. Have a top weekend ahead.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
The Nasdaq 100 has shifted into a short-term bullish recovery after finding strong support around 26,611. Following the sharp sell-off, price has formed a sequence of higher lows and has moved back above the 20-hour moving average at around 27,270, while the 5-hour and 10-hour averages are also turning higher.
U.S. equity futures rose in the after hours, led by Nasdaq-100 futures up 1% and S&P 500 futures up 0.6%, as investors focused on Anthropic’s Nasdaq debut. The AI company priced its IPO at $83 per share, above expectations, and expanded the offering to raise around $81.3 billion, making it the largest IPO on record.
Brokers can offer LMAX perpetual futures alongside FX and CFDs through a single trading account. LMAX says brokers with existing credentials can go live in under five days.
24X National Exchange has filed a proposed rule change with the SEC to launch 24X Options, a general options market trading from 9:30 a.m. to 4:00 p.m. ET. The filing also covers binary KPI options on quarterly revenue, earnings per share and other metrics for 23 of the most actively traded U.S. companies.
cTrader Mobile 5.11 introduces Signals, a new app where traders can browse signals from leading providers and act on them directly in the platform.
ATFX Group has partnered with South Africa-based payment and digital asset infrastructure provider FiveWest to support institutional fund movements for ATFX Connect and add a cryptocurrency funding option for eligible retail clients. Both firms hold FSCA Over-the-Counter Derivative Provider licences.
UK inflation rose to 3.6% in October, keeping a December Bank of England rate rise likely, while the euro hit a fresh one-year low against the dollar ahead of tonight’s Fed minutes. Daily FX analysis from Equals.
GBPUSD has shifted decisively lower. After reaching 1.3228, the pair reversed and initially consolidated around the moving averages before breaking sharply below the 1.3180 area. It is now trading near 1.3169.
Nvidia shares jumped around 4% after hours after beating earnings and revenue expectations and raising its outlook for 75% year on year revenue growth through January 2028. The positive Nvidia results also lifted AI-related stocks, with CoreWeave up 8% and Nebius 10%.
Deutsche Börse Group has appointed Maximilian Weissenrieder as Head of Cash Market from 1 January 2027, succeeding Eric Leupold, who becomes CEO of Eurex. Weissenrieder has led Group M&A and Venture Investments since October 2024 and will retain those duties until a successor is named by the Group.