just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
US 2-Year Yield Climbs, Fed’s Williams Talks Down Rate Cuts
Summary: The Euro (EUR/USD) plummeted 100 pips lower to 1.0895 (1.0995) after data showed that business activity in Europe continued to deteriorate. A poll released by S&P Global, a US financial information and analytics company revealed that activity in Germany and France shrank.
Germany’s Flash Services PMI fell to 48.1 from 48.7 previously, missing forecasts at 49.0. France’s Flash December Manufacturing PMI slid to 42 from 42.9 previously, missing estimates at 43.3.
On the other side of the Atlantic, New York Fed President John Williams said that “its premature to talk about rate cuts at the March meeting”, lifting 2-year US treasury rates to 4.44% from 4.39%.
Chicago Fed President Austan Goolsbee said it was too early to declare victory in the central bank’s inflation fight and that decisions would be made on incoming economic data.
The Dollar Index (DXY), a popular gauge of the Greenback’s value against a basket of 6 major currencies rebounded 0.63% to 102.60 from Friday’s 101.95. The British Pound (GBP/USD) slumped 0.8% to 1.2675 (1.2757).
Against the Japanese Yen, the US Dollar (USD/JPY) rallied to 142.20 from 141.85 Friday. While the 2-year US bond rate was up, the US 10-year treasury yield dipped to 3.91% from 3.93%, limiting the Greenback’s topside.
The Australian Dollar (AUD/USD) was little changed, settling at 0.6700 from 0.6697 Friday. The Aussie Battler held on to its gains after hitting a low of 0.6540 during the week.
The Greenback advanced against the Asian and Emerging Market currencies. USD/CNH (Dollar-Offshore Chinese Yuan) edged higher to 7.1350 from 7.1220. Against the Singapore Dollar (USD/SGD), the Greenback rallied to 1.3320 (1.3290 Friday).
Wall Street stocks finished higher. The DOW gained 0.35% to 37,340 (37,200) while the S&P 500 finished at 4,723, up from 4,715 previously. Japan’s Nikkei climbed to 32,780 (32,720).
Other economic data released Friday saw Eurozone Flash Services PMI tumble to 48.1 from 48.7 previously and lower than expectations at 49.0. US S&P December Global Services PMI rose to 51.3 from 50.8 previously, and higher than economists’ forecasts at 50.6.
On the Lookout: Today starts the last full week of trading in the currency markets. The economic calendar is light and kicked off earlier with New Zealand’s Westpac Bank Consumer Confidence Index which climbed to 88.9, beating forecasts at 85.1 and higher than 80.2 previously. New Zealand’s Business NZ Services Index climbed to 51.2 from 49.2 previously. The Kiwi (NZD/USD) was little changed following the release, at 0.6197 (0.6202). China follows next with its November Foreign Direct Investment (y/y f/c -10 from -9.4 – ACY Finlogix). Australia releases its Mid-Year Economic and Fiscal Outlook (FX Street). Europe follows with Germany’s December IFO Business Climate (f/c 87.8 from 87.3 previously – ACY Finlogix), German December IFO Expectations (f/c 85.8 from 85.2 – FX Street) and German December IFO Current Assessment (f/c 89.5 from 89.4 – ACY Finlogix). Germany’s Bundesbank releases its monthly report. Canada starts off North America with its Canadian National Housing Price Index (NHPI – f/c 0.1% from 0.0% - Forex Factory). The US rounds up today’s data releases with its NAHB Housing Market Index (f/c 36 from 34 – ACY Finlogix).
Trading Perspective: After falling for most of the week, the US Dollar reversed its losses on the back of hawkish rhetoric from a couple of Federal Reserve Heads (see Summary). On the week however the Greenback is lower against most of its Rivals. Markets will be focusing their attention on this week’s upcoming Bank of Japan policy meeting tomorrow (19 December). Which will be the final one for the BOJ this year. Other notable events this week include the release of Australia’s latest RBA Monetary Policy Meeting Minutes (Tuesday, 19 December) and US Final Q3 GDP and US Core PCE Price Index (Friday, 22 December). Expect the Dollar to consolidate its gains at current levels with the possibility of more volatile trade ahead.
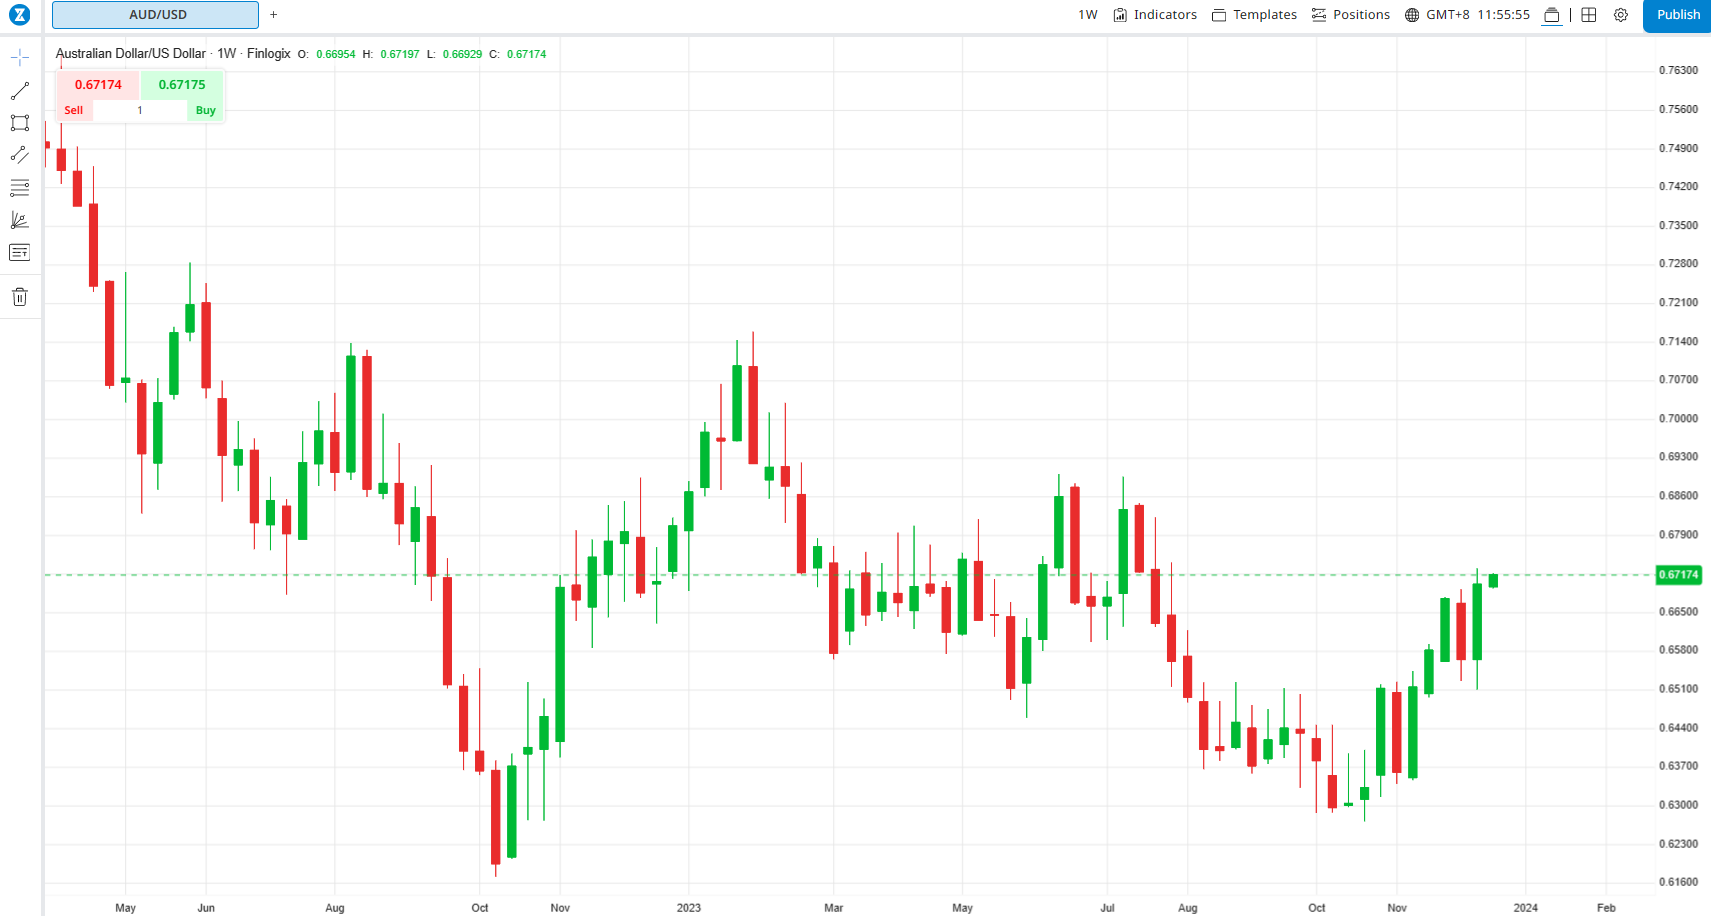
(Source: Finlogix.com)
Have a good Monday and trading week ahead all.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Theorem has integrated Symbiotic’s Liquid Lane RFQ network, letting holders of tokenised real-world assets trade against on-chain pool liquidity and market-maker quotes. The integration is live on Ethereum, with Midas’s yield-bearing mHYPER fund as the first supported asset. Holders can trade for the USDC stablecoin.
US equities were volatile with technology selloff erasing much of the earlier rebound.
FM Summit London 2026 returns to Old Billingsgate on 24 November for its 15th edition, with LMAX Group, Plus500 and oneZero among confirmed exhibitors. The one-day event adds Business Connect meetings and roundtables, and opens with a networking evening at The Folly on 23 November.
Finance Magnates Summit London returns to Old Billingsgate on 24 November 2026 for its 15th edition. The one-day event brings together brokers, liquidity providers, institutional firms, trading technology vendors, payments businesses and digital asset firms.
iSAM Securities Apex has integrated with Match-Prime, giving brokers access to liquidity across more than 2,000 instruments, with tailored pricing and up to 10 levels of market depth.
propfunding.com's free-entry instant funding changes the order of prop funding. Start trading first. Its free-entry instant funding model offers two qualification attempts without an upfront activation fee.
US stocks closed higher on Wednesday, with the Nasdaq gaining 1%, the S&P 500 rising 0.6%, and the Dow advancing 0.7%, as renewed enthusiasm for AI-related stocks lifted market sentiment.
SpaceX went public in June as a rocket company. On October 20 it reported as something else entirely: an AI infrastructure business, financed by a satellite broadband network, with a launch division attached. Rockets generated 12% of third quarter revenue and lost money. The AI segment generated 52% of revenue and consumed 84% of capital expenditure. Starlink generated 85% of operating profit.
Standard Chartered has signed definitive agreements to acquire 100% of Zodia Custody UK Limited, folding its regulated digital asset custody business into Securities Services. Zodia Solutions will be set up under SC Ventures with bank investors including Northern Trust, NAB Ventures, Emirates NBD and Investcorp.
Bybit Fintech FZE has secured a Virtual Asset Service Provider licence from Dubai’s Virtual Assets Regulatory Authority for Exchange Services, covering spot trading. Bybit’s Peter Loo said the firm hopes to add derivatives, subject to regulatory approvals. Its international Dubai headquarters opened in 2022.