just now


Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

In summary, the Federal Reserve holds a much greater influence on the financial markets compared to other central banks. Both the Fed and the US Treasury are keen on keeping yields from rising too high. Weak economic data from around the world is not surprising, but weak data within the United States can significantly impact the markets.
As the week begins, we observe lower yields, stronger stock performance, a decrease in oil prices, a weaker US dollar, and diminished strength in the Japanese yen (JPY) and Swiss franc (CHF). Among G10 currencies, the Australian dollar (AUD), New Zealand dollar (NZD), and Canadian dollar (CAD) are the top performers, while emerging market currencies have gained ground. It is still too early to determine if this marks a reversal of the trends that began at the end of July and accelerated this fall, but it appears to be a consistent start.
Three key factors underlie the market movements this week, all of which are related to the United States. Firstly, the dovish stance of the Fed, which made a significant impact with the inclusion of the word "financial" in its statement, indicating that the Fed views rising yields as part of its intended effect. This led the market to believe the Fed would not raise rates again in December, as this can be easily seen on the CME FEDWatch Tool, while 87.6% expects a pause again on 13 December only 12.4% expects a rate increase.
FEDWatch Tool
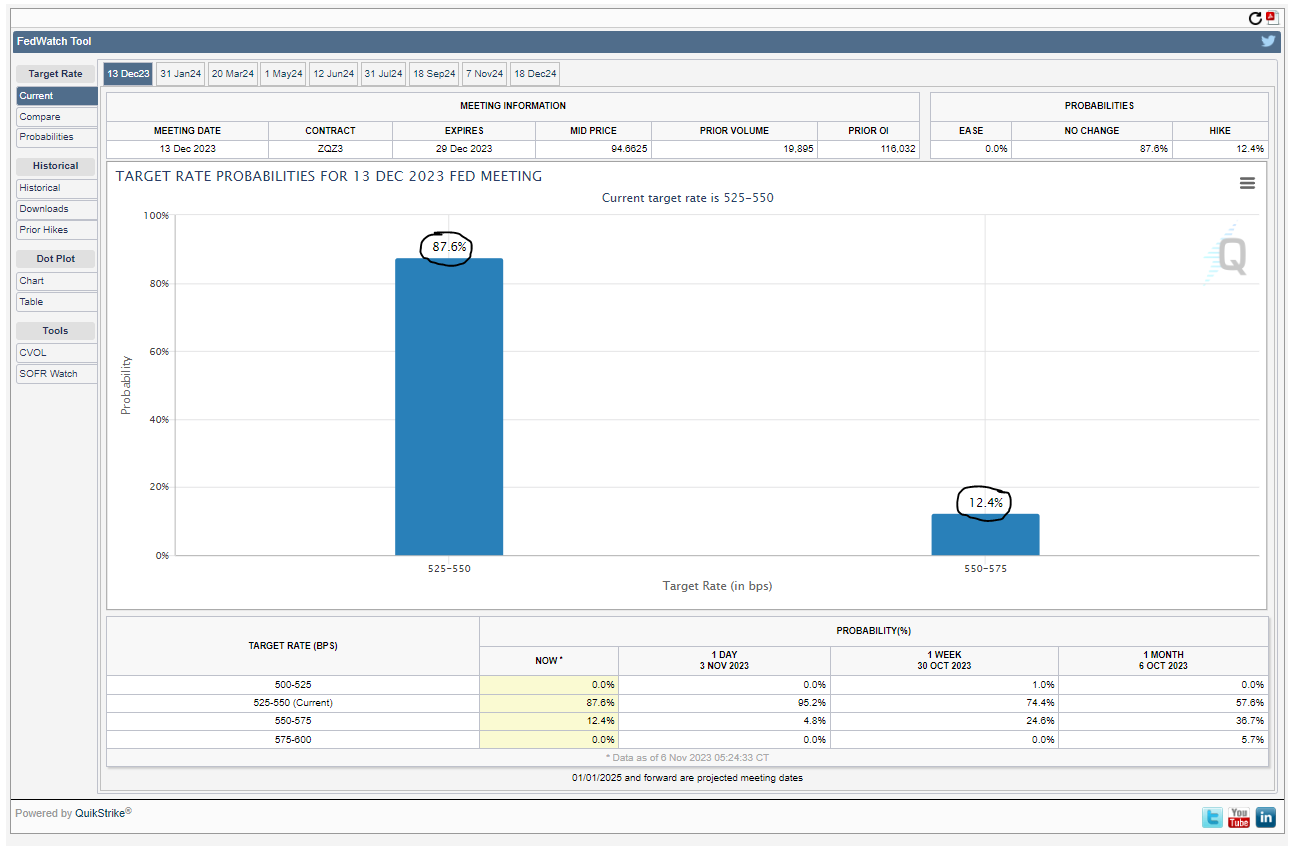
Source: CME
Secondly, the weaker economic data from the US, including disappointing ISM manufacturing and ADP employment figures, along with last Friday non-farm payrolls report, has raised concerns. Lastly, the US Treasury's surprise decision to provide lower-than-expected long-term supply in the November refunding was seen as a response to the recent increase in yields, signalling both the Fed and the US Treasury's efforts to counteract rising rates. (I’ve discussed this on my YouTube video you can watch it here:
)Despite the Bank of Japan (BoJ) taking steps to exit from yield targeting, the Japanese yen (JPY) is currently the weakest G10 currency. The BoJ's actions have not had a significant impact on the JPY, which aligns with my view that the USDJPY currency pair is primarily influenced by Federal Reserve policy, and it is expected to weaken only when the Fed contemplates rate cuts. The Swiss franc (CHF) is the second weakest performer in the G10, despite a slight uptick in core inflation. Geopolitical factors, such as the war in Israel, may be influencing CHF's performance, as Switzerland is the only G10 economy with both headline and core inflation below 2%. However, the Swiss National Bank (SNB) has been supporting the CHF by reducing its balance sheet. As the Israel conflict stabilizes and oil prices drop, the CHF may experience renewed weakening.
Here is my Central Bank Calls
US (FED)
Next Metting 13/12/2023
Consensus 5.38%
Narrative
I maintain my forecast of an additional 25 basis point (bp) interest rate hike in December, but this prediction has become less certain following the November meeting. I anticipate the first rate cut to occur in June 2024, with subsequent quarterly reductions of 25bp in the policy rate, resulting in a total of 75bp in rate cuts for the year 2024. Furthermore, I expect 100bp of rate cuts in 2025. I project the initial rate cut to take place in June 2024, and the Quantitative Tightening (QT) process is likely to conclude around the same time, although there is a possibility of an extended runoff period.
Europe (ECB)
Next Metting 14/12/2023
Consensus 4%
Narrative
My outlook entails no further interest rate hikes, and I anticipate the earliest possible rate cut to occur by June 2024. Following this, I expect a rate cut to take place every quarter. Additionally, I project that full reinvestments under the Pandemic Emergency Purchase Programme (PEPP) will cease in June 2024. As part of the operational framework review, I also anticipate mandatory reserve requirements to be adjusted to a range of 2-3%.
Japan (BoJ)
Next Metting 19/12/2023
Consensus -0.10%
Narrative
With the Bank of Japan (BoJ) now having increased its flexibility in managing the long end of the yield curve, I believe the central bank's next step will involve discontinuing Negative Interest Rate Policy (NIRP) and Yield Curve Control (YCC), although I expect them to maintain a safety net for yields. My positive outlook on inflation and wage growth has led me to anticipate a potential move between December 2023 and April 2024. The BoJ's recent communications have suggested a decreased likelihood of a move in December. However, I remain confident in my primary scenario, which envisions a change occurring at the Monetary Policy Meeting (MPM) scheduled for January 17-18, with the latest possible adjustment by April 2024.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.

Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
24X National Exchange has filed a proposed rule change with the SEC to launch 24X Options, a general options market trading from 9:30 a.m. to 4:00 p.m. ET. The filing also covers binary KPI options on quarterly revenue, earnings per share and other metrics for 23 of the most actively traded U.S. companies.
cTrader Mobile 5.11 introduces Signals, a new app where traders can browse signals from leading providers and act on them directly in the platform.
ATFX Group has partnered with South Africa-based payment and digital asset infrastructure provider FiveWest to support institutional fund movements for ATFX Connect and add a cryptocurrency funding option for eligible retail clients. Both firms hold FSCA Over-the-Counter Derivative Provider licences.
UK inflation rose to 3.6% in October, keeping a December Bank of England rate rise likely, while the euro hit a fresh one-year low against the dollar ahead of tonight’s Fed minutes. Daily FX analysis from Equals.
GBPUSD has shifted decisively lower. After reaching 1.3228, the pair reversed and initially consolidated around the moving averages before breaking sharply below the 1.3180 area. It is now trading near 1.3169.
Nvidia shares jumped around 4% after hours after beating earnings and revenue expectations and raising its outlook for 75% year on year revenue growth through January 2028. The positive Nvidia results also lifted AI-related stocks, with CoreWeave up 8% and Nebius 10%.
Deutsche Börse Group has appointed Maximilian Weissenrieder as Head of Cash Market from 1 January 2027, succeeding Eric Leupold, who becomes CEO of Eurex. Weissenrieder has led Group M&A and Venture Investments since October 2024 and will retain those duties until a successor is named by the Group.
DEXA, the AI-powered risk management and analytics platform developed by TFB (Tools for Brokers), has connected with Match-Trader, bringing real-time trader analysis and toxic flow detection to brokers on the platform. DEXA classifies trader behaviour from as early as the third trade, with no change to execution systems.
Poland's financial markets regulator, the Polish Financial Supervision Authority (Komisja Nadzoru Finansowego, KNF), is preparing a new product intervention on contracts for difference (CFDs)
Choosing an outsourced dealing desk is much closer to hiring a head of dealing than to buying a piece of software. You are handing an external team one of the most sensitive functions in your brokerage - your exposure, your routing, your clients' trading activity - so the decision should rest on evidence of how the team actually operates, not on how good the sales presentation looks.