just now
Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
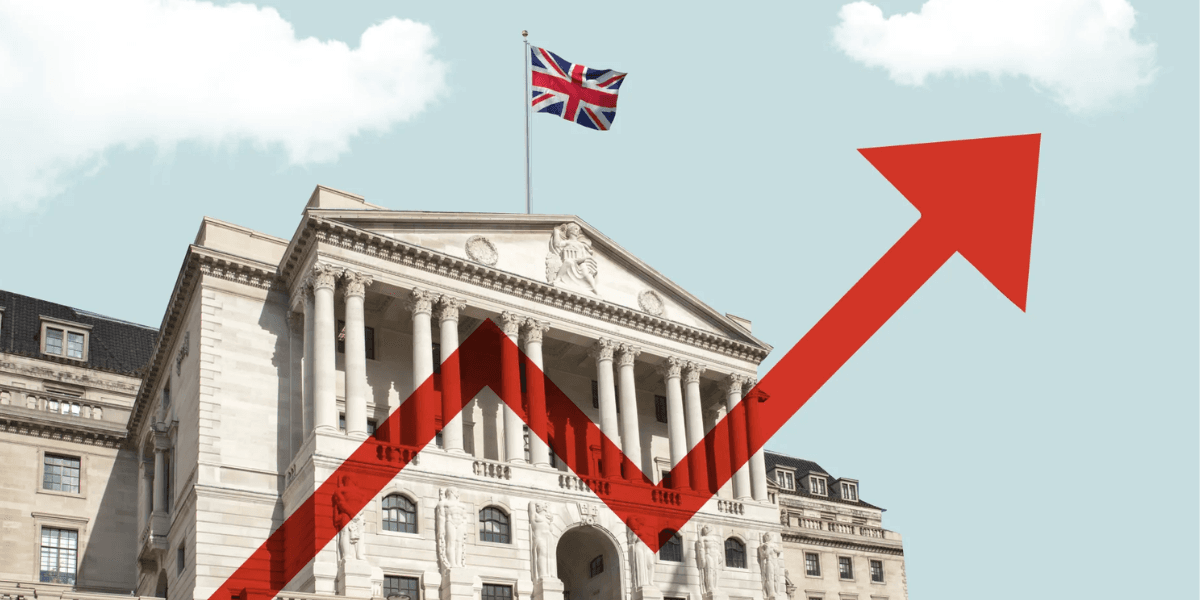
March 21, 2023 - The UK’s October 2022 inflation figure printed at a 40-yr high of 11.1%, highlighting the strength of pricing pressures being experienced in the UK. With real wages falling, pressure is being felt not just by the Bank of England (BoE) to bring inflation back under control, but also by the UK government as it tries to find ways to shield households from this erosion in living standards.
For the BoE, this failure to control inflation has seen its role as the UK’s monetary guardian questioned. Admittedly, a significant element of the pricing pressures seen have their origins overseas, such as the increases seen in global energy prices and Covid-disrupted supply chains. But the BoE cannot hide from the fact that as recently as just over one year ago, the Monetary Policy Committee (MPC) was continuing to claim that inflationary pressures were transitory and that CPI would fall back to target of its own accord, given time, without the need for an aggressive monetary response. Even when the market was warning that inflationary pressures were becoming increasingly embedded, the MPC chose to ignore them and instead do nothing, remaining convinced by its own arguments.
Accelerating inflation
The result of this inaction was clearly seen in 2021, when CPI accelerated from 0.7% in the January to 5.4% by December, a level nearly three times higher than the BoE’s mandated 2% target. Yet it was not until that December that the MPC finally accepted that inflationary pressures were not actually transitory but would require action to bring back under control. Its response was to hike interest rates by 0.15%, in hindsight a too small amount delivered too late, and which had minimal impact.
What makes the BoE’s policy response – or lack thereof – more puzzling is that 2020 had seen an unprecedented contraction in aggregate supply as Covid lockdown restrictions were imposed. At the same time, a huge boost to aggregate demand was subsequently provided by the UK government through various mechanisms such as the jobs furlough programme and the “eat out to help out” scheme. Combined with the supply chain distortions being seen at the time, it is difficult to understand why the MPC thought these supply and demand imbalances would not have led to a surge in inflation once lockdown restrictions were lifted. Even with the benefit of hindsight, the MPC allowed itself to get too far behind the policy curve; by the time it realised its mistake, the inflation genie had fled its bottle.
The consequences are now being felt
The damaging consequences of this policy error have been clearly felt over the past year. CPI exceeded forecasts some eight times in 2022 alone, climbing to 11.1% in October before starting to ease back again, albeit slowly. At the same time, real incomes have taken a battering and led to growing industrial unrest as trade unions have resorted to strike action to try and secure pay increases that at least match the rising cost of living. And while this has happened, so the MPC has been required to aggressively tighten policy, raising interest rates from 0.25% to 4.0% in just nine meetings and seeing the market now expecting a terminal rate of 4.50% to be reached by end-H1 this year. Any fears BoE officials may have been secretly harbouring that a lack of monetary action was risking inflation getting out of control were realised by the MPC.
Ultimately, the ‘transitory inflation’ story was rightly abandoned. But it left the MPC behind the curve in terms of where interest rates needed to be as inflation climbed higher. Even today, the real interest remains negative at -6.1%, suggesting there remains a need for further tightening still.
Did fears concerning growth stay the MPC’s hand?
One reason frequently offered for the timid response to fighting inflation has been the deteriorating UK growth outlook, the MPC unwilling to tighten policy for fear of exacerbating the expected economic slowdown. But supporting growth is not the MPC’s role; it is only required to ensure the 2% inflation target is met and is tasked with achieving that objective only: maximising economic output falls under the remit of the UK Treasury and fiscal policy, not the BoE.
Has the UK Government come to the BoE’s aid?
The most recent BoE forecast for CPI (February 2023) showed inflation on a downwards trajectory, falling to 3.0% by Q1 2024 and 1.0% by Q1 2025, if interest rates rise in line with market projections. A key factor behind this rapid deceleration may be the fallout from the Truss/Kwarteng ‘mini-budget’ of end-October 2022. Designed to boost UK output, the degree of new borrowing it required frightened the markets, triggering a rapid financial tightening as gilt yields soared and interest-rate sensitive products such as mortgage rates rose steeply. With the need to restore confidence in the UK economy suddenly paramount, the subsequent Sunak/Hunt fiscal statement delivered in the November cast any concerns about growth to the wind. Virtually all the easing measures in the Truss/Kwarteng budget were removed, but at a cost of also removing some £50bn-worth of demand from the economy via a policy of aggressive tax hikes. But crucially the key measure of capping household energy bills was retained, the NIESR estimating this measure alone will lower CPI over the course of 2023 by some 3%-4%. Not only did the November statement assist the BoE in removing demand from the economy, it also single-handedly lowered headline CPI. Possibly an argument can be made that the government inadvertently came to the BoE’s aid.
But it is under the BoE’s current stewardship that control of CPI has been lost
But this does not detract from the fact that it is under the BoE’s current stewardship that control over inflation has been lost. The previous BoE Chief Economist, Andy Haldane, warned repeatedly in 2021 that the MPC was being too lax in addressing the potential inflationary threats facing the UK. Yet he was ignored, including by current Governor Andrew Bailey, who was unwilling to acknowledge any kind of inflation threat and instead opted to continue with the policy of monetary stimulus. Even the modest easing in CPI seen since October is more likely the result of falling energy prices and easing global supply chains – things over which the BoE has no control – rather than a consequence of the tightening the Bailey-led MPC has belatedly delivered.
Does the BoE need a new hand on the tiller?
Bailey’s tenure as BoE Governor has not been a smooth one. Criticisms were made of him in his previous role as Chairman of the FCA and more latterly in his communications with the market over monetary policy and the need for wage restraint from lower paid sections of society. Under him, the BoE is meant to have the key ‘birds’ eye’ view on all things inflationary, afforded to it by the huge volume of official data it has access to that is not available to others. But if the BoE is unable to decipher and interpret this information correctly – incorrectly believing rising inflation was transitory rather than sustained - or allows the data to perhaps fit its own arguments, where does that leave the UK in its battle to control inflation? Perhaps it is time to pass responsibility for ensuring price stability on to another institution - or, at a minimum, to possibly put another person in charge at the helm of the BoE/MPC?
Equiti Capital UK Limited began trading operations in 2008. We offer accessible Prime Brokerage services with real liquidity from top tier banks and ECN venues. We have invested heavily in our trading technology and partnered with the biggest liquidity providers globally allowing us to deliver a unique range of services to our Clients. Equiti Capital UK Limited's continued focus on exceptional customer support and innovative liquidity solutions has allowed us to become the prime brokerage of choice for a diverse range of clients.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Bybit has launched Perp Options, described as the first options contracts built on TradFi perpetuals, giving traders round-the-clock access to US equity options. SpaceX and Nvidia are the first underlying assets, with USDT settlement and integration into Bybit's Unified Trading Account.
Use this trading preparation checklist to plan your session, define entry rules, manage risk, and build a disciplined trading routine in seven steps.
Your Bourse expands its crypto liquidity ecosystem with Caladan, giving brokers access to broader market coverage, institutional execution capacity and streamlined settlement.
Scope Markets, the retail brokerage part of Rostro Group, has appointed Ibrahim Hossny as Head of Research and Marketing for the Middle East and North Africa.
Hantec Prime, the institutional division of Hantec Markets, has reported trading volume up more than 300% year-to-date, alongside the addition of 42 new institutional clients since December, capping one of its strongest years of growth to date.
Learn how to refine XAUUSD support and resistance on the daily chart using candle bodies, market structure and weekly gold levels for swing trading. A slug alone cannot guarantee a top Google ranking. Keep it focused rather than adding every supporting keyword.
The week in Dubai will be focused on connecting directly with the industry and discussing how technology can help modern brokerages simplify operations, automate workflows, strengthen operational control, and scale efficiently.
Devexperts has launched a turnkey solution giving brokers in South Korea access to US equity markets, combining its DXtrade trading platform, dxFeed market data, and execution services. The offering targets South Korea's growing retail demand for US stocks, worth several billion USD monthly.
Assess why WTI crude oil surged past $105 per barrel amid Saudi pipeline disruptions, record tanker charter rates, and escalating geopolitical tensions.
Bitcoin price forecast: BTC/USD retests $78,460–$80,215 resistance. Watch bearish confirmation toward $72,480 or a bullish breakout toward $86,150.