just now
Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
The relentless ascent in US bond yields persists, yet there are emerging indications that this surge is beginning to exert a more pronounced influence on market risk sentiment. This development wasn't entirely unexpected; the only uncertainty lay in the timing. The S&P 500, for instance, experienced a 1.5% decline in its value yesterday, a decline largely attributed to the surge in yields. The US 10-year UST bond yield surged to a new peak of 4.56%, although it has since retreated slightly. This represents a 51-basis point increase from its intra-day low on September 1st. In September alone, the S&P 500 has declined by 5.2%, and it is now 7.2% below the record intra-day high recorded on July 27th.
In addition to the ongoing rise in yields, two other factors may have contributed to this downturn in the equity markets. Firstly, there has been a deterioration in consumer sentiment, marked by a significant drop in expectations. While the decline in overall confidence (from 108.7 to 103.0) was notable, the more substantial decline was observed in expectations, which fell by nearly 10 points to 73.7. When comparing the present conditions index with the expectations index, it becomes evident that the breakdown aligns with conditions indicative of a potential recession. If gasoline prices continue to rise and equity markets continue to fall, it could further erode consumer expectations and dampen their willingness to spend. If yields continue their upward trajectory, we may soon witness even more substantial declines in the equity markets, which would have repercussions for the US economy's primary driver—consumer spending. Furthermore, it's possible that expectations could be dragged even lower as consumers gradually deplete their pandemic-related excess savings. According to estimates from the San Francisco Fed, these savings could decline from over USD 2.0 trillion to as little as USD 190 billion by June.
The second factor at play is the impending government shutdown. The 2018 government shutdown, which lasted 34 days, did not significantly impact the real economy or the markets. December 2018 saw a substantial equity market downturn, largely attributed to various global factors, and FED tightening, but the shutdown itself did not play a major role. However, the dollar did weaken by over 2.0% during that shutdown period. While a shutdown certainly doesn't bode well for market sentiment, its impact may become more significant if it persists longer than the 2018 shutdown, potentially affecting up to 1 million government workers. This time around, the shutdown is anticipated to have a broader impact than in 2018. Currently, the US dollar remains on its strengthening trajectory, albeit at a stretched level, as evidenced by the DXY index recording ten consecutive weeks of gains last week. It's possible that an increasingly attention-grabbing government shutdown could serve as a catalyst for at least a temporary correction in the dollar's strength. Nevertheless, a decline in yields driven by equity market pressures appears to be a more plausible trigger for a reversal in foreign exchange markets, with the 10-year yield currently 5 basis points lower than its peak yesterday.
JPY & CNY
Japan's Finance Minister Suzuki has once again addressed the foreign exchange (FX) market, expressing a "strong sense of urgency" in monitoring currency movements, particularly after USD/JPY breached the 149-level. It's noteworthy that Japanese Ministry of Finance (MoF) officials are now communicating on yen fluctuations with increasing frequency, and their choice of words suggests a heightened likelihood of actual intervention. However, one significant hurdle to immediate intervention is the absence of "rapid" or "disorderly" FX movements. Stepping in at this stage might reinforce the perception of defending a specific level (150.00) rather than addressing market volatility.
Furthermore, there are limited signs of speculative activity driving these currency moves. Weekly data from the International Money Market (IMM) does not indicate an increased appetite for selling JPY at these levels. Additionally, while the yen is underperforming, the Bank of Japan's Nominal Effective Exchange Rate (NEER) has experienced only modest weakness, declining by just 0.6% in September. The likelihood of intervention remains high, but it may materialize only after a break above the 150-level, as this scenario would carry a higher risk of triggering stop orders, potentially fuelling volatility and justifying MoF intervention.
In a related context, Chinese authorities have also stepped up their efforts to counter CNY (Chinese Yuan) weakness. These actions could assist Tokyo in its efforts to limit JPY depreciation. The People's Bank of China (PBoC) issued a statement emphasizing its commitment to maintaining a "basically stable" FX rate and correcting "one-sided and pro-cyclical behaviours." Bloomberg reported that China's state banks have been actively selling US dollars in the onshore FX market, while their overseas branches have reduced CNH (offshore CNY) lending to tighten liquidity and support the currency offshore. These measures continue despite the ongoing broad strength of the US dollar.
These efforts are bolstered by positive economic data released today from China. Industrial profits in China rose by 17.2% on an annual basis in August, marking the first positive annual reading in over a year and suggesting signs of economic stabilization. Industrial production also showed improvement in August, further indicating that policy support measures may be contributing to growth support. Despite the prevailing momentum of the US dollar, the risks for both USD/JPY and USD/CNY still lean toward the upside, but the opposition to currency weakness in both Tokyo and Beijing remains resolute.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Dubai-based financial derivatives group MultiBank Group has appointed former Crypto.com executive Mohammed Al Hakim as Vice Chairman of MultiBank Group and CEO of MB.io,
Interbank trading venue MultiBank Exchange, part of Dubai-based financial derivatives group MultiBank Group, has unveiled what it describes as the world’s first interbank trading platform to offer double exotic currency pairs with settlement in both fiat currencies and digital assets.
Multibank FX aggregation service FXSpotStream (@FXSpotStream) reported an overall average daily volume (ADV) of USD 163.217 billion for October 2026.
Eurex Clearing is to bring native digital instruments into its existing clearing framework. It says this will make it the world’s first hybrid central counterparty (CCP).
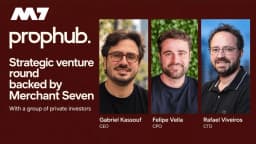
Brazil-based PropHub has secured strategic backing from Merchant Seven and private investors to expand its modular trading technology, strengthen sales and marketing, and accelerate international growth.
Devexperts hosted its first Trading Industry Leaders Lunch in Jakarta on 29 October, with more than 30 Indonesian capital markets figures discussing investor confidence, market integrity and trading infrastructure, following Bappebti approval of its flagship DXtrade multi-asset trading platform in August 2026.
Spotware Systems will be present at The Trading Festival Mexico 2026 on 12–13 November at the World Trade Center in Mexico City, Booth B1, introducing the latest updates to its flagship platform, cTrader.
Capital.com's Singapore unit is now listed by the Monetary Authority of Singapore as a Capital Markets Services licensee, with permissions covering securities, collective investment schemes, OTC derivatives and custody. The entry names former IG Singapore head Tony Lim as chief executive of the Singapore entity.
ICM MENA has promoted Firas Bechwaty to Head of Business Development. He joined in July 2022 as Business Development Executive and became Business Development Manager in August 2024. He previously worked in account management for over five years. Shoaib Abedi, Founder and Chairman, ICM MENA, commented on the promotion.
Euronext's Supervisory Board intends to nominate NN Group CEO David Knibbe as Chief Executive Officer and Chairman of the Managing Board at its AGM on 20 May 2027, following Stéphane Boujnah's decision to step down. The appointment requires approval from regulators, the Dutch Minister of Finance and Euronext shareholders.