just now


Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
Markets have entered a period of heightened fragility, with risk sentiment caught in the crossfire between geopolitical tensions in the Middle East and an increasingly uncertain monetary policy backdrop in the U.S. and Europe. While the headlines remain dominated by the Israel-Iran conflict and its broader ramifications, market participants are also recalibrating expectations around central bank actions especially the Federal Reserve following persistent signs of sticky inflation.
Let’s start with the geopolitical front. The recent flare-up involving Iran’s retaliatory strike on Israel was initially met with market fear, but asset prices quickly rebalanced once it became clear that both sides were keen to avoid an all-out war. Despite the temporary shock, financial markets interpreted the action as largely symbolic. Oil prices spiked momentarily but failed to sustain momentum, reflecting both ample supply buffers and a perception that the conflict, for now, lacks the kind of escalation risk that would severely threaten energy flows.
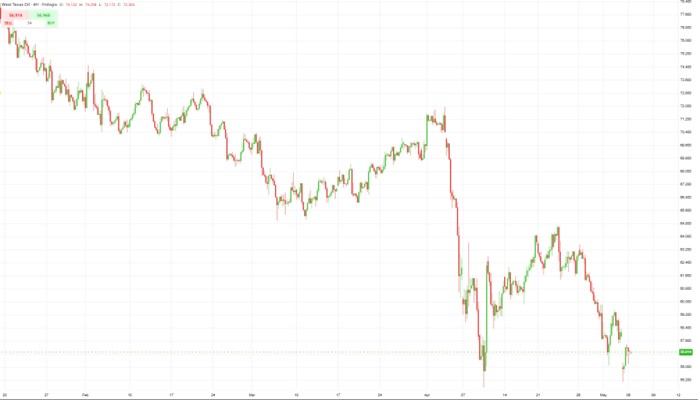
However, we shouldn't be complacent. While diplomacy may be containing immediate fallout, the situation remains fluid. Any miscalculation could reignite volatility, particularly in oil markets. It's worth noting that Brent crude still trades with a geopolitical risk premium embedded, and any sudden deterioration could renew upward pressure on prices something central banks will be closely watching.
On the monetary policy side, the Fed’s path forward is becoming increasingly murky. After a string of hotter-than-expected CPI prints, the disinflation narrative is under pressure. March inflation, for instance, showed renewed momentum in core services, reinforcing the notion that inflation is proving more persistent than policymakers anticipated. As a result, market pricing for rate cuts has shifted significantly from as many as six cuts expected at the start of the year to perhaps just one or two now being priced in.
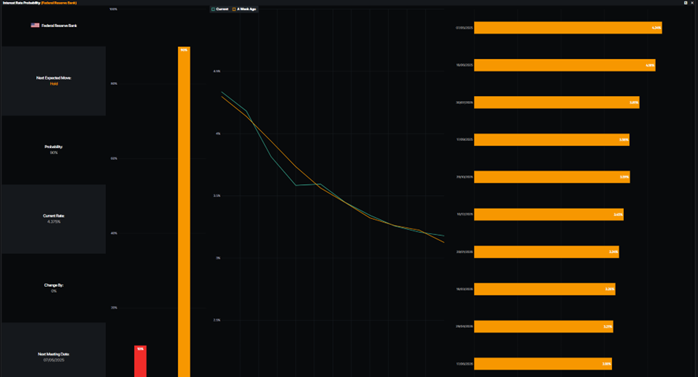
Fed Chair Powell has maintained a cautious stance, emphasizing the need for more evidence before committing to any easing cycle. This aligns with recent speeches from other FOMC members, who have flagged concerns about reacceleration risks and urged patience. Simply put, the bar for rate cuts has risen.
Global markets are now repricing accordingly. U.S. yields have climbed, the dollar has regained some strength, and equities while still supported by strong earnings are showing signs of stress at the margin, especially in rate-sensitive sectors. The message is clear: monetary easing is not a given.
Across the Atlantic, the European Central Bank is still hinting at a June rate cut, but that too depends on upcoming data. Wage dynamics in Europe remain a concern, and like the Fed, the ECB doesn't want to move prematurely and risk a resurgence of inflation pressures.
Layered atop these macro variables is the ever-present role of energy markets. While the initial Middle East escalation didn’t produce a sustained oil rally, the structural tightness in crude markets remains relevant. Inventories are below average, OPEC+ production discipline persists, and demand forecasts are being revised upward, especially as China stabilizes and global air travel rebounds.
Adding to the mix is the shift in investor sentiment toward gold. In the face of geopolitical uncertainty and doubts about the timing of rate cuts, gold has surged to record highs, supported by strong central bank demand and growing retail interest. It’s a sign that investors are seeking hedges not just against inflation, but against broader systemic risks.
We’re navigating a market regime where binary outcomes are increasingly possible. Either inflation cools convincingly, unlocking rate cuts and supporting risk assets, or it persists forcing central banks into a prolonged holding pattern. Meanwhile, any flare-up in geopolitical tensions could upset even the most well-laid forecasts.
In this kind of environment, flexibility is paramount. Portfolio strategies need to balance duration risk with inflation hedges, maintain exposure to real assets like commodities and gold, and remain nimble in FX particularly as the dollar's path becomes more data dependent.
The weeks ahead will be pivotal. U.S. CPI, PCE inflation, and any fresh signals from the Fed could reshape the outlook again. Simultaneously, the Middle East remains a wild card, and oil traders will be watching every headline.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplies by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.

Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Brokers can offer LMAX perpetual futures alongside FX and CFDs through a single trading account. LMAX says brokers with existing credentials can go live in under five days.
24X National Exchange has filed a proposed rule change with the SEC to launch 24X Options, a general options market trading from 9:30 a.m. to 4:00 p.m. ET. The filing also covers binary KPI options on quarterly revenue, earnings per share and other metrics for 23 of the most actively traded U.S. companies.
cTrader Mobile 5.11 introduces Signals, a new app where traders can browse signals from leading providers and act on them directly in the platform.
ATFX Group has partnered with South Africa-based payment and digital asset infrastructure provider FiveWest to support institutional fund movements for ATFX Connect and add a cryptocurrency funding option for eligible retail clients. Both firms hold FSCA Over-the-Counter Derivative Provider licences.
UK inflation rose to 3.6% in October, keeping a December Bank of England rate rise likely, while the euro hit a fresh one-year low against the dollar ahead of tonight’s Fed minutes. Daily FX analysis from Equals.
GBPUSD has shifted decisively lower. After reaching 1.3228, the pair reversed and initially consolidated around the moving averages before breaking sharply below the 1.3180 area. It is now trading near 1.3169.
Nvidia shares jumped around 4% after hours after beating earnings and revenue expectations and raising its outlook for 75% year on year revenue growth through January 2028. The positive Nvidia results also lifted AI-related stocks, with CoreWeave up 8% and Nebius 10%.
Deutsche Börse Group has appointed Maximilian Weissenrieder as Head of Cash Market from 1 January 2027, succeeding Eric Leupold, who becomes CEO of Eurex. Weissenrieder has led Group M&A and Venture Investments since October 2024 and will retain those duties until a successor is named by the Group.
DEXA, the AI-powered risk management and analytics platform developed by TFB (Tools for Brokers), has connected with Match-Trader, bringing real-time trader analysis and toxic flow detection to brokers on the platform. DEXA classifies trader behaviour from as early as the third trade, with no change to execution systems.
Poland's financial markets regulator, the Polish Financial Supervision Authority (Komisja Nadzoru Finansowego, KNF), is preparing a new product intervention on contracts for difference (CFDs)