just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
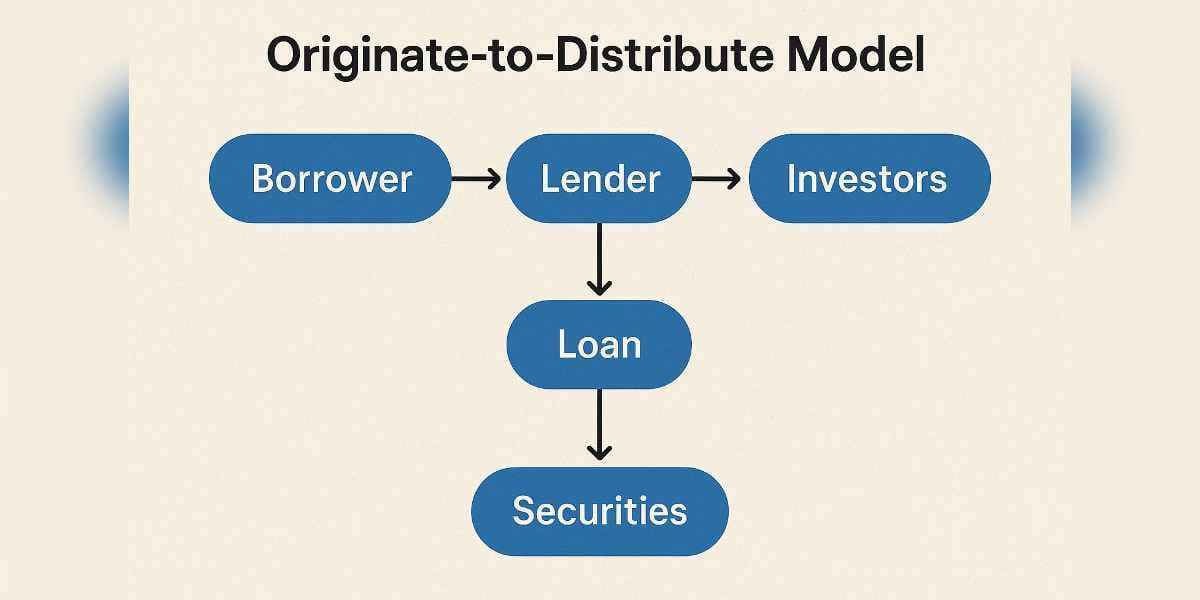
The OTD model is a modern banking approach where banks originate loans but quickly sell them to investors or package them into securities (like ABS or CDOs), rather than holding them until maturity. This model has expanded from mortgages to credit cards, auto loans, student loans, and corporate lending.
Banks benefit from diversified funding by accessing a broader pool of investors beyond traditional depositors. This expansion allows them to tap into various capital markets and investor types, enhancing their financial flexibility and resilience.
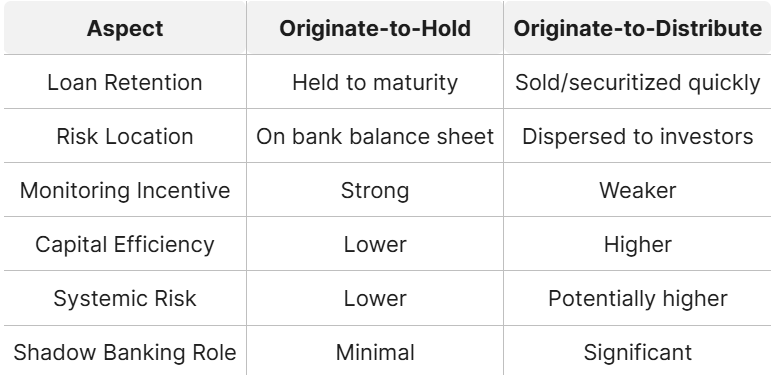
The dispersion of credit risk across many market participants reduces the concentration of risk within any single institution. By distributing loans to a wide range of investors, banks help mitigate systemic vulnerabilities that could arise from localized credit exposures.
Selling loans also improves capital efficiency for banks. By offloading loans from their balance sheets, banks free up regulatory capital, which can then be redeployed to originate additional loans, supporting greater lending activity and economic growth.
Additionally, banks generate fee income through multiple channels in this model. They earn fees from originating loans, selling them to investors, and providing ongoing servicing such as collecting payments and managing the underlying assets, creating diversified revenue streams.
As banks increasingly adopt the originate-to-distribute (OTD) model, one significant consequence has been the weakening of lending standards. Since banks no longer retain the majority of the risk associated with the loans they originate, their incentive to thoroughly screen and monitor borrowers diminishes. This shift can lead to a greater prevalence of lower-quality loans entering the financial system, as originators may prioritize loan volume over credit quality, knowing that much of the risk will be transferred to third-party investors.
The growth of shadow banking is another critical development linked to the OTD model. Nonbank entities such as collateralized loan obligations (CLOs) and investment managers now hold substantial portions of credit risk that was once concentrated within regulated banks. These nonbank financial intermediaries often operate with less regulatory oversight, which can obscure the true location and magnitude of risk within the broader financial system. This shift has contributed to the expansion of the so-called "shadow banking" sector, raising concerns about financial stability and transparency.
Liquidity risks have also become more pronounced under the OTD model. Banks that rely heavily on securitization markets for funding are vulnerable to sudden drops in investor demand for structured products. This vulnerability was starkly demonstrated during the 2007–2008 financial crisis, when the market for asset-backed securities seized up, leaving banks unable to sell or refinance their loans. The resulting liquidity squeeze forced some banks to seek emergency funding or absorb unexpected losses, highlighting the fragility of this funding model during periods of market stress.
Finally, the potential for credit crunches is an inherent risk in the OTD framework. If the secondary market for loans and structured products freezes, banks may be compelled to retain loans they had intended to distribute. This scenario can strain bank balance sheets, reduce their lending capacity, and ultimately restrict the flow of credit to the real economy. Such disruptions can amplify economic downturns, as seen in past crises, underscoring the importance of robust risk management and regulatory oversight in an environment increasingly shaped by the originate-to-distribute model.
In recent years, banks have significantly reduced the proportion of term loans they retain on their balance sheets. Instead of holding these loans until maturity, banks now sell or securitize the majority of them, transferring much of the associated credit risk to nonbank investors such as collateralized loan obligations (CLOs), investment funds, and other institutional players. This shift has fundamentally altered the risk landscape of the financial system, as nonbank entities now play a much larger role in absorbing and managing credit risk.
The distribution of loans by banks is increasingly purpose-driven. Banks are more likely to offload loans that are considered riskier, such as those issued for mergers and acquisitions (M&A), into the secondary market. These loans typically carry higher risk profiles and are more attractive for securitization and sale. In contrast, banks tend to retain a greater share of loans used for capital expenditures, which are generally viewed as less risky and more stable. This selective approach reflects both regulatory considerations and the banks’ own risk management strategies, as well as investor appetite for higher-yielding, riskier assets.
Despite the lessons from past financial crises, the originate-to-distribute (OTD) model remains a central feature of large-scale lending, especially in the United States and Europe. The model’s efficiency in freeing up bank capital and supporting high volumes of lending has ensured its continued use. However, the growing reliance on nonbank investors and the evolving complexity of structured finance products continue to pose challenges for financial stability, making robust risk management and regulatory oversight more important than ever.
Samantha Lee, Chief Credit Strategist at GlobalBank:
“The OTD model has proven resilient, but recent market volatility highlights the need for banks to maintain strong underwriting standards even when they don’t hold the loans long-term.”
Dr. Rajiv Menon, Financial Stability Advisor, ECB:
“Supervisors are increasingly focused on transparency and stress-testing in the securitization market. The lessons of 2008 are clear: risk must be understood and managed, not just transferred.”
Elena Garcia, CEO of FinTech Analytics:“
Advanced analytics and AI are helping banks better assess borrower risk, even in an OTD framework. However, technology is no substitute for prudent risk culture.”
Michael O’Connor, Senior Partner, Capital Markets Advisory:
“Shadow banking continues to grow, and while it adds flexibility to the system, it also creates blind spots for regulators. The OTD model is at the heart of this evolution.”
Lisa Tan, Head of Fixed Income Research, EuroInvest:
“Periods of market stress still expose the fragility of structured products. Investors are demanding more transparency and simpler structures, which is a healthy development.”
The OTD model remains a pillar of modern banking, enabling greater lending and risk sharing. However, recent events and expert commentary underscore the ongoing need for robust risk management, transparency, and regulatory vigilance—especially as new technologies and market participants reshape the financial landscape.
We're the largest marketplace to connect with brokers, Fintech companies & digital asset firms. Want to partner? Let's get in touch.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Theorem has integrated Symbiotic’s Liquid Lane RFQ network, letting holders of tokenised real-world assets trade against on-chain pool liquidity and market-maker quotes. The integration is live on Ethereum, with Midas’s yield-bearing mHYPER fund as the first supported asset. Holders can trade for the USDC stablecoin.
US equities were volatile with technology selloff erasing much of the earlier rebound.
FM Summit London 2026 returns to Old Billingsgate on 24 November for its 15th edition, with LMAX Group, Plus500 and oneZero among confirmed exhibitors. The one-day event adds Business Connect meetings and roundtables, and opens with a networking evening at The Folly on 23 November.
Finance Magnates Summit London returns to Old Billingsgate on 24 November 2026 for its 15th edition. The one-day event brings together brokers, liquidity providers, institutional firms, trading technology vendors, payments businesses and digital asset firms.
iSAM Securities Apex has integrated with Match-Prime, giving brokers access to liquidity across more than 2,000 instruments, with tailored pricing and up to 10 levels of market depth.
propfunding.com's free-entry instant funding changes the order of prop funding. Start trading first. Its free-entry instant funding model offers two qualification attempts without an upfront activation fee.
US stocks closed higher on Wednesday, with the Nasdaq gaining 1%, the S&P 500 rising 0.6%, and the Dow advancing 0.7%, as renewed enthusiasm for AI-related stocks lifted market sentiment.
SpaceX went public in June as a rocket company. On October 20 it reported as something else entirely: an AI infrastructure business, financed by a satellite broadband network, with a launch division attached. Rockets generated 12% of third quarter revenue and lost money. The AI segment generated 52% of revenue and consumed 84% of capital expenditure. Starlink generated 85% of operating profit.
Standard Chartered has signed definitive agreements to acquire 100% of Zodia Custody UK Limited, folding its regulated digital asset custody business into Securities Services. Zodia Solutions will be set up under SC Ventures with bank investors including Northern Trust, NAB Ventures, Emirates NBD and Investcorp.
Bybit Fintech FZE has secured a Virtual Asset Service Provider licence from Dubai’s Virtual Assets Regulatory Authority for Exchange Services, covering spot trading. Bybit’s Peter Loo said the firm hopes to add derivatives, subject to regulatory approvals. Its international Dubai headquarters opened in 2022.