just now


Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

As the currency markets digest a myriad of macroeconomic signals, fiscal narratives, and central bank recalibrations, we find ourselves at a crucial juncture marked by policy divergence, re-pricing of inflation expectations, and latent geopolitical stress. In this piece, I reflect on recent institutional insights not to echo them, but to interpret them through a refined lens with practical implications for the trading floor and the strategy desk.
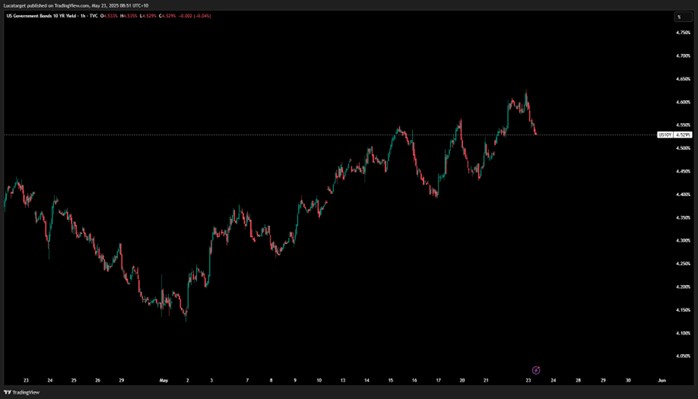
Despite the upward pressure in long-end U.S. yields post-auction, the dollar has failed to break convincingly in either direction, leaving traders caught between momentum and macro. The market appears uncomfortable with the absence of a clear catalyst the kind that historically jolts dollar flows into alignment with yield spreads. Instead, a "sell America" undertone lingers in the background, quietly reasserting itself in cross-asset rotation.
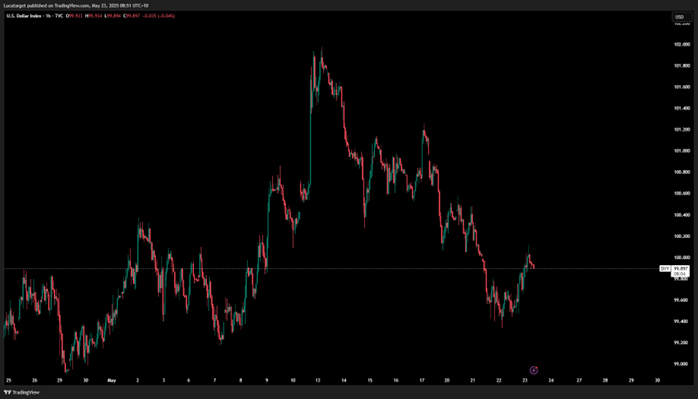
The DXY’s close below the 100 level hints at further downside, yet conviction remains elusive. This muted response speaks volumes: real money accounts are selectively de-risking, but without the urgency that typically accompanies a trend break. Until the U.S. fiscal trajectory sharpens or a liquidity event occurs, we remain defensively short the dollar, primarily against the euro and commodity-linked currencies.
Sterling is facing an identity crisis. While recent UK inflation data and auction dynamics have spurred brief rallies, fiscal slippage and structural imbalances are rapidly taking centre stage. Markets were underwhelmed by the CPI print's implications especially with service price measures failing to decelerate as quickly as anticipated.
The pound’s behaviour suggests investors are now increasingly pricing in a slower disinflation path, coupled with political uncertainty. With EUR/GBP holding key support at 0.8375, we maintain a constructive view on euro longs against sterling, especially as the UK’s deficit widens and real yields adjust down.
The yen remains resilient, but not yet compelling. BoJ officials, including Noguchi, have reiterated a hands-off stance on the JGB market and no urgency for tightening, which creates an odd paradox. While JPY is firming on global risk sentiment and yield differentials, its inability to attract broad-based flows suggests a lack of conviction.
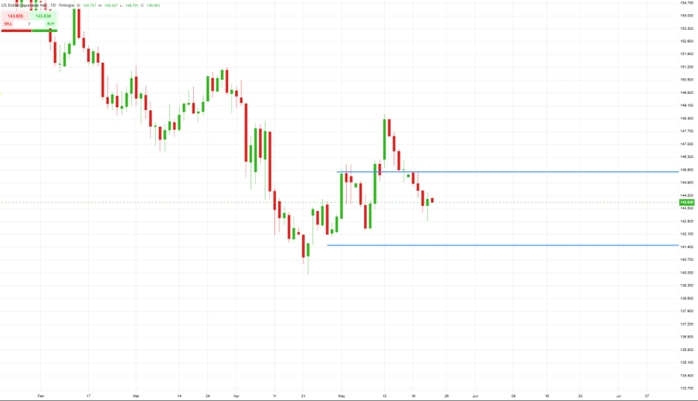
The USDJPY pair continues to hover in limbo between 141.50 and 145.50 a range that reflects market indecision rather than directional bias. In this context, we have reduced exposure to CHFJPY shorts and are watching positioning data closely. We expect yen dynamics to remain event-driven and reactive unless the BoJ alters course on balance sheet policy a low probability in Q2.
Despite the broader USD softness, the franc’s appreciation has hit a ceiling, particularly against the dollar and euro. This aligns with rising interest in CHF-funded carry trades positioning that is now visibly extended in AUDCHF and CHFJPY pairs.
While geopolitical tensions (notably Israel-Iran risks) and fiscal concerns in the U.S. may fuel intermittent bids for the franc, the appetite for short CHF exposure remains strong. We are neutral for now, awaiting a reversion in volatility or a macro event that recalibrates rate differentials.
Australia’s dollar remains rangebound, despite constructive positioning. The RBA’s reluctance to commit to further tightening paired with mixed Chinese data has capped upside potential. Still, relative macro stability supports long-term accumulation on dips, especially versus the yen and pound.
New Zealand, on the other hand, is contending with an underwhelming fiscal path and weaker performance. The Treasury’s projection for a return to budget surplus by 2029 offers little near-term support for NZD, especially considering reserve manager (RM) selling pressure and a passive stance from the RBNZ.
A stronger-than-expected Canadian core inflation print has forced a sharp re-pricing of Bank of Canada expectations with rate cut odds for June collapsing from 70% to under 30%. The Loonie reacted sharply, with real money and systematic accounts driving USDCAD toward 1.3820. Our base case now aligns with a BoC hold in June, and we favour a neutral stance pending further inflation surprises.
Markets are currently starved for a unifying narrative and that absence is breeding volatility without direction. In such an environment, positioning becomes the compass. Until fiscal clarity emerges in the U.S., inflation softens more convincingly in the UK, or Asian central banks shift decisively, we expect ranges to dominate and patience to outperform prediction.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplies by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.

Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Brokers can offer LMAX perpetual futures alongside FX and CFDs through a single trading account. LMAX says brokers with existing credentials can go live in under five days.
24X National Exchange has filed a proposed rule change with the SEC to launch 24X Options, a general options market trading from 9:30 a.m. to 4:00 p.m. ET. The filing also covers binary KPI options on quarterly revenue, earnings per share and other metrics for 23 of the most actively traded U.S. companies.
cTrader Mobile 5.11 introduces Signals, a new app where traders can browse signals from leading providers and act on them directly in the platform.
ATFX Group has partnered with South Africa-based payment and digital asset infrastructure provider FiveWest to support institutional fund movements for ATFX Connect and add a cryptocurrency funding option for eligible retail clients. Both firms hold FSCA Over-the-Counter Derivative Provider licences.
UK inflation rose to 3.6% in October, keeping a December Bank of England rate rise likely, while the euro hit a fresh one-year low against the dollar ahead of tonight’s Fed minutes. Daily FX analysis from Equals.
GBPUSD has shifted decisively lower. After reaching 1.3228, the pair reversed and initially consolidated around the moving averages before breaking sharply below the 1.3180 area. It is now trading near 1.3169.
Nvidia shares jumped around 4% after hours after beating earnings and revenue expectations and raising its outlook for 75% year on year revenue growth through January 2028. The positive Nvidia results also lifted AI-related stocks, with CoreWeave up 8% and Nebius 10%.
Deutsche Börse Group has appointed Maximilian Weissenrieder as Head of Cash Market from 1 January 2027, succeeding Eric Leupold, who becomes CEO of Eurex. Weissenrieder has led Group M&A and Venture Investments since October 2024 and will retain those duties until a successor is named by the Group.
DEXA, the AI-powered risk management and analytics platform developed by TFB (Tools for Brokers), has connected with Match-Trader, bringing real-time trader analysis and toxic flow detection to brokers on the platform. DEXA classifies trader behaviour from as early as the third trade, with no change to execution systems.
Poland's financial markets regulator, the Polish Financial Supervision Authority (Komisja Nadzoru Finansowego, KNF), is preparing a new product intervention on contracts for difference (CFDs)