just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
More Hawkish Standpoint in Anticipation of 2024: Contrasting Market Sentiments
As we approach the end of the year, The Street is buzzing with the release of annual outlooks. I will release a comprehensive analysis but still a lot of work to be done so it will be published around early January, the time is ripe to juxtapose my 2024 Federal Reserve (Fed) outlook with the prevailing consensus and the market's implied policy trajectory. In essence, my stance is notably more hawkish than both, although I project 2-3 rate cuts commencing in the middle of the year, as I’ve mentioned on my webinar and my YouTube videos.
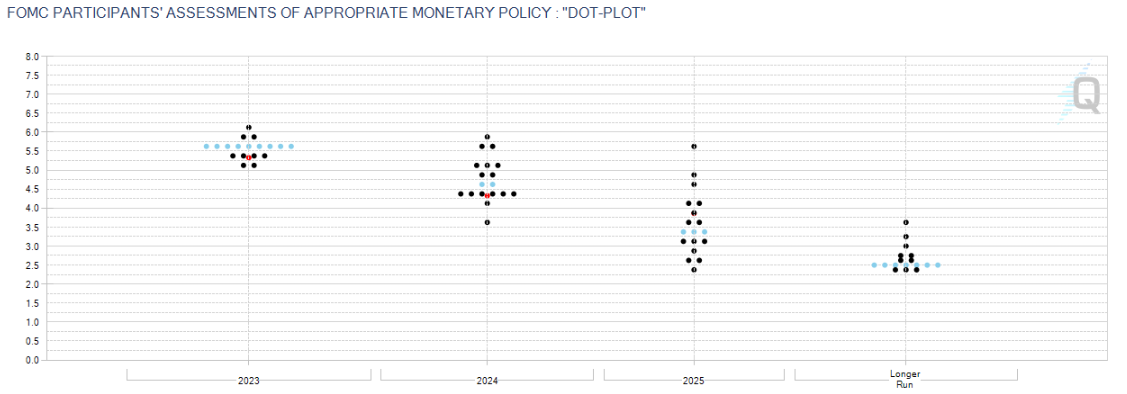
A detailed examination of the chart below unveils the market's anticipated federal-funds rate from now until December 2024. While the consensus aligns with my expectation of no further rate hikes, my forecast deviates as I foresee rate cuts initiating in May. The fed-funds futures curve I present suggests a trajectory with cuts almost every meeting, culminating in an implied funds rate of approximately 4.5% by year-end.
Dot Plot Chart
Source: CME
In contrast, economists surveyed by Bloomberg, not depicted in the chart, project an even lower policy rate of 4.45%. This implies nearly 100 basis points of cuts in the coming year, considering the current effective funds rate is at 5.33%. Additionally, the median dot for end-2024 from the Federal Open Market Committee's (FOMC) September Summary of Economic Projections stands at 5.1%. My viewpoint, anticipating the first rate cut in June or July with at most two additional cuts by year-end, positions the target federal-funds rate between 4.75% to 5%. This trajectory aligns somewhat with the September dots, depicting a less-dovish outlook.
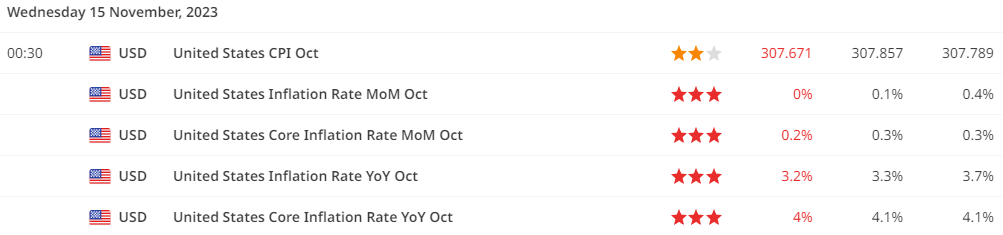
My rationale hinges on the belief that inflation will take most of the next year to approximate the Fed's 2% goal. My 2024 rate forecast assumes a slowdown in the U.S. economy, likely commencing as early as Q4 2023, as we could see already yesterday on the release of the CPI data.
US CPI
Source: Finlogix
This aligns with the Fed's perspective that tightening credit conditions and higher rates will impede economic growth. I anticipate inflation to be around 3% by midyear, and the subsequent cooling, combined with subpar growth, will prompt the Fed to moderate the current restrictive policy setting, albeit without excessive easing.
More dovish forecasts, in contrast, presuppose a more significant economic slowdown than I anticipate. Consensus forecasts project U.S. GDP growth below 1% for the first half of the year, concluding 2024 at 1.7%. The consensus also envisions U.S. core personal consumption expenditures (PCE) inflation below 3% by Q2 2024, settling at 2.5% by year-end. These figures, while not divergent from the Fed's September dots, suggest a more cautious stance.
The crux of the divergence lies in the interpretation of the Fed's reaction function. While consensus and market expectations posit a swift response to slowing growth and decelerating inflation, I maintain a contrary view. I perceive the dots as indicative of a Fed comfortable with a cooling growth scenario, even with a moderate decline in inflation, yet sustaining a relatively tight policy stance.
Shifting Focus to Federal Home Loan Bank (FHLB) Reforms: Implications and Criticisms
Proposed reforms to the Federal Home Loan Bank (FHLB) system are on the horizon, potentially restricting member banks' capacity to provide liquidity during banking system stress. Currently, FHLBs issue advances to commercial banks as a source of liquidity and funding. The suggested alterations favour tapping the discount window for short-term liquidity over relying on FHLB advances.
Examining the historical trends in FHLB advances and discount window usage since 2000 reveals interesting patterns. During periods of stress, FHLB liquidity provision overshadows discount window borrowing. Instances such as the Global Financial Crisis (GFC), the COVID lockdowns, and more recent regional banking stresses in March-April 2023 underscore the significance of FHLB liquidity. This preference may stem from the perceived stigma associated with discount window borrowing, as FHLB advances are less conspicuous and reported less frequently.
Furthermore, the years leading up to the pandemic witnessed a steady increase in FHLB usage, reaching over $500 billion by the end of 2018. Conversely, 2021 and 2022 saw diminished FHLB advances, attributed to the Federal Reserve's ample liquidity provision post-March 2020 lockdowns and the persistent zero-rate environment, facilitating readily available cheap bank funding.
While the proposed reforms remain pending with no definitive timeline, they face considerable criticism. One primary concern questions the readiness of banks to seek discount window financing in the absence of FHLB advances during a liquidity event. If banks are reluctant to turn to the window, the question arises: where will they source liquidity in times of stress?
This contemplation leads to the notion that, in periods of calm, banks might hoard liquidity as a precautionary measure, potentially raising the lowest comfortable level of reserves in the banking system and causing stress on both banks and the overall financial system.
Shifting Gears to Real Money Demand for US Treasuries: An Intricate Market Dynamics Exploration
Extensive discussions about real money demand for U.S. Treasuries have been a recurring theme, particularly emphasizing the positive demand from institutional investors for both bills and coupons. In the realm of bills, institutional investors exhibit a willingness to deplete their cash and short-term securities holdings in favour of higher returns in the bill market. This behaviour mirrors that of money market mutual funds, which, since the postponement of the debt ceiling in early June, have been redirecting their investments from the Federal Reserve's overnight reverse repo facility to T-bills.
Despite this positive trend, a noteworthy player in the domestic market, U.S. commercial banks, has been reducing its holdings of U.S. Treasuries and agency mortgage-backed securities (MBS) since last year. Official Fed statistics indicate a reduction of approximately $500 billion in these positions since February 2022. While total holdings have increased since the pandemic's onset, the ongoing reduction in UST and MBS holdings raises concerns.
The reduction in bank holdings is attributed to the surge in interest rates and mark-to-market losses on securities portfolios, exacerbated by leverage constraints such as the supplementary leverage ratio (SLR). Given my apprehensions about continued robust supply from the U.S. Treasury into 2024, the declining participation of price-inelastic buyers, such as commercial banks, raises concerns about whether price-sensitive buyers will be sufficient to smoothly absorb the forthcoming Treasury issuances.
In conclusion, the intricate interplay of economic forecasts, proposed financial reforms, and market dynamics creates a tapestry of uncertainties. As we navigate the complex landscape of monetary policy, liquidity provision, and Treasury markets, staying attuned to evolving trends and potential risks becomes imperative for informed decision-making in the ever-evolving financial landscape.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.

Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS Feed
just now
Sign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
UK retail sales rose a stronger-than-expected 0.7% in October, giving sterling some support, while a deepening tech sell-off pushed the dollar lower overnight against all major currencies. Thanim Islam, Head of FX Analysis at Equals, says the dollar remains in charge as the week ends, with the Fed expected to raise rates more than both the Bank of England and the ECB.
Nvidia beats expectations, reporting $115.8bn in revenue and raising its long-term growth outlook, but the stock still struggled to sustain its gains. AI remains fundamentally strong, but investor expectations are becoming more demanding, particularly around capex and profitability. Wall Street suffered a major sell-off, with the S&P 500 entering a six-session losing streak as rate concerns intensified.
iSAM Securities reviews the ris of weekend gold trading
Webull Corporation reported record third quarter 2026 revenue of $218.7 million, up 39% year-on-year, with customer assets reaching $32.4 billion and options contracts volume up 79%. Net income attributable to the company was $31.2 million, while margin debit balances passed $1 billion for the first time.
Anthropic, the company behind the Claude family of AI models, begins trading on the Nasdaq today under the ticker ANT. It priced its shares at $83 last night, above its marketed range of $70 to $78, and raised about $81.3 billion. That makes it the largest initial public offering on record, ahead of the roughly $75 billion SpaceX raised in June. This note covers what investors need to know: the terms, the business, how the company is governed, and what to watch.
Nvidia's first results without Jensen Huang answered the question that has hung over the AI trade since October. Revenue of $115.8 billion beat consensus by about $7 billion, fourth-quarter guidance of $130 billion came in roughly $5 billion above expectations, and the company raised its outlook for next fiscal year to around 75% growth. All of this assumes no data-centre sales to China.
Marex has entered the football financing market through a partnership with specialist sports investment and advisory firm Pinto Capital, targeting clubs in the Premier League and EFL Championship.
Around 110,000 UK retail investors have secured $300 million worth of Anthropic shares in its record-breaking $81 billion IPO. The heavily oversubscribed offer, coordinated by RetailBook, saw smaller investors prioritised, with 63% of applicants receiving their full allocation.
Clear Street has completed its acquisition of Boom Securities (H.K.) Limited, establishing its first licensed brokerage presence in Hong Kong
Sterling slips to its lowest against the dollar since October as markets trim Bank of England bets and Fed minutes point to further US rate rises, while the euro hits a fresh one-year low. Daily FX analysis from Equals.