
Search Companies, News, Members & more
Terms of ServicePrivacy PolicySecurity PolicyLegal InformationCommunity GuidelinesSitemapsCookie Settings
2026 Copyright © Liquidity Finder Ltd. All rights reserved.
Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
JP Morgan's JPMD - A Tokenised Deposit Cum Stablecoin
Published on Jul 19, 2025
Updated on Mar 7, 2026

JP Morgan has announced that it will be issuing a stablecoin-like token, called JPMD, on a public blockchain.
Importantly, the token is permissioned. So, yes, it is on the pubic blockchain, but holders are “by invitation only”. Upfront, the guest or whitelist is limited to JPM Institutional Clients only.
To date my take on tokenised deposits has been: “Not useful outside the four walls of the place that issued them”. Specifically, my view has been that using JPM Coin or Kinexys is like have an extra discrete account in a specific currency which works on new technology or rails.
JPMD adds mew dimensions. To quote Keynes: “When the facts change, I change my mind …” In this case, the facts have changed. In this post I’ll explain my thinking.
As with all things bleeding edge in financial services, there is every risk that I haven’t understood properly, or just missed a few salient points, or just come to an implausible conclusion. If any of things are true, please call me out on them.
Why is this an important topic?
Let’s start at the beginning. With a good old TradFi account at JPM, or any Nostro, when you want to make a payment you send the instruction to JPM. Funds are then moved as book transfers if the recipient / payee also has a JPM account or IRL via a payment system, such as the FedWire, CHIPS, CHAPS or T2. But there are limitations on timing; business days end in late afternoon, early evening and the batch nature of the systems mean nothing happens at the weekend.
JPM broke out of this “legacy systems albatross” with JPM Coin and Onyx, which is now Kinexys. The “train” is the same; an account and a payment, but the “rails” are different. New technology enabling 24 * 7 * 365 processing.
The change meant that JPM clients could send and receive funds from any other client using Kinexys at any time. This is useful if a meaningfully large or all-encompassing group of clients all bank with JPM. An example where this is the case is India, with local banks using JPM to settle dollar trades.
At this point, you will understand my saying: “Not useful outside the four walls of the place that issued them”.
Kinexys is also a path for JPM to payments system renewal. Instead of trying to adapt, upgrade and fix the old rails, JPM have taken a really sensible path here. Trying to have a big bang, with the one stopping and the other starting, could be done, but requires huge planning. Allowing things to exist in parallel, whilst minimising investment in the old, legacy systems, reduces the operational risks involved. One of co-existence. There is a parallel from TradFi; bank branches with counter service vs. ATMs. Only some 50 years after the first ATMs were introduced did banks begin to push through widespread closure of their counter services.
What’s new or changing?
Quite often, people I interact with talk about public blockchains and private permissioned chains. Two discrete things. For reasons which are easy to imagine; KYC, transaction monitoring, sanctions screening, in other words all the regulatory must do stuff, which regulated financial institutions have to do. There is though a hybrid or in-between flavour: public permissioned.
This is an important concept. The token circulates on the public blockchain but only amongst approved users. A private members’ club. In the case of JPMD, the membership is limited to JPM’s institutional clients.
Using the public blockchain opens up interoperability, programmability and composability. The holy trinity of digital asset capabilities. Here’s my thinking of what this means in practical terms.
Today, an institutional client wanting to trade digital assets will often be required to pre-fund cash with whichever marketplace or broker it is using. In the TradFi world, if the client uses JPM and the marketplace uses Citi, then money has to move IRL and that can be slow. In technical terms, this type of set-up has credit risk and liquidity risk, as well as making liquidity management harder than it might be.
That works a bit better if both client and marketplace have a TradFi fiat Nostro with the same bank. Not really a scalable solution for the marketplace. And limited by all those TradFi opening hours and cut-off times.
Things work a bit better if you use Kinexys; the opening hour restrictions largely go away. But, there is the same limitation for the marketplace. And, as the client you still need to pre-fund the marketplace aka venue aka exchange.
Once the client accounts are on a public-permissioned blockchain, all parties can take advantage of that holy trinity of digital assets. Back to that institutional client wanting to trade. Once it has some JPMD on a public chain, it could send a buy order to a marketplace, which in turn would use interoperability to earmark enough JPMD to cover the order and then try to execute. If the order is not filled, a quick kill instruction would lift the earmark, and the client can try its luck at another venue. Now exactly the same thing could be done with USDC or USDT; JPM is offering optionality. Programmability might be used for an escrow arrangement; when an order is placed, it enables funds to be earmarked, and then later transferred when pre-agreed conditions are met.
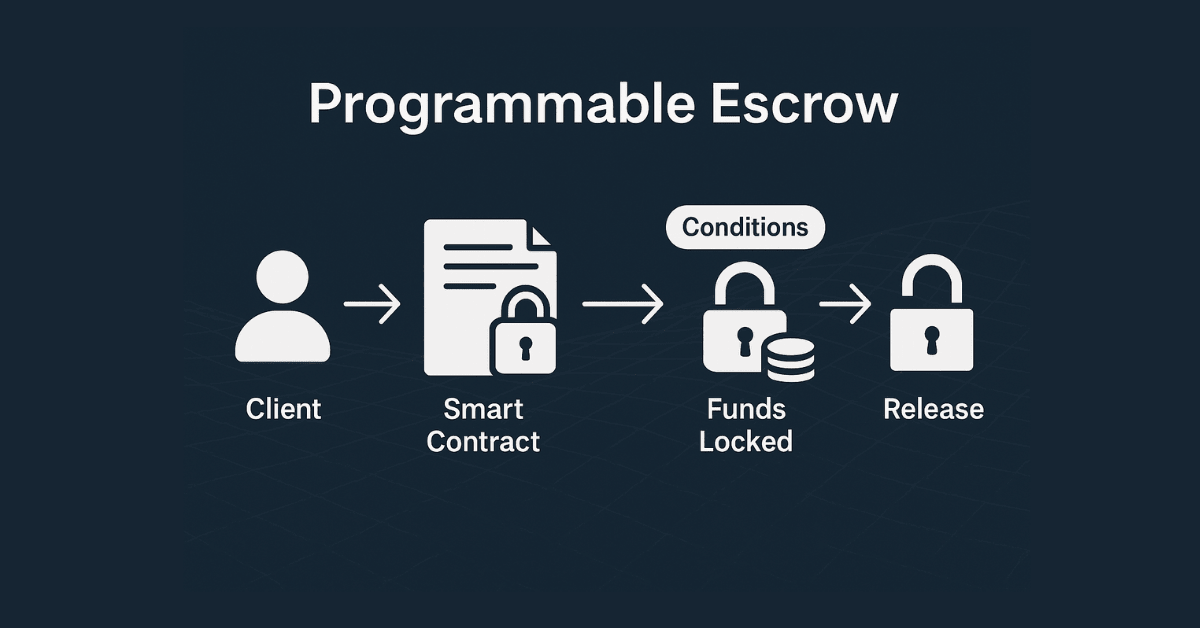
In technical terms, there is still credit risk, but vis a vis JPM rather than one or more marketplaces. There is no liquidity risk; one pool of liquidity serving the marketplaces and settlement needs which have accounts at JPM. There is still some liquidity management to be done, balancing fiat needs and tokenised deposit needs, but life is easier. In the long run, the fiat part will become smaller and smaller.
In terms of accounting and reporting, I don’t think there is any change here; today in fiat, or even Kinexys, JPM keeps track of client balances. With the advent of JPMD, JPM will still be accountable for things AML / CFT. That will force them to monitor the follows of their JPMD token between wallets. This is the same range of work as if they process a TradFi book-transfer between two JPM clients.
So clients have the ability to use the full range of new services on the public blockchain as long those they want to interact with also use JPM.
Now, somethings do not change. The issued JPMD is still a liability in JPM’s books and still has to be reflected in the liquidity calculations: LCR, NSFR.
In conclusion
JPM has done our industry a service with this step. Public permissioned is an important step.
I need to update my take on tokenised deposits:
Old: “Not useful outside the four walls of the place that issued them”.
New: “Useful inside the four walls of the issue or the private members’ only gardens controlled by the issuer”.
There is hope for even more useful developments. In times past, I have spent many hours in the world of securities settlement, dividends and withholding tax reclaims. These are elongated, paper-based processes. In my days at Goldman Sachs in Zurich, we had to collect all the confirmations of net dividends received and withholding tax deducted, then fill out forms, then submit these to HMRC in the UK for a stamp that entitled Goldman Sachs Intl to reclaim 20 of the withheld 35% under the double tax treaty, and then submit the stamped forms to the Swiss Federal tax folk. Potentially that could be much simpler: HMRC issues Goldman Sachs International a token on a public chain validating their right to that refund. The Swiss tax folk can see the position, the gross dividend paid, and the HMRC token all in the same wallet. A smart contract can execute the repayment of 35% of the withholding to token-holding wallets without any manual review or effort. Outside the upfront smart contract work, there is no on-going admin. Governments could reduce headcount. Could - but whether they will or not is an entirely different matter.
Things JPMD all work really well as long as all those who want to play are JPM clients. Rather like Google with search, and to some extent Apple with the App Store, JPM is building an ecosystem which could give it monopoly power in the long-run. I am an Operations guy who has spent his career settling trades and making payments. The main ingredient has been the use of financial market infrastructure (FMIs) to do that. The idea that we would all have to use JPM does not sit well.
My thanks to Mike Manning and Dani Heller for reviewing the draft and making some useful edits and observations.
Thanks for reading. Please do let me know what you think of these notes. Feedback via the comments would be great.
Author
 |
Olaf Ransome is a liquidity and financial services expert. He is the founder of 3C Advisory You can message Olaf directly here. |
Share this article
Comments
Most Recent
Find The Right Partners for
Your Trading Business
Sign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
BitMart announced on July 26, 2026 that it is winding down its trading platform: new registrations and deposits stopped immediately, spot and futures trading ends August 26, 2026, and operations fully close by January 31, 2027. Anyone still holding funds on BitMart needs a reliable replacement exchange immediately.
A new stablecoin backed by 140+ firms, from Visa to BlackRock. Can Open USD challenge USDT and USDC, and will it clear MiCA? Olaf Ransome weighs in.
SoFi's SoFiUSD is the first stablecoin issued by a US national bank. But do holders actually have the protection they think?
Brent Xu left Wall Street for blockchain in Ethereum's earliest days. Now his Franklin Templeton and Galaxy Digital backed platform Dora is bringing fractionalised bond trading to retail brokers. He speaks to Sam Low.

Discover whether KuCoin is still “The People’s Exchange” in 2026. This in-depth KuCoin review breaks down fees, KYC, security, Proof of Reserves, supported coins, deposits/withdrawals, futures, margin, Earn and the platform’s standout free trading bots — plus who it’s best for (and who should avoid it).
Gas fees can be the most confusing part of using Ethereum and other blockchains. This guide explains what gas fees are, why they exist, how costs are calculated (including EIP-1559’s base fee and priority tip), and the key factors that drive price spikes. You’ll also learn practical ways to reduce fees using gas trackers, smarter timing, batching, and Layer 2 networks like Arbitrum, Optimism, Polygon and zkSync.
Generating and sustaining liquidity requires a strategic approach across centralized exchanges, decentralized pools, and market-making relationships. This guide covers every stage of the process for crypto projects.
This guide covers how proof-of-stake works, the best assets to stake, liquid staking protocols, and the risks you need to understand before committing funds.
Create Your FREE Account
Get access to latest news, updates, real-time data, brokerage and trading firm insights and customized information feeds.


CME Group will launch baseball futures on 12 October, pending regulatory review, tracking CME FutureSports Performance Indexes built on Official League Data. Standard and micro contracts will start with the 2026 Postseason and the four clubs in the League Championship Series, trading around the clock.

ESMA has published an opinion stating that MiCA-authorised crypto-asset service providers should cease services tied to non-MiCA-compliant stablecoins for EU clients across MiCA crypto-asset services. National authorities should require remediation of existing exposures within three months, by early January 2027.

Nasdaq Ventures has made a strategic investment in Amsterdam-based derivatives and crypto exchange One Trading, with both firms to explore 24/7 trading of equity futures. The undisclosed investment follows Nasdaq's US$100 million investment in Payward, the parent of Kraken, and CME Group's move to 24/7 trading.

cTrader has opened multi-platform plugins to brokers and prop firms, which can pre-install their own tools for clients or list them in cTrader Store. The plugins run across Mobile, Web, Windows and Mac, and can be built and launched independently of core-platform releases, including trading journals and calculators.

Institutional brokerage and financial infrastructure provider Clear Street has joined TradingView’s broker network, allowing its clients to trade US stocks, exchange-traded funds and options directly through the charting and analysis platform.


Learn how to improve trading psychology, manage fear and greed, avoid revenge trading, and follow your trading strategy with discipline and a trading journal.

GTC Prime has announced a strategic partnership with Centroid Solutions to manage and distribute its liquidity through CS 360 Bridge, Centroid's multi-asset connectivity and execution engine, giving brokers and institutional clients access to tailor-made pricing, low-latency execution and real-time risk management.

CMC Markets Founder and CEO, Lord Peter Cruddas, discusses the structural evolution of the Group, the accelerating opportunity across B2B and institutional markets, major global partnerships including Revolut, Westpac, and ASB, and his outlook for the remainder of the financial year ahead.
Clear Street has announced an exclusive partnership with Seawolf Capital to bring market commentary from Danny Moses, Vincent Daniel and Porter Collins to its clients and the wider investing community, including live market calls, digital content and events. New programming will sit alongside Seawolf's podcast.
Yields are surging. But is inflation really the reason? This week’s BitDelta Pro Weekly Outlook looks beyond the headline explanation to examine what is actually driving the move in rates, and what that could mean across equities, credit and commodities. We also explore the growing importance of balance-sheet quality, the signals emerging from the AI infrastructure cycle, and what oil and gold may be telling markets about the current macro regime. Read the full Weekly Outlook. BitDelta Securities Financial Services LLC, regulated by the Capital Market Authority under Category 5 (Introduction Only), acts solely as an introducer and does not provide trading, execution, dealing, advisory, portfolio management, or custody services. All trading, execution, and investment-related services are provided by BitDelta Limited, Mauritius, a licensed Investment Dealer. All trading and investments involve risk. The value of investments may fluctuate, and you may receive less than your initial investment.
Feed