
Search Companies, News, Members & more
Terms of ServicePrivacy PolicySecurity PolicyLegal InformationCommunity GuidelinesSitemapsCookie Settings
2026 Copyright © Liquidity Finder Ltd. All rights reserved.
Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Tokenised Deposits: good, bad or ugly? - Olaf Ransome
Published on Jun 19, 2024
Updated on Mar 7, 2026

These things are all the rage, so it is worth spending a little time to understand what they are, how they work and what the implications are for your business. If you are in treasury or transaction banking, or trading, I’d offer the view that having some insight and a view on this is essential.
I tend to have strong views which are loosely held; when the facts change, I change my view. Last week at Future of Finance’s “Digital Money” event, I had the chance to talk about this; I learned something and adjusted my views.
Today, any retail or corporate client will have a cash balance in an account with its bank. In very simple terms, the typical TradFi or legacy tech in most banks is a one-trick pony. It simply allows a client to send in a simple instruction of “Pay X to Y’s account at Bank Z on Day T”. Yes, we have many ways to send those instructions; web login, app, SWIFT, but the payment is quite a simple instruction.
Tokenisation is about the use of new technology to represent our assets; they might be securities, real-world assets or money. Along with that comes a desire to have a means of payment which is “always on”. i.e. 24 * 7 * 365, “programmable”, and interoperable.
The promise of tokenised deposits is that programmability means we can “orchestrate” payments. IFTTT, if this then that, is a well-known explanation of these things. Last week, somebody told me about when you do all the paperwork to buy a house in the UK, there might be as many as 16 parties involved. If you have a programmable payments infrastructure, then many good things can happen.
Whilst there are lots of banks looking at tokenising deposits, JP Morgan with its Onyx product has been among the pioneers. They happen to have used Blockchain technology to create new internal payment rails. Until now, this has been useful for making payments between any two JPM clients and it can be combined with existing legacy payments capabilities to pay to a counterpart using another bank. Quite useful, but not nirvana.
Should I do anything about tokenised deposits?
If you are a JPM Client, whether you come from an FI, an NBFI, or a corporate, you should be talking to your JPM representative. What’s in it for me (WIFM)? Come to a view on whether you can and should use the new infrastructure.
If you are a client of another bank, then for all your major currencies, tokenised deposits should be a topic for you next relationship meeting. The same WIFM question.
Be curious.
What else do I need to know?
Particularly if you are the Treasurer, you should have an eye on what the rest of the bank is up to, because there are ways that this new world of tokenised deposits may play out, which will make us all less rather than more efficient.
I have said many times that a tokenised deposit is only useful inside the four walls of the institutiin which issued it. In other words, payor and payee both have to bank at the same place. New tech it might be, but with new tech like JP Morgan’s Onyx, any payment is made by a good old-fashioned in-house book transfer.
Last week, Ownera’s Anthony Woolley challenged my thinking and made the case that through inter-operability, tokenised deposits could be used for payments between two parties who bank with two different banks.
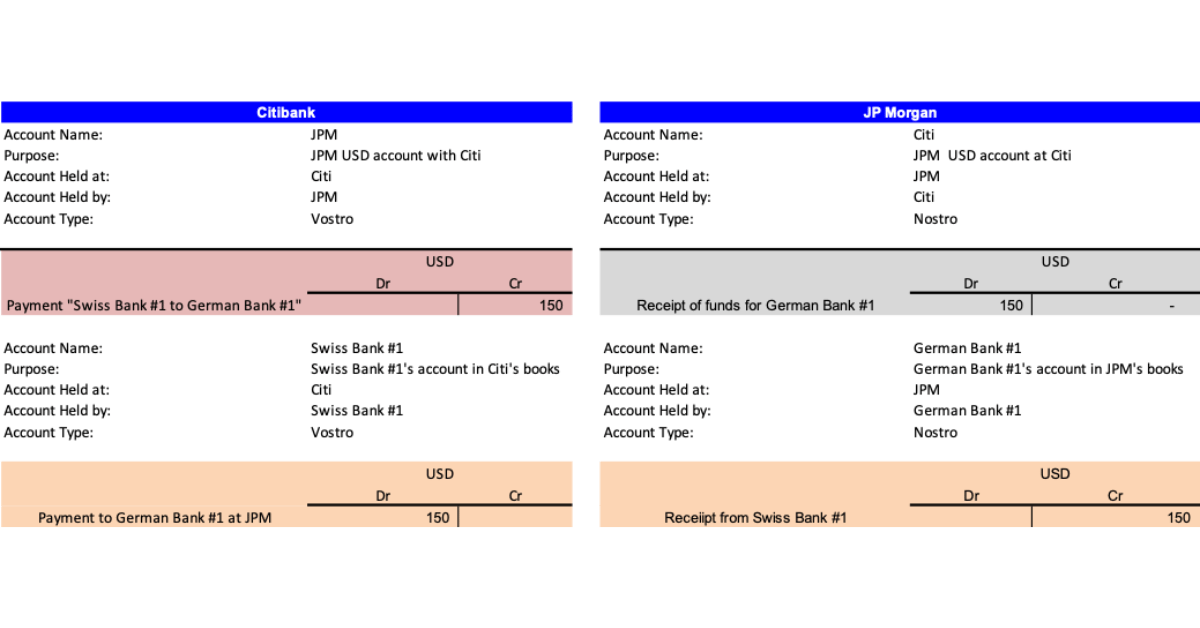
I worked through the accounting, cf. Figure 1. In my example Swiss Bank #1 has Citi as its Nostro. It wants to make a payment of USD 150 to German Bank #1, which uses JPM as its USD Nostro.
Technically, Anthony is right. The foundation of such an arrangement would be that each bank has to have an account in the other bank’s books; tokenised or not. Settlement is then by book transfer. In my time at Credit Suisse, this method was used with UBS; each bank had a USD and a gold acount in the other’s books.
So, it can be done. Would it be a good thing if many banks have their own unique tokenised deposits and there is interoperability between them? My Bankers’ Plumber view is: “not really, and anything inter-bank would be a step backward rather than forward.” Here’s why:
The arrangements would be fine for payor and payee. The payor sees a debit and the payee sees the credit. Broadly, German Bank #1 is indifferent as to where JPM has its USD balances. Tokenisation does not change that. If the tech stack is “new & improved” that is entirely separate.
As soon as we introduce interoperability to the mix here, as Anthony suggested, I think a number of dimensions are involved around things we don’t really want.
Firstly, there are some implications for the two banks.
- Counterparty risk: JPM has an unsecured receivable vs. Citi. It consumes a small sliver of credit risk appettite that a normal, old-fashioned FedWire payment would not. It adds complexity to keep track of that exposure; does JPM allocate a fixed piece of its credit appetite for Citi to that business, or try to manage intra-day?
- Liquidity Fragmentation: JPM now has another bucket of money to manage. Firsty, more buckets = more work, more operational risk and less efficiency of liquidity management. Secondly, the balance at Citi is in a discrete system; JPM will have to choose to have Citi make a payment on the FedWire in order to get those funds back to their main USD account, which would be at the Fed.
- Commercial vs. central bank money: The use of central bank money for payments and settlements is the preferred approach (cf: Principles for financial market infrastructures – PFMI, Principle 9). Settlement in commercial bank money is widespread today; as soon as payor and payee are at the same bank, it happens. But it generally doesn’t happen for inter-bank settlements; in any payment system, the major banks pay each other via an FMI in central bank money. Changing that mix is theoretically possible, but not really a good thing, because it creates credit-based dependencies.
For the client banks, Swiss Bank #1 and German Bank #2, the benefits are mixed at best. Good: tokenised deposits allow for programming and use cases which today’s legacy tech stack does not. Bad: the system still relies on the use of intra-day credit. If Citibank makes the payment by allowing Swiss Bank #1 to be overdrawn, then both parties’ intra-day liquidity buffers are impacted.
Figure 1: Accounting Entries with bi-lateral Nostro arrangements
 My conclusion for the Treasury fraternity; keep a very close eye on your business and product people. Steer them away from “new solutions” which increase the number of accounts you hold.
I have heard it said of advertising that “it is not necessarily a good thing or bad thing; it depends on the use to which it is put.”
Thanks for reading. Please do let me know what you think of these notes. Feedback via the comments would be great.
Please feel free to get in contact via LiquidityFinder here
My thanks: to Dominic Hobson and Wendy Gallagher at Future of Finance for having me on the panel last week, to Keith Bear for being a great host, to Anthony Woolley for challenging me, as welll as to my fellow panelists: Emma Landriault, ShearinCao, Roberto Pagliari, John O’Neil and Marcy Dumitrescu.
 |
Olaf is a liquidity and financial services expert. He is the founder of 3C Advisory You can message Olaf directly here. |
Share this article
Comments
Most Recent
Find The Right Partners for
Your Trading Business
Sign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Scope Prime's Andrew Taylor sets out how brokers serving Asian clients should measure and price sharp gold flow, citing the October 2025 and January 2026 sell-offs, thin liquidity at the Asian open, segmentation over relationship-wide repricing and the questions to ask a prime of prime provider.
Scope Prime's Andrew Taylor sets out how brokers serving Asian clients should measure and price sharp gold flow, citing the October 2025 and January 2026 sell-offs, thin liquidity at the Asian open, segmentation over relationship-wide repricing and the questions to ask a prime of prime provider.
GCC Brokers is a Dubai-based A-Book STP broker with FSC Mauritius and UAE SCA regulation, raw spreads from 0.0 pips, and an LBMA gold fix service. Here is an honest assessment of who it suits and who it does not.
Dark pool trading was once the preserve of institutional desks, but a new wave of AI tools is promising self-directed investors a look into non-displayed liquidity and where the big money sits. This article explains what dark pools actually are, why retail traders face an even bigger information gap in FX than in equities, and what AI-driven intelligence platforms like IUX24 can and cannot reveal about institutional positioning.
SoFi's SoFiUSD is the first stablecoin issued by a US national bank. But do holders actually have the protection they think?
LSEG's DiSH promises atomic settlement and 24/7 PvP and DvP capability using tokenised commercial bank deposits. But when the balances move and the banks don't, who actually owns what? Olaf Ransome examines the mechanics - and the risks.
Klarna is partnering with Coinbase, raising stablecoin-denominated funding and launching KlarnaUSD. We break down the treasury logic, merchant incentives and agentic AI payments angle — and what other CFOs should take from it.

Olaf Ransome’s latest article on liquidity management explores PORTS (Perpetual Overnight Rate Treasury Securities) and how they could expand the supply of on-chain high-quality liquid assets (HQLA) for treasury and cash management. He explains why long cash balances create risk, how stablecoins and tokenised money market funds need safe short-duration assets, and what PORTS could mean for reverse repo, liquidity management and wholesale banking.
Create Your FREE Account
Get access to latest news, updates, real-time data, brokerage and trading firm insights and customized information feeds.


Clear Street has completed its acquisition of Boom Securities (H.K.) Limited, establishing its first licensed brokerage presence in Hong Kong


Sterling slips to its lowest against the dollar since October as markets trim Bank of England bets and Fed minutes point to further US rate rises, while the euro hits a fresh one-year low. Daily FX analysis from Equals.

JT Prime, the institutional Prime of Prime founded by Raj Sitlani, Jonathan Brewer and Jeff Wilkins, is set to become the new home for institutional client relationships currently serviced by FXCM Pro. Clients have been offered the same leverage, fees and connectivity, ensuring continuity of trading conditions.


The Nasdaq 100 has shifted into a short-term bullish recovery after finding strong support around 26,611. Following the sharp sell-off, price has formed a sequence of higher lows and has moved back above the 20-hour moving average at around 27,270, while the 5-hour and 10-hour averages are also turning higher.

U.S. equity futures rose in the after hours, led by Nasdaq-100 futures up 1% and S&P 500 futures up 0.6%, as investors focused on Anthropic’s Nasdaq debut. The AI company priced its IPO at $83 per share, above expectations, and expanded the offering to raise around $81.3 billion, making it the largest IPO on record.

Brokers can offer LMAX perpetual futures alongside FX and CFDs through a single trading account. LMAX says brokers with existing credentials can go live in under five days.

24X National Exchange has filed a proposed rule change with the SEC to launch 24X Options, a general options market trading from 9:30 a.m. to 4:00 p.m. ET. The filing also covers binary KPI options on quarterly revenue, earnings per share and other metrics for 23 of the most actively traded U.S. companies.


cTrader Mobile 5.11 introduces Signals, a new app where traders can browse signals from leading providers and act on them directly in the platform.

ATFX Group has partnered with South Africa-based payment and digital asset infrastructure provider FiveWest to support institutional fund movements for ATFX Connect and add a cryptocurrency funding option for eligible retail clients. Both firms hold FSCA Over-the-Counter Derivative Provider licences.

UK inflation rose to 3.6% in October, keeping a December Bank of England rate rise likely, while the euro hit a fresh one-year low against the dollar ahead of tonight’s Fed minutes. Daily FX analysis from Equals.
Feed