just now
Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
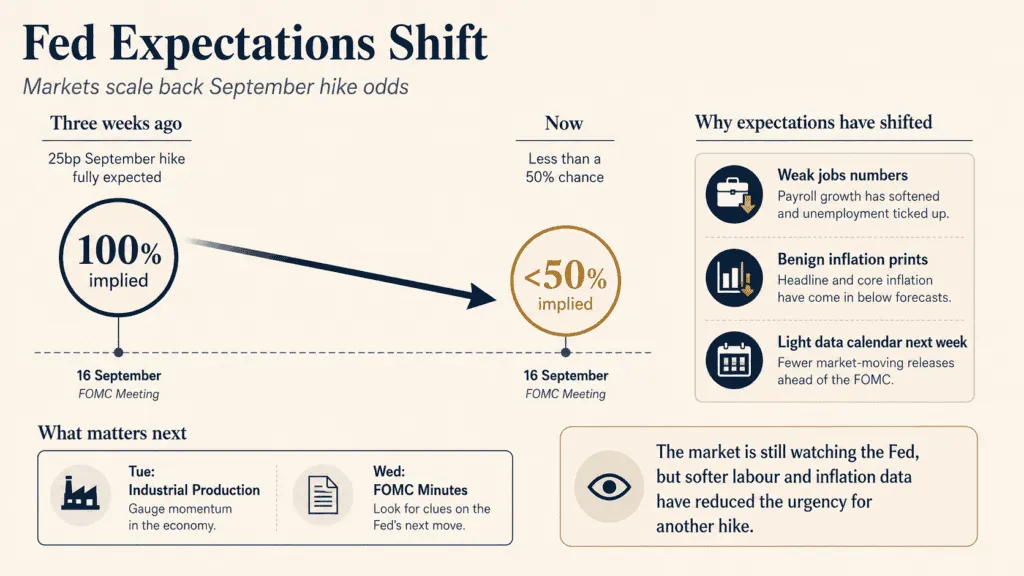
Markets head into the new week with an interesting macro backdrop: risk appetite remains strong and economic activity is holding up, but the pressure for the Federal Reserve to raise interest rates has eased considerably.
The US economy is sending two different messages. On the activity side, the picture remains constructive. July's ISM Manufacturing PMI rose to 55.6, its highest reading since May 2022. More importantly, the forward-looking components remained strong. New Orders increased to 56.7, Production jumped to 58.5 and Backlog of Orders climbed to 55.0. The services economy is telling a similar story, with July's Services PMI at 54.1, New Orders at 57.2 and Business Activity at 59.1.
That normally points towards an economy maintaining positive momentum.
The complication comes from the labour market. July non-farm payrolls fell by 23,000, while May and June were revised down by a combined 103,000. The unemployment rate remained relatively low at 4.1%, but labour-force participation has fallen 0.7 percentage points since January. In other words, the headline unemployment rate may be understating some of the underlying weakness in employment.
Inflation has meanwhile been less threatening at the consumer level. July CPI rose just 0.1% month-on-month, while core CPI increased 0.2%. Headline inflation eased from 3.5% to 3.4% year-on-year, while core inflation slowed from 2.6% to 2.5%.
There is still an inflationary warning underneath the surface, however. Producer prices were unchanged overall in July, helped by falling energy prices, but the measure excluding food, energy and trade services increased 0.4% month-on-month and 4.7% year-on-year. ISM price indicators also remain elevated. This suggests businesses are still facing cost pressure even while consumer inflation has moderated.
The result is a somewhat unusual but broadly supportive market regime:
Growth remains expansionary, risk appetite remains positive, but weaker employment and softer consumer inflation have reduced the urgency for further Fed tightening.
For equities, this resembles a risk-on reflationary environment rather than outright Goldilocks. Demand and business activity remain healthy enough to support earnings, while the threat from monetary tightening has eased. The risk is that persistent producer and input-cost inflation eventually makes its way back into consumer prices.
That tension will remain important heading towards the Fed's 16 September meeting.
The US calendar is relatively light next week, making Tuesday's industrial production report and Wednesday's FOMC minutes the main events.
Tuesday – Industrial Production
Industrial production will provide a useful test of whether the strength seen in recent manufacturing surveys is beginning to appear in the hard economic data.
The July ISM report provides a constructive lead. Production surged to 58.5, New Orders remained comfortably in expansion and manufacturing employment moved above 50 for the first time in almost three years. That creates a reasonable argument for stronger industrial activity.
Expectations are for industrial production to increase by around 0.3% month-on-month. There is potentially room for something stronger given the ISM data, although weaker hours worked in manufacturing provides a reason for some caution.
The Federal Reserve confirms that July industrial production and capacity utilisation will be released on Tuesday, 18 August.
For markets, the interesting question is not simply whether production beats or misses. It is whether the report strengthens the current combination of solid growth without enough inflation pressure to force the Fed's hand.
Wednesday – FOMC Minutes
The minutes from the Fed's 28–29 July meeting will probably attract greater attention.
The Fed left rates unchanged at 3.50–3.75% at that meeting, although the decision produced three dissenters who preferred an immediate 25bp increase.
Chairman Kevin Warsh's post-meeting communication left markets with plenty to debate over how close the broader committee is to another rate increase. The June projections had already shown policymakers evenly divided, with nine officials expecting a hike this year and nine expecting no increase.
Since then, weak employment data and relatively benign CPI readings have weakened the immediate case for tightening.
The minutes therefore matter because they should give markets a better sense of how broad the hawkish camp really is, and what evidence would be required to move undecided members towards a September hike.
The minutes will be released on Wednesday, 19 August at 2pm ET.
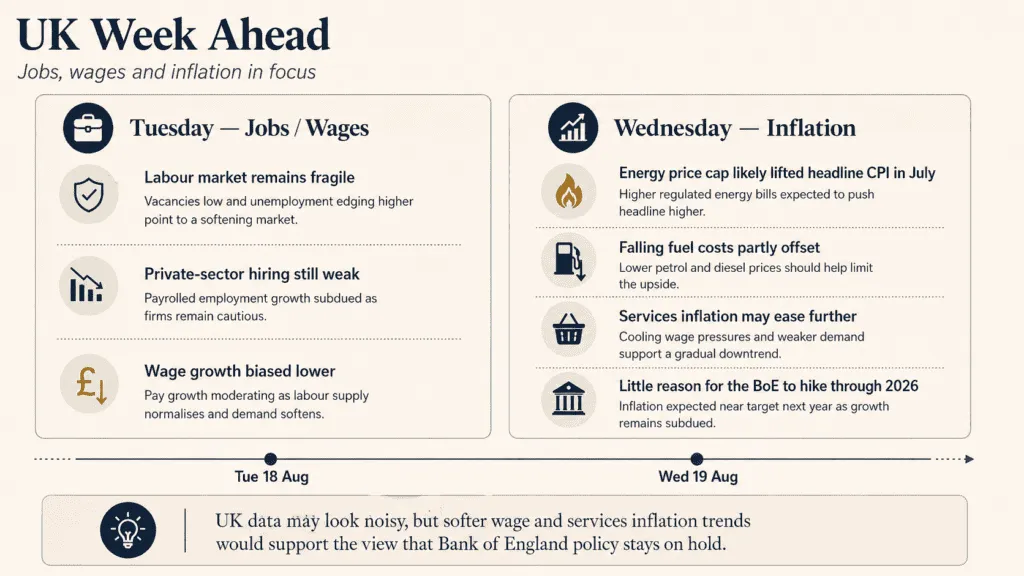
The UK has a busier week, with the labour-market report on Tuesday followed by July inflation on Wednesday.
Tuesday – Jobs and Wages
The labour market remains one of the weaker parts of the UK economic picture.
The latest unemployment rate stood at 4.9%, while payroll data have shown employment falling compared with a year earlier.
The focus next week will therefore be on whether hiring continues to soften and whether private-sector wage growth is losing momentum.
That wage component is particularly important for the Bank of England. Further moderation would make it harder to argue that domestic inflation pressure requires tighter monetary policy, even if headline inflation temporarily moves higher because of energy.
The next UK labour-market report is confirmed for Tuesday, 18 August.
Wednesday – UK Inflation
Wednesday's inflation report could produce an uncomfortable-looking headline.
UK CPI stood at 2.6% year-on-year in June, but July's increase in the household energy price cap is expected to push headline inflation back towards 3%. Falling petrol and diesel prices should partly offset that increase.
The more important number for the Bank of England may again be services inflation.
If headline CPI rises mainly because of regulated energy prices while services and wage inflation continue to cool, the message for monetary policy is much less hawkish than the headline number alone would suggest.
The July CPI release is confirmed for Wednesday, 19 August at 7:00am UK time.
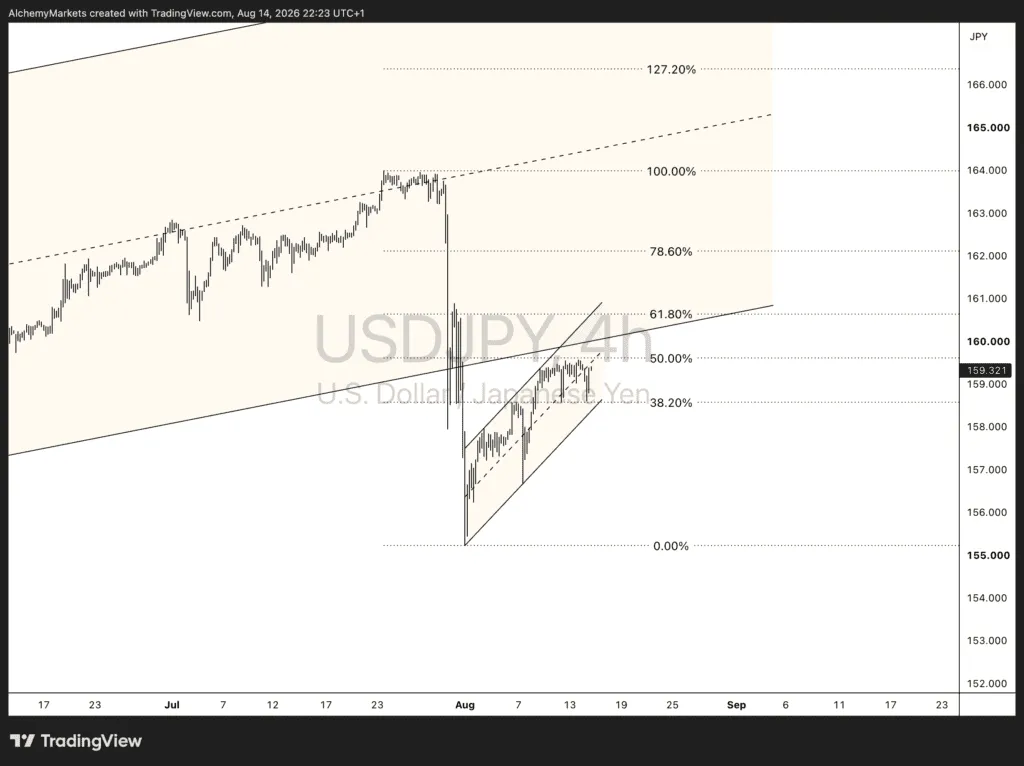
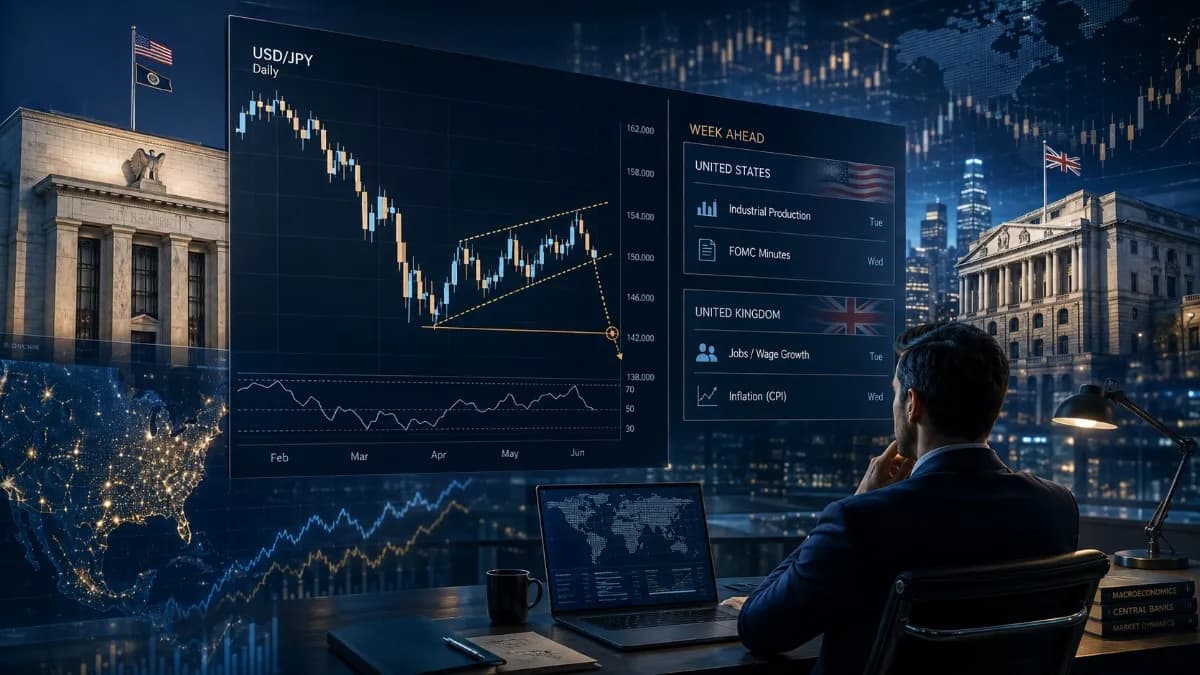
USD/JPY remains our chart to watch heading into the new week.
The pair suffered a sharp decline from the 164.00 region towards 155.00, before entering a corrective recovery. That rebound has now retraced roughly 50% of the initial decline, taking price back towards the 159.50 area.
The structure currently resembles a bear flag, with price consolidating higher following the initial impulsive sell-off.
Importantly, a 50% retracement may already be enough to complete that correction.
The next confirmation would therefore come from a break below the lower boundary of the flag. Such a move would suggest the recovery has run its course and bring the 38.2% retracement area around 158.20 back into focus initially.
Below there, attention would turn towards the August low around 155.00–155.20.
The bearish setup remains conditional rather than confirmed. As long as USD/JPY remains inside the rising corrective structure, the recovery can extend towards the 61.8% retracement around 160.70.
But if the flag gives way, the technical picture would favour another leg lower in USD/JPY, with the 50% retracement potentially marking the end of the counter-trend recovery.
Alchemy Markets is a multi-asset brokerage providing retail traders with the same elite trading conditions, tools, and transparency typically reserved for institutions.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Gold reached the $3,880 bearish target. Review the weekly analysis, $4,000 support zone and original break-and-retest sell checklist.
VS Markets Ltd has been authorised by CySEC to provide crypto-asset services under MiCA, covering custody, exchange, order execution, reception and transmission, and transfers. Services launch in the coming weeks for retail and institutional clients across 29 EEA markets, alongside its CFD and shares offering.
Learn how to set up a day tradeusing price action with five simple steps covering market direction, key levels, entry confirmation, stop loss, and take profit.
Learn price action trading step by step, with beginner and advanced techniques covering market structure, key levels, entry confirmation, and risk management.
Gold price forecast: Will XAUUSD break $4,250 or lose $4,000 support? Explore bullish and bearish setups, with potential targets at $4,375 and $3,880.
smartTrade Technologies SAS has acquired Celoxica, a provider of ultra-low latency execution infrastructure for listed markets across 80+ venues worldwide. The deal extends the smartTrade Group’s reach from OTC to listed markets, and Celoxica General Manager Jean-Marc Bouhelier joins the smartTrade Executive Committee.
The collaboration adds outsourced dealing, real-time risk intelligence and trading-flow surveillance to STARPRIME's institutional liquidity offering.
MAS Markets has appointed Gareth Palmer as eFX Sales, bringing more than 20 years of financial services experience to develop the FCA-regulated liquidity provider’s electronic FX sales capabilities, strengthen institutional client relationships and expand its electronic trading offering across global markets.
Usio has reported third quarter 2026 revenue of $23.8 million, up 12%, with Adjusted EBITDA up 222% to $1.2 million, total payment dollars processed up 25% to $2.73 billion and a sixth consecutive quarterly record in ACH transactions, and has reiterated its guidance of 14% to 16% revenue growth for 2026.
Macquarie Bank has admitted failures in how it promoted its Welcome Rate offer for new savings account customers, with ASIC and Macquarie jointly proposing a $14 million penalty to the NSW Supreme Court, on top of $8.8 million in remediation that Macquarie has already paid to nearly 40,000 customers.