just now


Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
For three months, one chokepoint in the Persian Gulf wrote the macro narrative for everyone. The Strait of Hormuz did the work that data usually does — it set the inflation path, it set the dollar's tone, it set the risk mood. Brent ripped from the low-$60s to north of $110 at the peak, and every central bank on earth suddenly had the same problem handed to them by the same map.
That chapter is now closing. Over the weekend, reports landed that Washington and Tehran have agreed the "final" text of a peace deal, the clearest signal yet that the supply shock has an expiry date. Oil eased, equities caught a bid, and for the first time since February the tape is being allowed to trade on something other than a missile headline.
Here's the catch, and it's the whole point of next week: de-escalation doesn't hand you back the old world. It hands you a world where the inflation that the war injected is still sitting in the system — in fuel, in shipping, in the lag before household energy bills reset — while the catalyst that caused it fades from the front pages. That's the awkward gap central banks have to navigate, and it's why a single week containing the Fed, UK CPI, UK jobs and the Bank of England is going to matter far more than the calm price action suggests.
And they are emphatically not aligned. The consensus that normally binds the major central banks has fractured along the fault line the oil shock opened. Some are leaning hawkish into the inflation overshoot; others are insisting the next move is still, eventually, a cut. Next week is where those diverging reaction functions get tested against live data — and where the dollar, gilts and crude all have to pick a side.
The non-obvious read: the war was the easy part to trade. The peace is harder. A fading premium pulls oil lower even as the inflation it left behind keeps the hawks talking — and that tension is exactly what the price action is starting to whisper before the calendar confirms it.
(All times BST / GMT+1. Consensus figures indicative and subject to revision into the events.)
Wednesday 17 June
Thursday 18 June
Lower-tier, worth a glance:
The thread tying it together: every one of these prints feeds the same question — with the war premium draining out of oil, does the inflation it created stay sticky enough to keep the hawks in control? The Fed's dots and the BoE's vote count are two different committees answering that exact question in the same 18 hours.
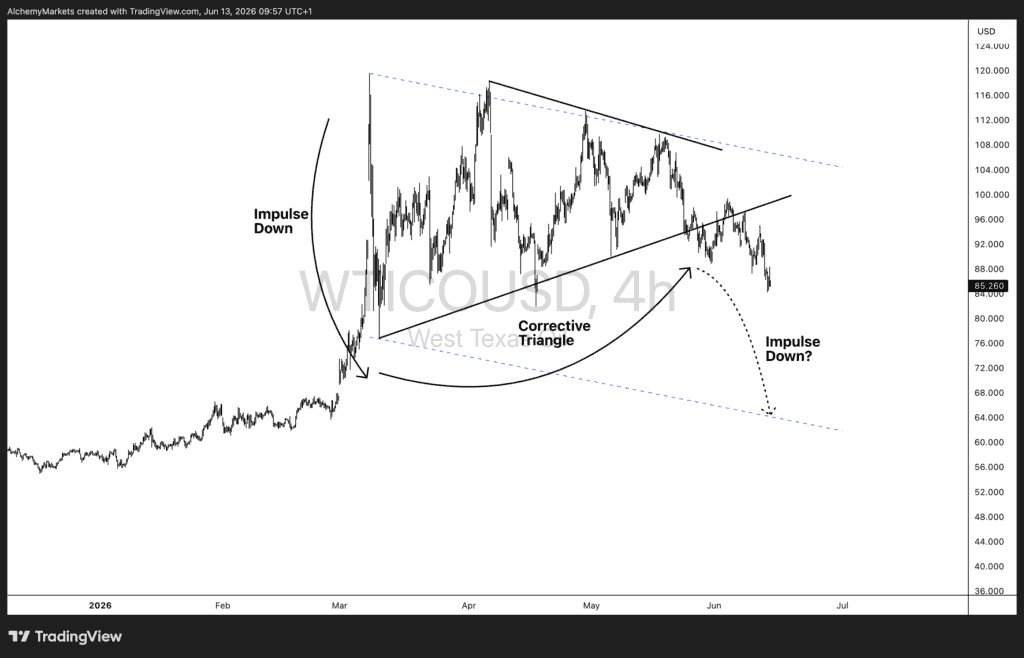
The chart has been telling this story ahead of the headlines, and it's lining up for a potential sequel.
Cast back to early March: oil printed a violent impulse down off the ~$120 spike, the first crack in the war premium. What followed wasn't a recovery — it was a corrective triangle, the textbook consolidation that forms between impulse legs while the market digests. Price has spent three months coiling inside that structure, chopping between a rising lower bound and the descending upper boundary of the broader channel, never convincingly reclaiming the highs.
Now the apex is behind us and price is leaning on the lower edge again, hovering in the mid-$80s. With the US–Iran conflict cooling and the supply-disruption bid deflating, the fundamental fuel for another upside spike is being pulled away just as the technical structure resolves lower. That's the confluence: a corrective pattern that wants to break down, meeting a catalyst that's fading exactly when bulls need it most.
The roadmap on the chart asks one question — Impulse Down? A decisive break and hold below the triangle's lower bound opens the path toward the descending channel's lower boundary, projected into the low-to-mid $60s as the dashed channel support slopes through the coming weeks. That would be a clean measured continuation of the move that started in March.
The invalidation is equally clean: oil doesn't move in a straight line, and any re-escalation — a stalled deal, a Hormuz flare-up — would slam the war premium straight back into the price and reclaim the triangle. Watch the lower channel boundary as the decision line. While price respects it from above, the structure favours the sellers; a strong reclaim of the triangle flips the script.
The market is doing what it always does — pricing the change in narrative before the narrative is officially confirmed. Peace is being negotiated on the wires; the chart is already trading the comedown.
Alchemy Markets is a multi-asset brokerage providing retail traders with the same elite trading conditions, tools, and transparency typically reserved for institutions.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Marex has entered the football financing market through a partnership with specialist sports investment and advisory firm Pinto Capital, targeting clubs in the Premier League and EFL Championship.
Around 110,000 UK retail investors have secured $300 million worth of Anthropic shares in its record-breaking $81 billion IPO. The heavily oversubscribed offer, coordinated by RetailBook, saw smaller investors prioritised, with 63% of applicants receiving their full allocation.
Clear Street has completed its acquisition of Boom Securities (H.K.) Limited, establishing its first licensed brokerage presence in Hong Kong
Sterling slips to its lowest against the dollar since October as markets trim Bank of England bets and Fed minutes point to further US rate rises, while the euro hits a fresh one-year low. Daily FX analysis from Equals.
JT Prime, the institutional Prime of Prime founded by Raj Sitlani, Jonathan Brewer and Jeff Wilkins, is set to become the new home for institutional client relationships currently serviced by FXCM Pro. Clients have been offered the same leverage, fees and connectivity, ensuring continuity of trading conditions.
The Nasdaq 100 has shifted into a short-term bullish recovery after finding strong support around 26,611. Following the sharp sell-off, price has formed a sequence of higher lows and has moved back above the 20-hour moving average at around 27,270, while the 5-hour and 10-hour averages are also turning higher.
U.S. equity futures rose in the after hours, led by Nasdaq-100 futures up 1% and S&P 500 futures up 0.6%, as investors focused on Anthropic’s Nasdaq debut. The AI company priced its IPO at $83 per share, above expectations, and expanded the offering to raise around $81.3 billion, making it the largest IPO on record.
Brokers can offer LMAX perpetual futures alongside FX and CFDs through a single trading account. LMAX says brokers with existing credentials can go live in under five days.
24X National Exchange has filed a proposed rule change with the SEC to launch 24X Options, a general options market trading from 9:30 a.m. to 4:00 p.m. ET. The filing also covers binary KPI options on quarterly revenue, earnings per share and other metrics for 23 of the most actively traded U.S. companies.
cTrader Mobile 5.11 introduces Signals, a new app where traders can browse signals from leading providers and act on them directly in the platform.