As we head into a new week, Trump’s decision to delay further strikes on Iran may give markets some breathing room by pulling oil lower.
However, renewed Fed rate-hike expectations could keep Treasury yields and the US dollar strong, weighing on gold, silver and high-valuation technology shares, while AMD’s earnings will test whether heavy AI spending is producing enough growth, margins and cash flow to justify the Nasdaq rebound.
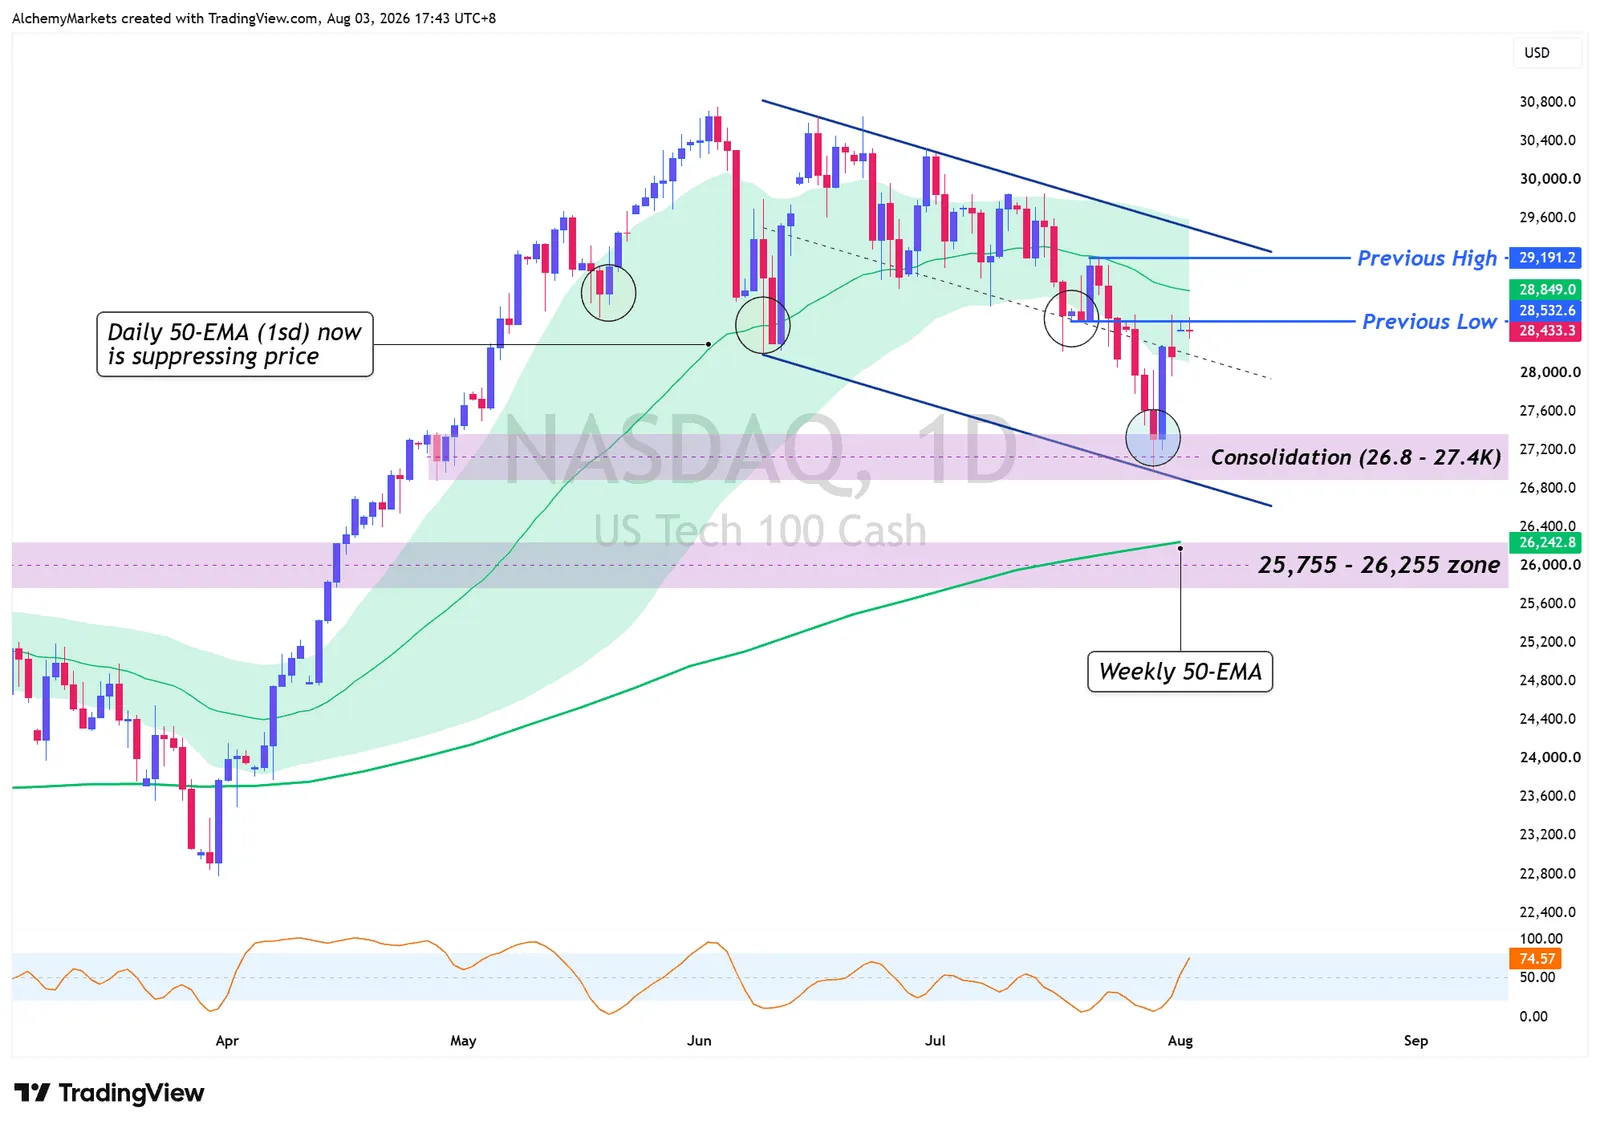
Technology stocks have recovered sharply from last week's lows. The Nasdaq rose roughly 5.4% from the 26,800 area, while the S&P 500 returned above its rising trendline after testing the value-area low near 7,314.
Chart 1. S&P 500 daily: The rebound is testing the Point of Control (red line) at $7,500 as resistance, after bouncing off the VAL (blue line) and reclaiming a trendline support. VIX has tapered off from 20.
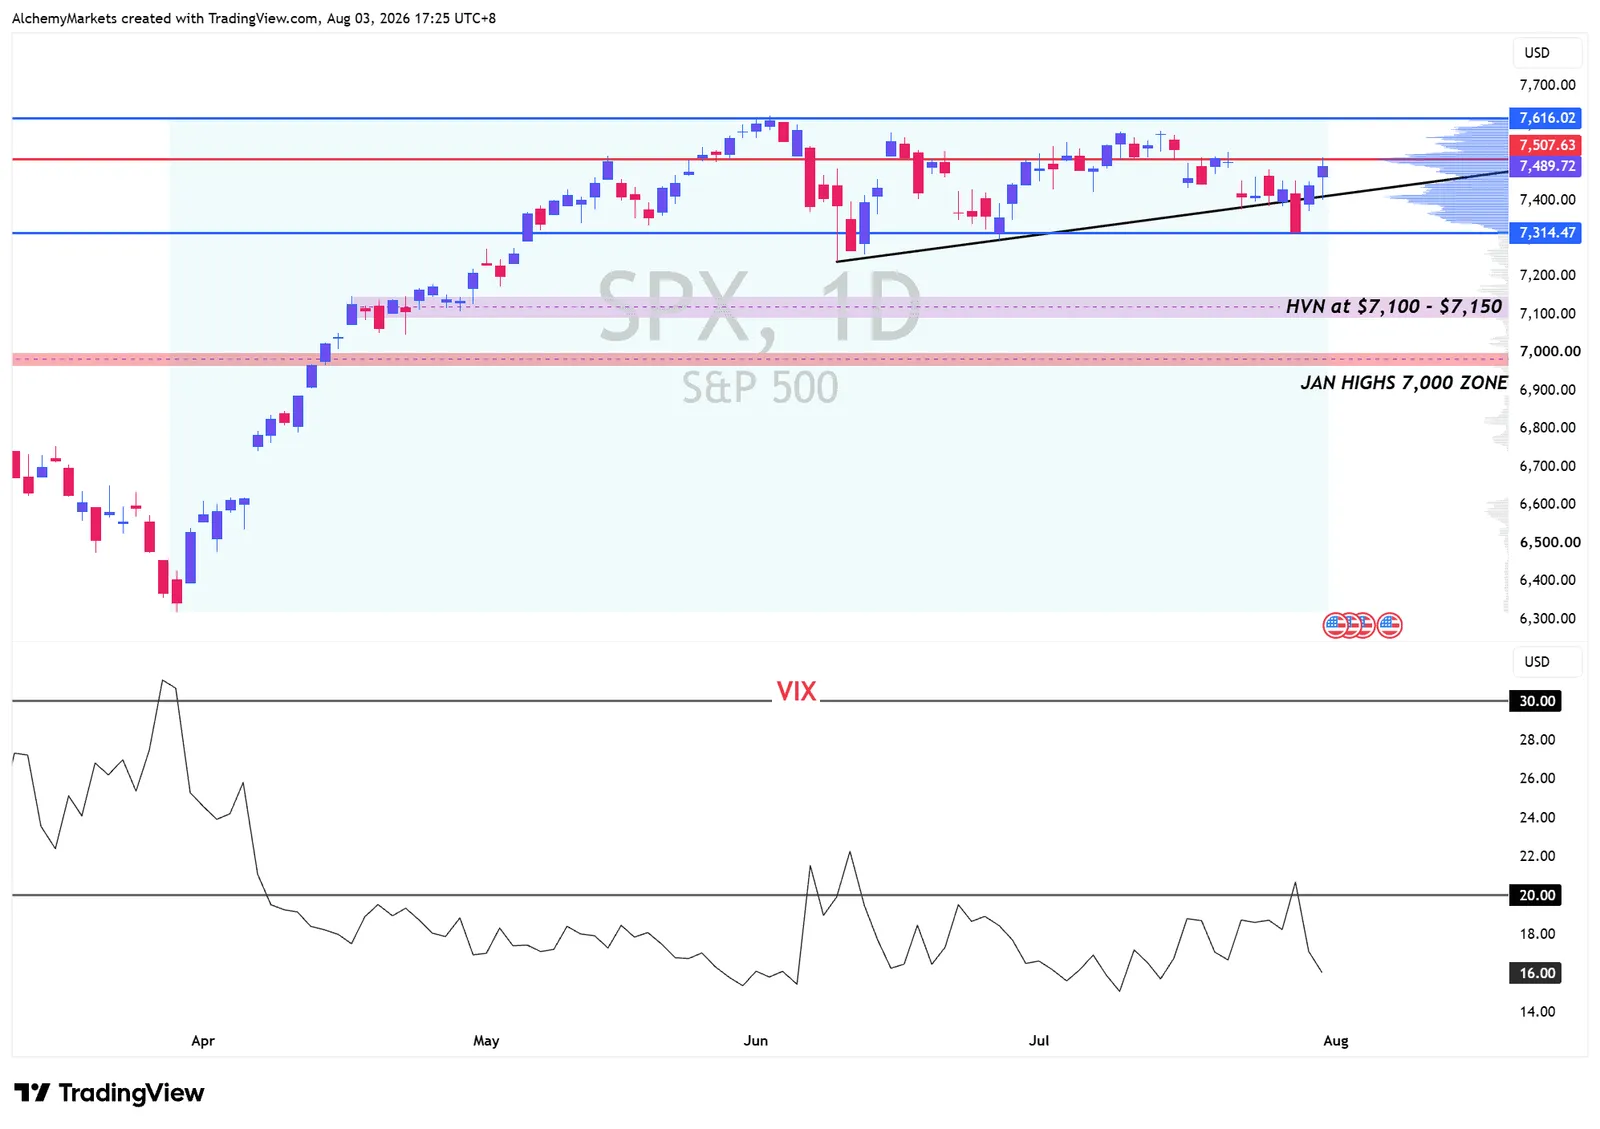
Chart 2. Nasdaq daily: The rebound is testing the previous low and daily 50-EMA band.
Several tests can change the move this week
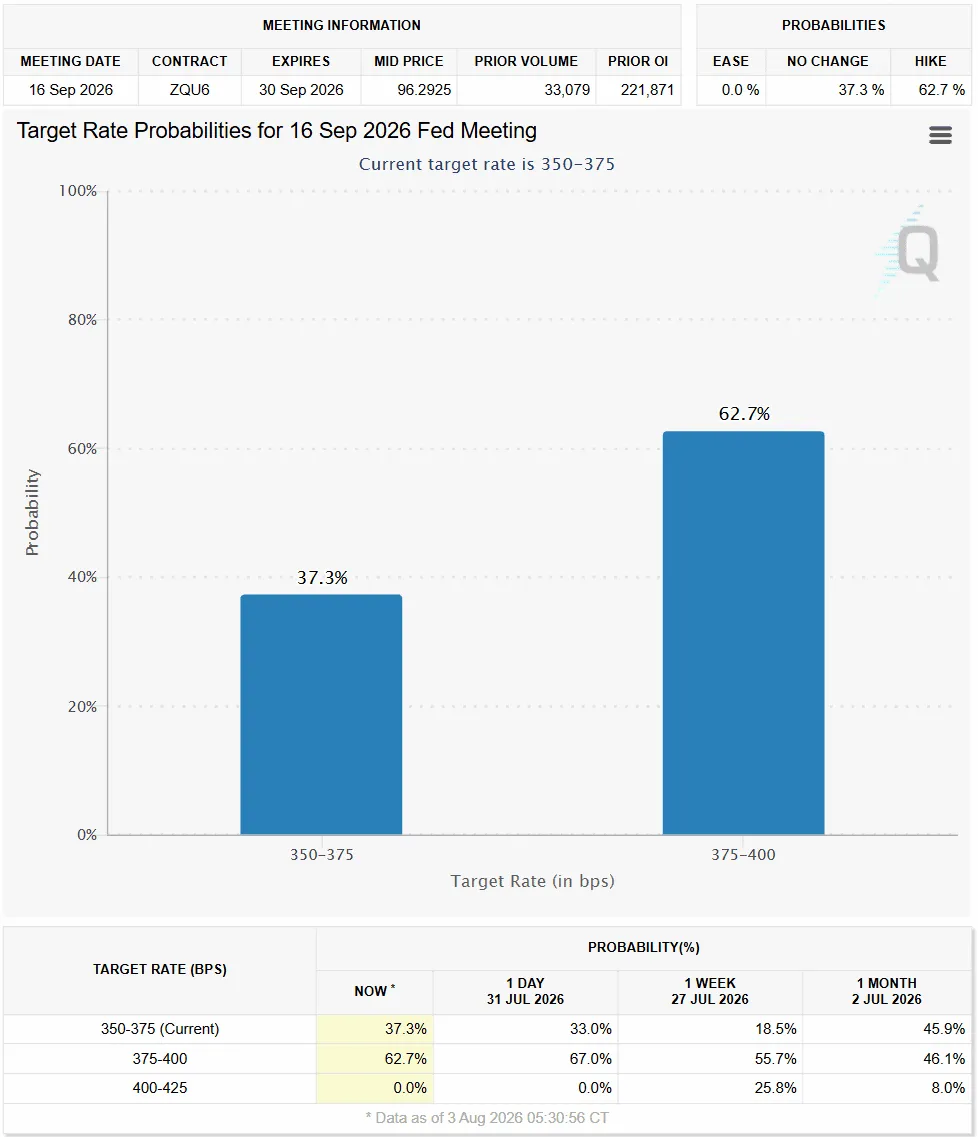
The Federal Reserve held rates at 3.50%-3.75% on 29 July, but three voters preferred a 25-basis-point increase.
That leaves technology shares sensitive to any data that pushes yields higher.
| Day | Event | Why markets care |
| Monday | ISM Manufacturing | Demand and prices can move yields. |
| Tuesday | JOLTS and AMD | Labour data and the main chip test. |
| Wednesday | ISM Services | Broader demand and price pressure. |
| Friday | US jobs report | Payrolls and wages shape Fed pricing. |
Together, these releases will confirm whether yields continue falling, or whether stronger growth and inflation sustain expectations for a September rate increase.
Currently, the September expectation sits at 62.7% for a 25bps hike, which is going to have a suppressive effect on equities (if earnings don’t outperform and capex concerns aren’t addressed), gold and silver.
Cheaper oil removed one immediate pressure
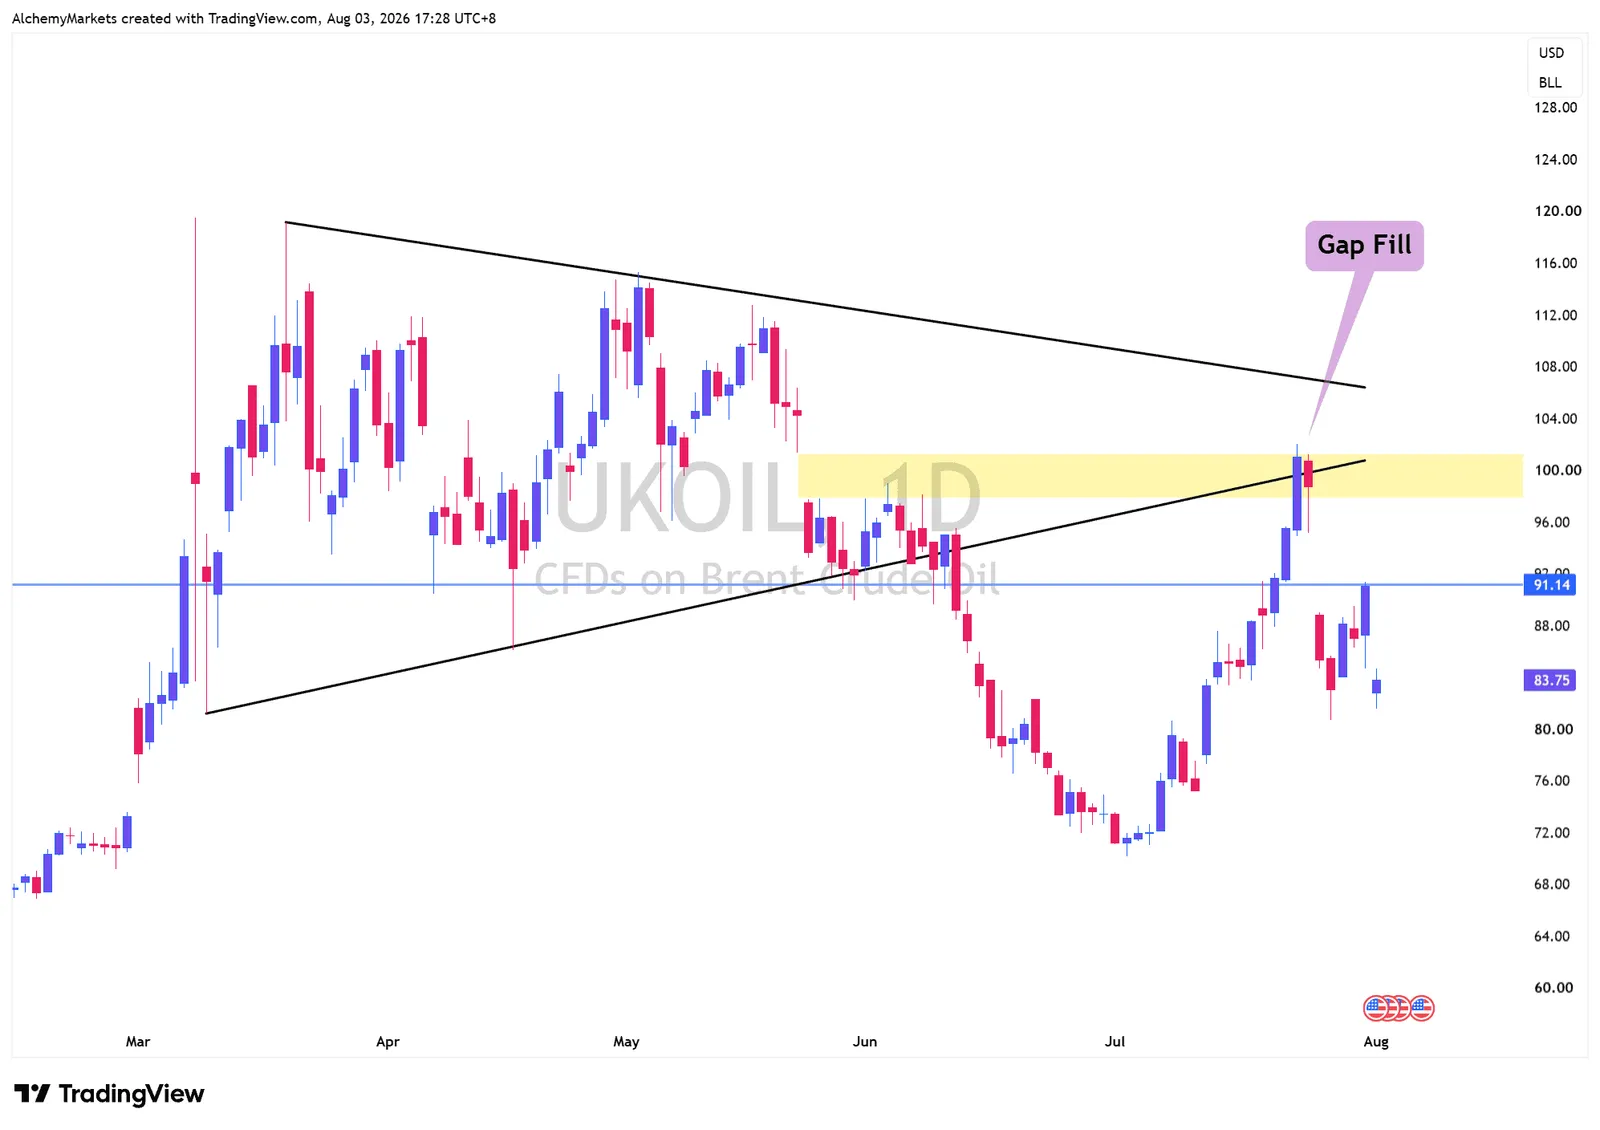
Brent crude gapped lower after another rejection from the $98-$101 area. The move followed Trump’s decision to delay further strikes on Iran while diplomatic discussions continued, reducing the immediate risk of another disruption to energy supplies.
Lower oil reduces headline inflation pressure, can pull Treasury yields lower and eases the discount-rate pressure on expensive technology shares.
June CPI fell 0.4% from May and core CPI was unchanged as energy dropped 5.7%. Producer prices also fell 0.3%, although annual final-demand PPI remained high at 5.5%, showing that one month of energy relief has not removed upstream inflation.
However, the move still depends on political expectations. Iran denied that direct US talks were under way, while shipping through Hormuz has not returned to normal. Until oil remains lower and physical conditions improve, this is relief rather than confirmation of lasting de-escalation.
Chart 3. Brent daily: the market rejected the gap-fill area and gapped lower, but the geopolitical path remains conditional.
Can the rebound hold?
The rebound has repaired some of the technical damage, but it has also relied on falling oil, yields and volatility.
ISM will test whether inflation pressure is easing, while AMD will test whether AI demand can support the semiconductor recovery.
Until the Nasdaq reclaims its daily 50-EMA band, this move remains a short term rally rather than a confirmed reversal.