just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
Aussie Underperforms; Yen, Euro Edge Up, Yields Ease
Summary:
The Dollar Index (DXY), a popular gauge of the Greenback’s value against a basket of 6 major currencies eased modestly after US Headline Inflation eased to 3.1% in November from 3.2% previously. Economists had forecast annual US CPI at 3.1%.
At the close of trade in New York, USD/DXY dipped to 103.87 (103.97). The Greenback finished modestly lower against most Rivals. The USD/JPY pair edged lower to 145.65 (145.95), while the Euro (EUR/USD) climbed to 1.0790 from 1.0765.
Ahead of the conclusion of tonight’s (tomorrow morning Sydney) Federal Reserve FOMC meeting, market participants expect the US central bank to keep interest rates steady.
Chair Jerome Powell’s remarks, as well as the Fed’s dot plot forecast, which is the projection of the key short term interest rate, will be closely scrutinized.
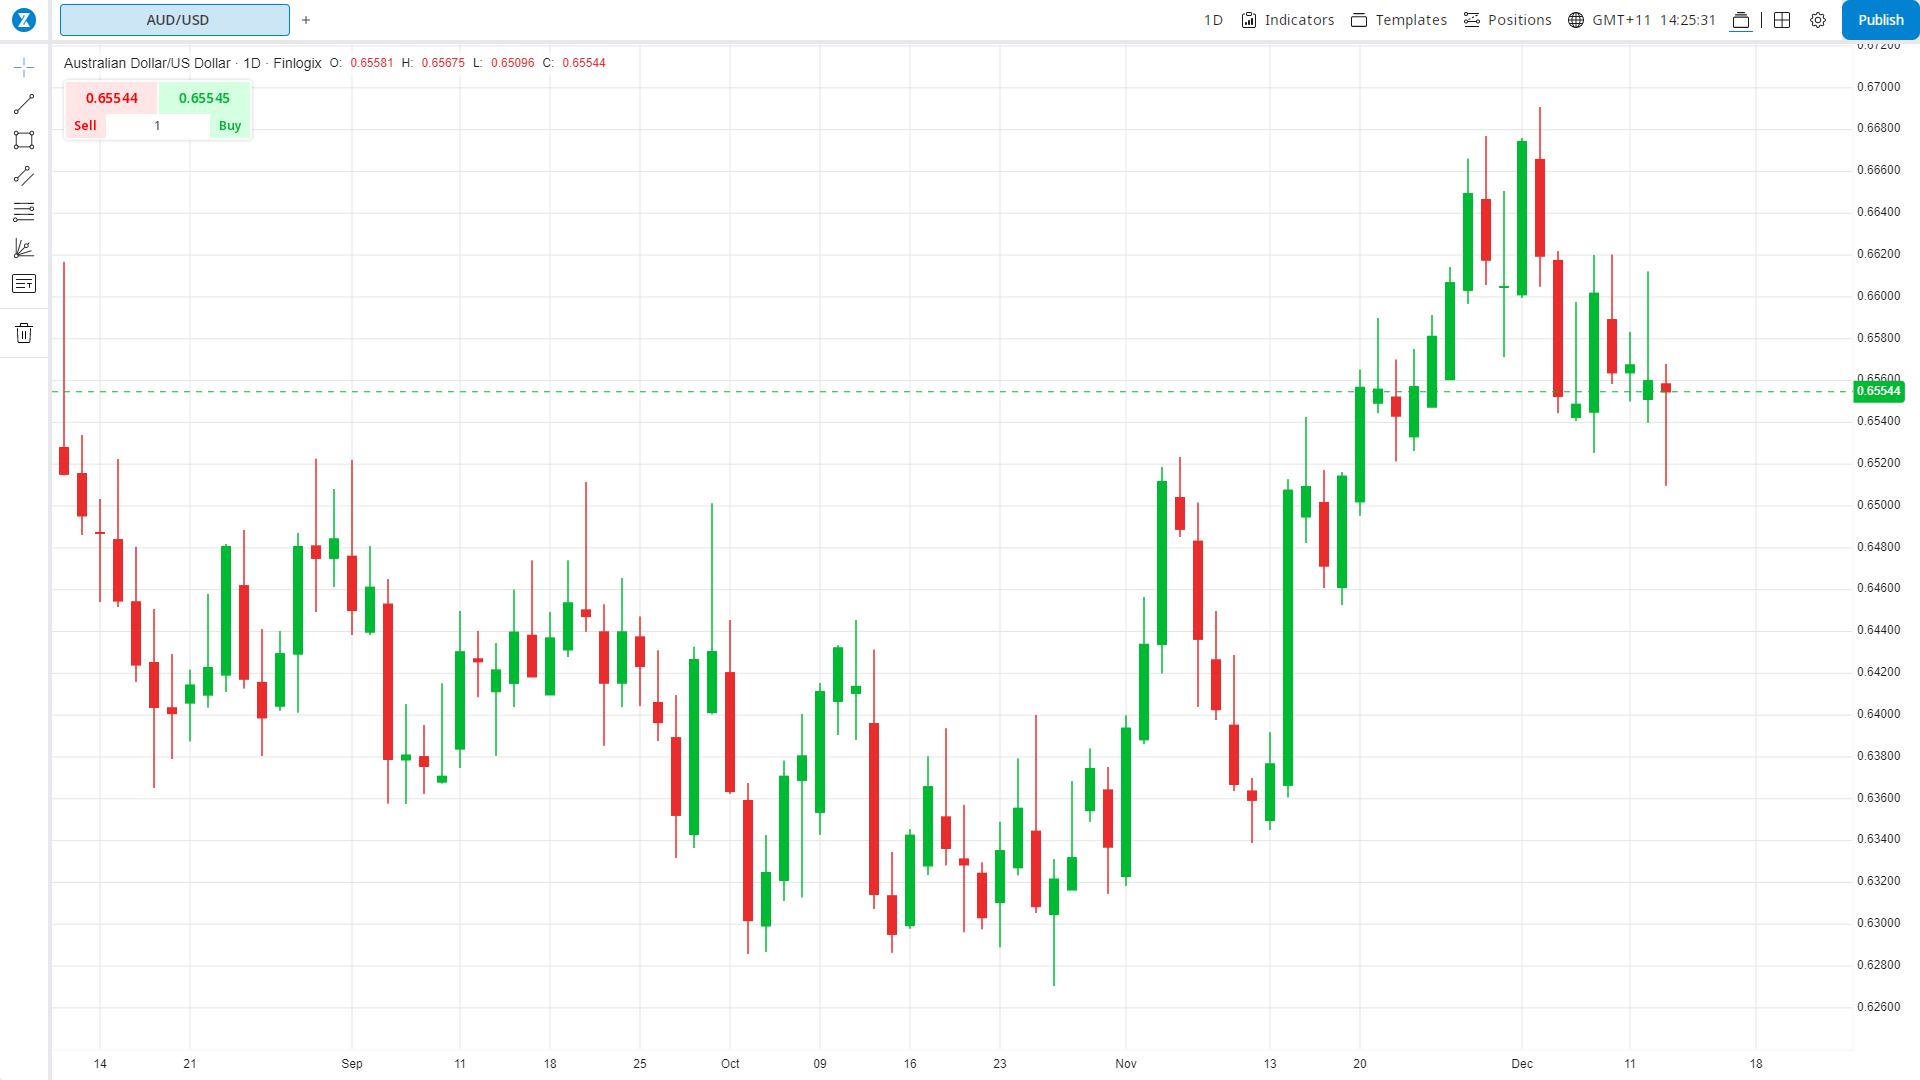
The Australian Dollar (AUD/USD) underperformed, slipping to 0.6555 from 0.6577 earlier in the week. The Aussie Battler traded around its recent range between 0.6540 and 0.6620.
Sterling (GBP/USD) grinded higher to finish at 1.2560, modestly higher than its 1.2535 finish earlier this week. Despite a drop in the UK’s Claimant Count Change (change in the number of unemployed people), Britain’s Jobless rate was unchanged, at 4.2%.
Against the Asian and Emerging Market Currencies (EMFX), the Dollar finished mixed. The USD/CNH (Dollar-Offshore Chinese Yuan) pair dipped to 7.1830 from 7.1895. The Greenback gained versus the Thai Baht (USD/THB) to 35.55 from 35.40 previously.
Global bond yields eased. The benchmark US 10-year treasury bond rate settled at 4.20% (4.23%). Germany’s 10-year Bund yield was last at 2.22% from 2.27% yesterday.
Other economic data released yesterday saw Japan’s Producer Price Index (PPI) climb to 0.3% year-on-year, down from 0.9% previously, but higher than median forecasts at 0.1%.
Germany’s ZEW Economic Sentiment Index climbed to 23.0 from 13.8 previously, beating median estimates at 13.3. The Euro soared to its overnight peak at 1.0828 following the release before easing to 1.0792 in late New York.
Wall Street stocks rallied. The DOW closed at 36,537, up from 36,227 while the S&P 500 rose to 4,637 (4,603). Other global share indices edged higher. Australia’s ASX 200 rallied to 7,235 (7,215).
On the Lookout:
Today’s economic calendar kicks off with New Zealand’s Q3 Current Account (q/q f/c -NZD 10.848 billion from -NZD 4.208 billion previously – ACY Finlogix).
New Zealand also releases its November Food Inflation (y/y f/c 5.8% from 6.3% previously – ACY Finlogix).
Next up is Japan’s Tankan Large Manufacturer’s Index (f/c 10 from 9 previously – ACY Finlogix), and Japanese Tankan Small Manufacturer’s Index (f/c -4 from -5 – ACY Finlogix).
The UK starts off Europe with its UK October Goods Trade Balance (f/c -GBP 14.8 billion from -GBP 14.288 billion – ACY Finlogix), UK October GDP (m/m f/c 0% from 0.2%; y/y f/c 0.6% from 1.3% - ACY Finlogix), UK October Industrial Production (m/m f/c -0.1% from 0%; y/y f/c 1.1% from 1.5% - ACY Finlogix), UK October Manufacturing Production (m/m f/c 0% from 0.1%; y/y f/c 0 from 0.1% - ACY Finlogix).
China releases its November New Yuan Loans (f/c CNY 1300 billion from CNY 738.4 billion – ACY Finlogix). The Eurozone follows with its Eurozone October Industrial Production (m/m f/c -0.3% from -1.1%; y/y f/c -4.6% from -6.9% - ACY Finlogix).
The US rounds up today’s economic data releases with its US November PPI (m/m f/c 0.0% from -0.5% - ACY Finlogix) and US November Core PPI (m/m f/c 0.2% from 0% - ACY Finlogix).
The US Federal Reserve is not expected to change its Fed Funds Rate of 5.5% at the conclusion of its FOMC monetary policy meeting tomorrow morning (6 am Sydney).
Trading Perspective:
The Dollar eased modestly after US Headline Inflation eased on a year-on year basis to 3.1% from 3.2% previously.
Core US November inflation though was unchanged, at 4%. Markets will be scrutinizing tomorrow morning’s Fed dot plot forecast and remarks from Fed Chair Jerome Powell which follows the FOMC meeting.
The US central bank is widely expected to keep the Fed Funds rate unchanged at 5.5%. Tomorrow sees 3 other central bank monetary policy meetings.
They are the Swiss National Bank, the European Central Bank, and the Bank of England. All are expected to keep their monetary policies unchanged. The Bank of Japan holds its policy meeting early next week.
What this tells us is that FX volatility will remain elevated, as it traditionally does during the month of December. It’s vital to keep those tin helmets on, with opinions flexible.
(Source: Finlogix.com)
Look for another riveting day in FX land. Happy Wednesday and trading all.
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
US equities were volatile with technology selloff erasing much of the earlier rebound.
FM Summit London 2026 returns to Old Billingsgate on 24 November for its 15th edition, with LMAX Group, Plus500 and oneZero among confirmed exhibitors. The one-day event adds Business Connect meetings and roundtables, and opens with a networking evening at The Folly on 23 November.
Finance Magnates Summit London returns to Old Billingsgate on 24 November 2026 for its 15th edition. The one-day event brings together brokers, liquidity providers, institutional firms, trading technology vendors, payments businesses and digital asset firms.
iSAM Securities Apex has integrated with Match-Prime, giving brokers access to liquidity across more than 2,000 instruments, with tailored pricing and up to 10 levels of market depth.
propfunding.com's free-entry instant funding changes the order of prop funding. Start trading first. Its free-entry instant funding model offers two qualification attempts without an upfront activation fee.
US stocks closed higher on Wednesday, with the Nasdaq gaining 1%, the S&P 500 rising 0.6%, and the Dow advancing 0.7%, as renewed enthusiasm for AI-related stocks lifted market sentiment.
SpaceX went public in June as a rocket company. On October 20 it reported as something else entirely: an AI infrastructure business, financed by a satellite broadband network, with a launch division attached. Rockets generated 12% of third quarter revenue and lost money. The AI segment generated 52% of revenue and consumed 84% of capital expenditure. Starlink generated 85% of operating profit.
Standard Chartered has signed definitive agreements to acquire 100% of Zodia Custody UK Limited, folding its regulated digital asset custody business into Securities Services. Zodia Solutions will be set up under SC Ventures with bank investors including Northern Trust, NAB Ventures, Emirates NBD and Investcorp.
Bybit Fintech FZE has secured a Virtual Asset Service Provider licence from Dubai’s Virtual Assets Regulatory Authority for Exchange Services, covering spot trading. Bybit’s Peter Loo said the firm hopes to add derivatives, subject to regulatory approvals. Its international Dubai headquarters opened in 2022.
ATFX Connect has released its Q4 2026 Institutional Edge, examining the geopolitical, monetary policy and fiscal pressures shaping global financial markets in the final quarter of the year.