just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

Non-Farm Payrolls (Wednesday)
While headline labour market conditions have avoided outright deterioration, the underlying picture remains fragile. Firings remain contained, but hiring momentum continues to disappoint. Excluding government, leisure & hospitality, and private education and healthcare, the US economy has shed jobs in seven of the past eight months. We expect January’s delayed NFP report to reflect a similar pattern.
The January FOMC statement removed the reference to “downside risks to employment” while noting “some signs of stabilisation” in the unemployment rate. We expect unemployment to remain steady at 4.4%, though risks are skewed to the upside in coming months as hiring remains sluggish and labour supply continues to rise. Markets should also be alert to benchmark revisions, which could materially lower the reported pace of job creation over the past year and reinforce the view that the labour market has been weaker than previously assumed.
CPI Inflation (Friday)
January CPI, delayed from Wednesday to Friday, will be closely scrutinised. While several private-sector inflation indicators have cooled sharply, we still see scope for stickiness in the official data. Delayed tariff pass-through remains a key risk: import prices are rising, and tariff revenue is being absorbed by US importing firms.
Although some companies suggest “efficiency savings” are offsetting these cost pressures, we believe further consumer-level pass-through cannot be ruled out. That said, lower energy prices and continued moderation in housing rents should provide an important offset, limiting the upside risk to headline inflation.
UK GDP (Thursday)
Fourth-quarter growth should appear relatively resilient, helped by the restart of car production at a major manufacturer. However, this strength is unlikely to alter the Bank of England’s policy outlook. Policymakers have repeatedly argued that recent GDP figures overstate the underlying health of the economy, with public sector output accounting for a disproportionate share of growth.
This week’s BoE meeting reinforced expectations for a March rate cut, as weak private-sector momentum and easing inflation pressures continue to dominate the policy debate.
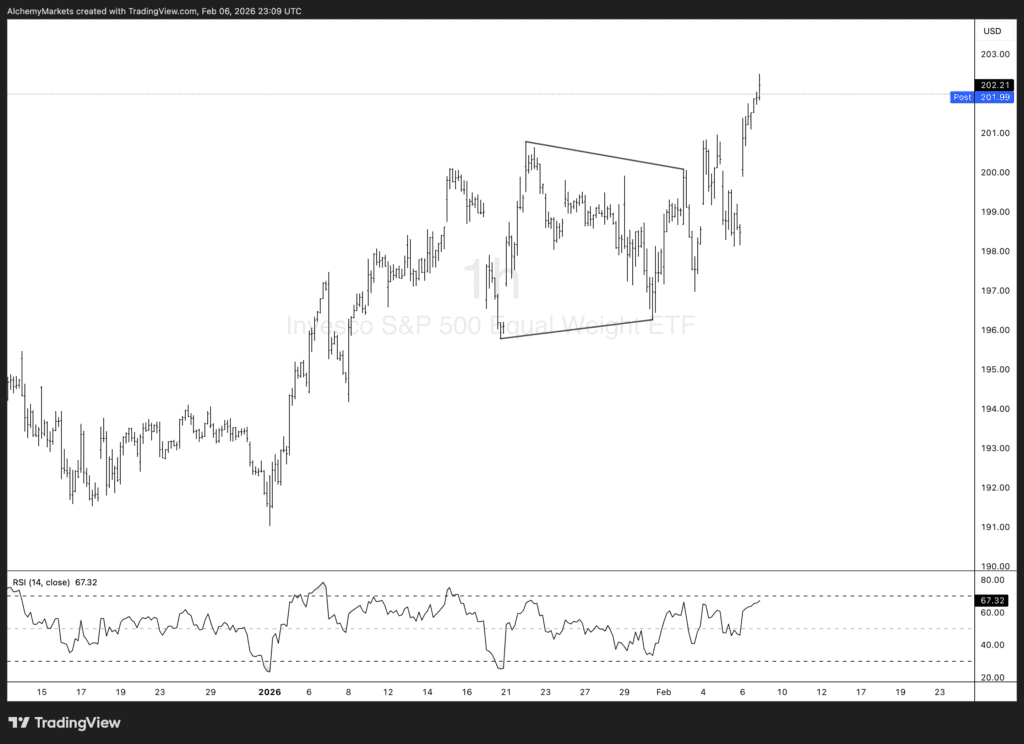
From a technical standpoint, caution around headline indices remains warranted. The traditional market-cap-weighted S&P 500 continues to look toppy, reflecting the heavy concentration in a small group of mega-cap stocks.
However, the S&P 500 Equal Weight index—which gives each constituent the same influence regardless of size—has delivered a more constructive signal. It has broken out to new highs, resolving a multi-week triangle pattern to the upside. Importantly, the breakout has been accompanied by RSI momentum that remains elevated but not yet overextended, suggesting there is still some energy left in the move.
This divergence highlights improving market breadth beneath the surface and suggests that, while index-level risks remain, participation across the broader market has quietly strengthened—an important dynamic to watch as macro data and central bank expectations evolve.
Alchemy Markets is a multi-asset brokerage providing retail traders with the same elite trading conditions, tools, and transparency typically reserved for institutions.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS Feed
just now
Sign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
The AI trade has always been a supply chain story. For the past two years, the narrative has been simple: insatiable demand for compute infrastructure, constrained supply at every choke point, and the companies that own the bottlenecks collect the toll. NVIDIA on GPUs. ASML on lithography. Samsung, SK Hynix, and Micron on memory. The entire semiconductor complex has traded on scarcity, and scarcity has delivered historic margins.
Interactive Brokers reported customer equity of USD 964.7 billion at the end of the third quarter, up 27% year on year, as customer accounts increased 35% to 5.58 million.
Crypto exchange BingX has secured a Markets in Crypto-Assets Regulation (MiCA) licence for its European arm from Austria's Financial Market Authority (FMA).
CXM Group has agreed to acquire TD Markets (Pty) Ltd, a Johannesburg-headquartered broker authorised by South Africa’s FSCA. TD Markets keeps its brand, team and licence, and Amar Ramith stays as CEO. Financial terms were not disclosed. The deal gives CXM a regulated base in South Africa. Clients need take no action.
Global equities under pressure: Hotter than expected US inflation and rising yields weighed on stocks, particularly technology and semiconductor shares.
Understand trading psychology and learn how a clear strategy, risk management and a trading journal help build discipline and day trading consistency.
Ripple Prime has launched support for real-world asset perpetual swaps, giving institutional clients including Virtu exposure to more than 100 reference markets across equities, indices, ETFs, metals, energy and FX. The swaps reference Trade.xyz perpetual futures on Hyperliquid and trade and settle around the clock.
iSAM Securities Apex has integrated with Crossover Markets, connecting brokers to CROSSx, its institutional digital asset ECN, through Apex’s ultra-low-latency technology stack.
Your Bourse and 4XPORTAL highlight their existing partnership, combining client onboarding, CRM and payment solutions with liquidity, execution and risk-management infrastructure for brokers.
The partnership brings together 4XPORTAL’s brokerage technology capabilities with Your Bourse’s connectivity, liquidity aggregation, and risk-management infrastructure.