just now


Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

With inflation expected to rise more sharply over the next three to six months, global currency markets are entering a more policy-driven phase. The key differentiator will be which central banks are willing to keep real interest rates—that is, rates adjusted for inflation—firmly in restrictive territory.
In this environment, currencies linked to more hawkish central banks are likely to find support. We are already seeing early signs of this shift. The European Central Bank is now expected to deliver another rate hike as soon as June, while further policy tightening remains on the table in Australia and Norway. These central banks appear increasingly focused on preventing a renewed inflation cycle, even at the cost of slower growth.
By contrast, the Federal Reserve looks less likely to re-engage in an aggressive tightening cycle. While inflation risks remain elevated in the US, the balance between growth and price pressures appears more delicate. As a result, the Fed is expected to remain cautious rather than overtly hawkish.
This divergence in policy outlooks is critical. If other central banks continue tightening while the Fed holds back, interest rate differentials will begin to move against the US dollar. Over time, this should lead to a softer dollar, particularly against currencies where real yields are being actively supported.
In short, the next phase for FX markets will be less about absolute inflation levels and more about policy response credibility—specifically, which central banks are willing to act decisively to contain inflation, and which are not.
It’s a quieter week for economic data, so markets will mainly focus on talks between the US and Iran. If the two sides reach a deal and tensions ease—especially around the important oil route called the Strait of Hormuz—it would likely calm markets.
But if talks fail, things could go the other way. Investors may get nervous, stock markets could fall, and the US dollar might rise. That’s because oil prices could stay high, pushing up inflation and making it harder for the Federal Reserve to cut interest rates anytime soon.
The Federal Reserve is in its “quiet period” before its next meeting on April 29, meaning officials won’t be speaking publicly. However, there’s still attention on Kevin Warsh, who is being considered as the next Fed Chair. His confirmation hearing is on April 21.
Warsh used to be seen as someone who prefers higher interest rates, but since he’s been nominated by Donald Trump—who wants lower rates—people will be watching closely to see what he says. He’s likely to suggest that lower rates could make sense eventually, but only if the economy supports it.
He also believes that technology and AI investment could help the US economy grow faster without causing inflation, which is a view some Fed members agree with.
However, his approval may not be straightforward. There are political disagreements that could delay the process.
As for economic data, the key report this week is March retail sales (how much consumers are spending). Sales may look stronger partly because of higher petrol prices and better car sales.
But the more important figure strips out things like cars and fuel. This “core” measure is expected to show only a small increase. If that happens, it would suggest that consumer spending is still weak, especially as people feel financially squeezed and less confident.
This week, the focus is on jobs, wages, and inflation.
However, the full impact on household energy bills won’t be seen until July, when price caps are updated.
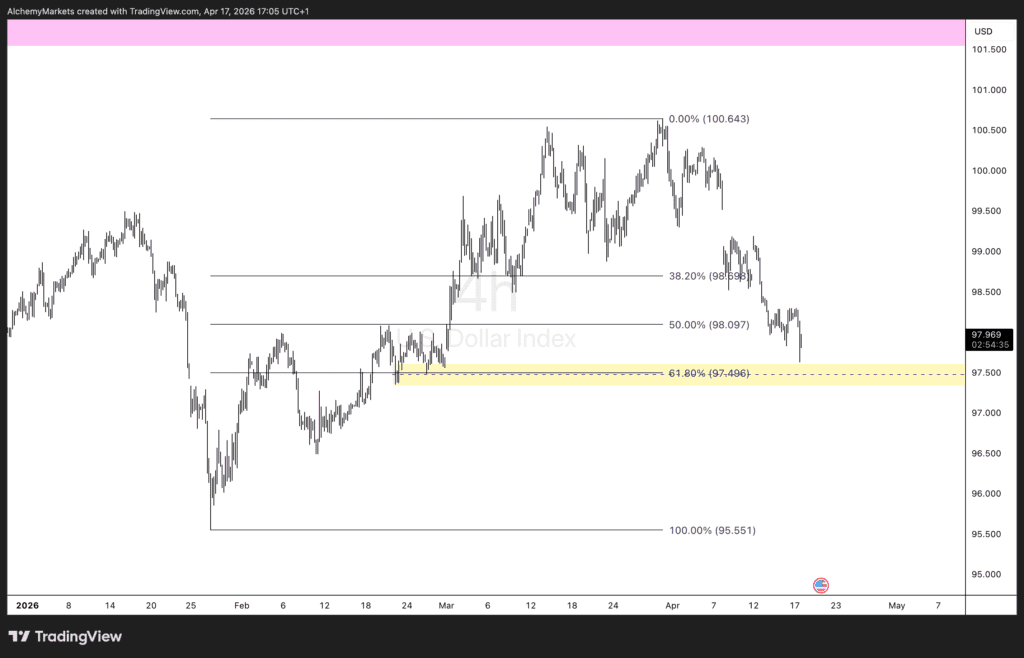
From a technical perspective, the DXY is currently trading around the 61.8% Fibonacci retracement level, a zone widely viewed as a key inflection point in trending markets. This level, often referred to as the “golden ratio,” tends to act as strong support during corrective phases.
The recent price action suggests that the dollar has been moving within a broader bearish impulse structure, with lower highs and a gradual loss of upside momentum following its peak near the 100.60 area. The pullback into the 61.8% retracement—around the 97.50 region—places the index at a technically significant support zone.
Holding this level could trigger a short-term corrective bounce, effectively unwinding part of the bearish move. In this scenario, a move back toward the 50% retracement or even the 38.2% level would not be surprising, particularly if macro catalysts (such as rate expectations or geopolitical developments) provide support.
However, the broader structure still leans bearish. A decisive break below the 61.8% level would likely confirm continuation of the downside impulse, opening the door toward the 100% retracement area near 95.50.
In summary, the DXY is at a critical juncture:
This aligns closely with the macro view of a potentially softer dollar, but near-term price action may first see a technical correction before any sustained decline resumes.
Alchemy Markets is a multi-asset brokerage providing retail traders with the same elite trading conditions, tools, and transparency typically reserved for institutions.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Brokers can offer LMAX perpetual futures alongside FX and CFDs through a single trading account. LMAX says brokers with existing credentials can go live in under five days.
24X National Exchange has filed a proposed rule change with the SEC to launch 24X Options, a general options market trading from 9:30 a.m. to 4:00 p.m. ET. The filing also covers binary KPI options on quarterly revenue, earnings per share and other metrics for 23 of the most actively traded U.S. companies.
cTrader Mobile 5.11 introduces Signals, a new app where traders can browse signals from leading providers and act on them directly in the platform.
ATFX Group has partnered with South Africa-based payment and digital asset infrastructure provider FiveWest to support institutional fund movements for ATFX Connect and add a cryptocurrency funding option for eligible retail clients. Both firms hold FSCA Over-the-Counter Derivative Provider licences.
UK inflation rose to 3.6% in October, keeping a December Bank of England rate rise likely, while the euro hit a fresh one-year low against the dollar ahead of tonight’s Fed minutes. Daily FX analysis from Equals.
GBPUSD has shifted decisively lower. After reaching 1.3228, the pair reversed and initially consolidated around the moving averages before breaking sharply below the 1.3180 area. It is now trading near 1.3169.
Nvidia shares jumped around 4% after hours after beating earnings and revenue expectations and raising its outlook for 75% year on year revenue growth through January 2028. The positive Nvidia results also lifted AI-related stocks, with CoreWeave up 8% and Nebius 10%.
Deutsche Börse Group has appointed Maximilian Weissenrieder as Head of Cash Market from 1 January 2027, succeeding Eric Leupold, who becomes CEO of Eurex. Weissenrieder has led Group M&A and Venture Investments since October 2024 and will retain those duties until a successor is named by the Group.
DEXA, the AI-powered risk management and analytics platform developed by TFB (Tools for Brokers), has connected with Match-Trader, bringing real-time trader analysis and toxic flow detection to brokers on the platform. DEXA classifies trader behaviour from as early as the third trade, with no change to execution systems.
Poland's financial markets regulator, the Polish Financial Supervision Authority (Komisja Nadzoru Finansowego, KNF), is preparing a new product intervention on contracts for difference (CFDs)