just now
Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

The S&P 500 finally ran into the one thing equity bulls had been ignoring for weeks: the bond market.
Friday’s selloff was not driven by earnings weakness or a sudden collapse in AI enthusiasm. It was a repricing event caused by rising yields, renewed inflation fears, and a sharp move higher in oil prices. The clean macro chain driving markets was straightforward:
oil spike + inflation fears → Treasury yields surge → Fed hike odds rise → valuation pressure on growth stocks → SPX and Nasdaq sell off.
Markets had spent the last month aggressively pricing a “goldilocks” scenario where inflation cooled enough for the Fed to eventually ease while AI-driven growth continued to push equities higher. Bonds are now challenging that narrative.
As inflation concerns resurfaced, Treasury yields broke higher across the curve. The US 10-year yield climbed toward 4.60%, the 30-year pushed above 5.10%, and the 2-year also moved sharply higher. That combination signals the market is beginning to reprice both inflation risk and the possibility of tighter Fed policy later this year.
At the same time, crude oil surged as geopolitical tensions in the Middle East added another layer of inflation anxiety. Higher energy prices threaten to feed directly into future CPI readings, particularly after earlier inflation data already showed price pressures remaining sticky.
The result was classic multiple compression.
When yields rise, especially real yields, the discount rate on future earnings increases. That matters most for long-duration assets — mega-cap tech, semiconductors, software, and AI-related equities that had led the rally to record highs. Nasdaq underperformed because those sectors are the most sensitive to changes in rates.
There was also a positioning issue underneath the surface. Equity markets had become heavily concentrated in the AI momentum trade, and sentiment was extended. Once yields broke higher, traders quickly moved to reduce exposure in crowded growth names.
This is why the move matters beyond a simple one-day pullback.
The first-order reaction is straightforward: higher yields pressure equities. The second-order question is whether rising rates begin triggering broader de-risking across positioning, market breadth, and credit. If yields continue climbing while leadership deteriorates, the probability of a deeper SPX correction rises significantly.
For now, this still looks more like a rates shock than an earnings shock. But the bond market is now firmly back in control of macro pricing.
It is a relatively quiet week for US economic data, with the primary focus turning toward housing activity.
Housing starts data will provide another read on how elevated mortgage rates and affordability pressures are impacting the broader economy. The housing market remains one of the most rate-sensitive sectors, and current financing conditions continue to act as a major headwind for new construction and buyer demand.
If housing data weakens further, it would reinforce the idea that tighter financial conditions are beginning to slow growth more materially.
Markets will also closely watch the latest FOMC minutes.
The minutes are expected to reinforce the hawkish shift that emerged during April’s meeting, particularly after several Fed officials pushed for more neutral language regarding future rate cuts. Traders are increasingly focused on whether policymakers are becoming more concerned about inflation persistence rather than slowing growth.
With rate hike odds rising again, any indication that the Fed is uncomfortable with easing financial conditions could keep pressure on equities and bonds alike.
UK inflation will be the key international macro release next week.
Headline CPI is expected to dip slightly in April despite higher energy prices, largely because of temporary distortions tied to Easter timing and the absence of some regulatory price increases that boosted inflation last year.
Markets will also focus heavily on services inflation and wage-sensitive components of the report. Signs that wage growth is cooling and economic slack is increasing could support the argument that domestic inflation pressures are finally moderating.
If inflation comes in softer than expected, it may allow some Bank of England officials to become less concerned about second-round inflation effects stemming from the recent energy shock.
That would likely support expectations for eventual policy easing later this year.
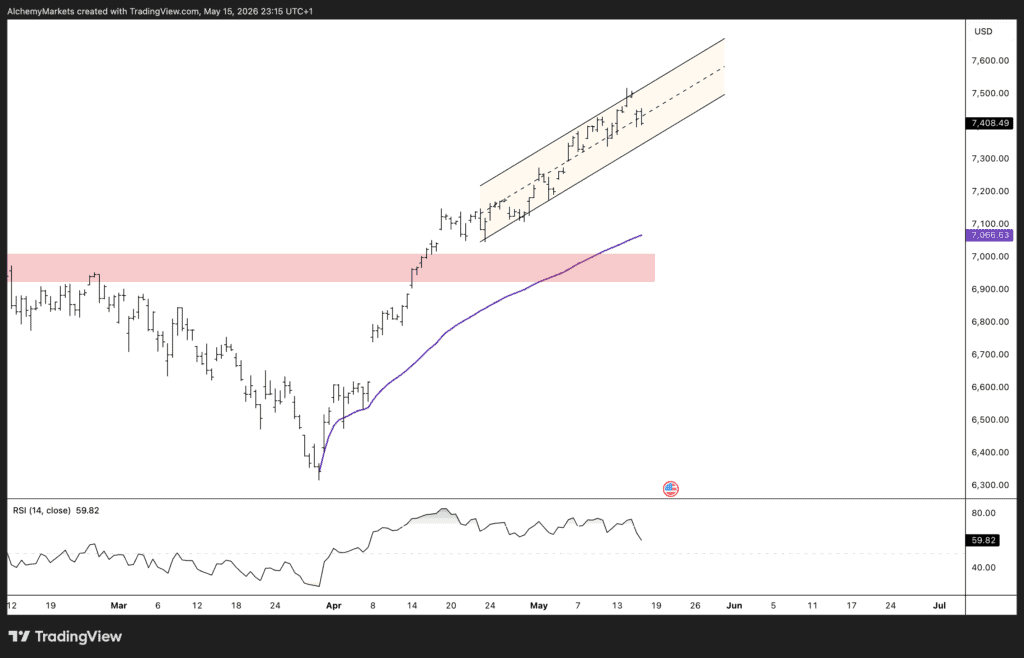
From a technical perspective, SPX remains trapped inside a well-defined rising channel following its sharp breakout above the 7000 region earlier in the quarter.
The problem for bulls is that momentum is beginning to stall precisely as macro conditions deteriorate.
Inflation concerns are returning, oil prices are pushing higher, and the bond market is now tightening financial conditions independently of the Fed. That creates a difficult backdrop for equities, especially after such an aggressive AI-led rally.
Price action is now respecting the upper and lower boundaries of the rising channel almost perfectly. Recent highs failed to generate strong continuation momentum, while RSI has also started to cool from elevated levels, suggesting upside momentum may be fading.
The key level to watch is the lower boundary of the channel.
If SPX breaks below that structure decisively, it would likely confirm that yields are beginning to overpower equity momentum. In that scenario, the market could quickly unlock a deeper correction back toward the 7000 region, which now acts as a major psychological and structural support zone.
Technically, 7000 is important because it aligns with:
As long as SPX holds inside the channel, bulls still maintain control of the broader trend. But the margin for error is narrowing.
The market is no longer trading purely on AI optimism.
It is trading on whether yields continue rising faster than earnings expectations can compensate.
That makes the bond market the most important chart in the world heading into next week.
Alchemy Markets is a multi-asset brokerage providing retail traders with the same elite trading conditions, tools, and transparency typically reserved for institutions.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
WTI crude oil price forecast: A confirmed breakout above $94.765 could open the way toward $100.305, while weekly support remains at $87.360–$90.830.
NAS100 price forecast recap: Explore the Nasdaq 100 rally to 31,401.3, with technical analysis of the breakout and key support and resistance levels.
Learn how to identify, draw and trade XAUUSD supply and demand zones using Gold market structure, price action confirmation and clear risk management.
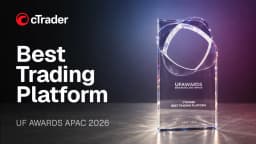
cTrader has been named Best Trading Platform at UF Awards APAC 2026 during iFX EXPO Asia in Hong Kong.
AUD/CHF reached last week’s 0.57732 bearish target. Learn how resistance, market structure and a neckline retest shaped the original price action forecast.
Businesses eventually reach a point where basic tools are not enough basic tools.
Multi-asset trading broker AvaTrade has agreed to acquire the majority of FXCM Group’s business and brand, in a transaction that would bring a longstanding retail FX franchise into the AvaTrade Group.
LSEG and CMC Markets have signed a multi-year strategic data agreement expanding CMC's access to LSEG's real-time and delayed pricing, reference and corporate actions data, news and analytics, plus AI-ready content, to support new products, entry into new markets and the growth of CMC's institutional and B2B partnerships.
The Tel Aviv Stock Exchange is considering a bid for the Cyprus Stock Exchange, with Israeli media citing its EU licence, trading platform and clearing house. Euronext’s Athens exchange and India’s National Stock Exchange are also seen as contenders, and Cyprus aims to sign a sale agreement by the end of this year.
CME Group will launch baseball futures on 12 October, pending regulatory review, tracking CME FutureSports Performance Indexes built on Official League Data. Standard and micro contracts will start with the 2026 Postseason and the four clubs in the League Championship Series, trading around the clock.