just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

Markets opened the week with fresh ISM data that continues to lean heavy. New orders contracted for a fourth straight month — coming in at 47.6, barely up from April’s 47.2, and still below the 12-month average of 48.6. This isn’t a one-off. We’ve now got a clean streak of weakening demand since the back half of 2022.
Panel commentary from the report backs that up. There’s no momentum shift here — still the same mix of soft overseas orders, ongoing tariff-related negotiations, and a slight edge toward concern on forward demand. The ratio of positive to negative comments? About 1 to 1.5 in favour of cautiousness.
Inventories told a similar story. Dropped to 46.7 from 50.8, back into contraction. First time we’ve seen that since February. The pull-forward on materials (tariff protection) looks done — now it’s about aligning stock levels with weaker expectations. Of the major manufacturing sectors, just two expanded inventory-wise last month. That’s not rotation — that’s hesitation.
Across the board, sectors are either sitting flat or easing. Not enough strength to push the needle forward, and not enough panic to scream recession — but very much a stall. A pause. A market that’s waiting, unsure if growth’s going to pick back up or if we’re drifting into a mild slowdown.
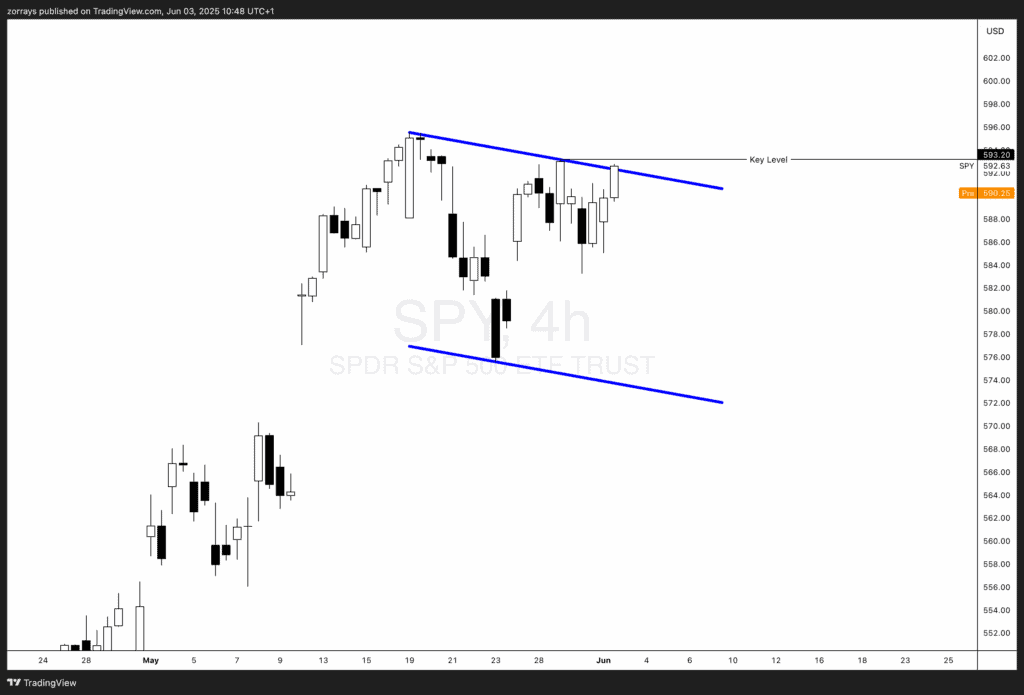
Here’s where price confirms the macro. We’re still inside this descending channel that’s been building since late May. SPY tapped into the upper bound around $593 and got cleanly rejected. That zone lines up with a key structure level, and unless we get a surprise macro bid, it’s acting as a ceiling.
If the market keeps digesting soft data and pricing in a mild recession — which I already leaned toward in my recent weekly — we’ve got space to the lower bound of this channel. Call it $570–$572 as the next downside magnet.
Price action is holding up — barely — but if this week doesn’t bring a macro tailwind (jobs data, Fed tone shift), that lower level’s going to look increasingly attractive. No real signs of broad sector rotation out of cyclicals or into defensives yet, but participation is narrowing. That’s a warning sign.
ISM didn’t crater — but it didn’t bounce either. This was the fourth straight month of contraction in new orders, and inventories flipped negative. That’s not what a bottom looks like.
Until we see a shift in forward orders or inventory build-up, the story stays the same: slowdown, not collapse. SPY reflects that — trapped under resistance, trading a range. Reclaim $593 and we talk upside. Fail here, and $570’s right back on the table.
Alchemy Markets is a multi-asset brokerage providing retail traders with the same elite trading conditions, tools, and transparency typically reserved for institutions.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Finance Magnates Summit London returns to Old Billingsgate on 24 November 2026 for its 15th edition. The one-day event brings together brokers, liquidity providers, institutional firms, trading technology vendors, payments businesses and digital asset firms.
iSAM Securities Apex has integrated with Match-Prime, giving brokers access to liquidity across more than 2,000 instruments, with tailored pricing and up to 10 levels of market depth.
propfunding.com's free-entry instant funding changes the order of prop funding. Start trading first. Its free-entry instant funding model offers two qualification attempts without an upfront activation fee.
US stocks closed higher on Wednesday, with the Nasdaq gaining 1%, the S&P 500 rising 0.6%, and the Dow advancing 0.7%, as renewed enthusiasm for AI-related stocks lifted market sentiment.
SpaceX went public in June as a rocket company. On October 20 it reported as something else entirely: an AI infrastructure business, financed by a satellite broadband network, with a launch division attached. Rockets generated 12% of third quarter revenue and lost money. The AI segment generated 52% of revenue and consumed 84% of capital expenditure. Starlink generated 85% of operating profit.
Standard Chartered has signed definitive agreements to acquire 100% of Zodia Custody UK Limited, folding its regulated digital asset custody business into Securities Services. Zodia Solutions will be set up under SC Ventures with bank investors including Northern Trust, NAB Ventures, Emirates NBD and Investcorp.
Bybit Fintech FZE has secured a Virtual Asset Service Provider licence from Dubai’s Virtual Assets Regulatory Authority for Exchange Services, covering spot trading. Bybit’s Peter Loo said the firm hopes to add derivatives, subject to regulatory approvals. Its international Dubai headquarters opened in 2022.
ATFX Connect has released its Q4 2026 Institutional Edge, examining the geopolitical, monetary policy and fiscal pressures shaping global financial markets in the final quarter of the year.
The Nasdaq 100 is trading at 29,382. After reaching a recent high of 29,957, the index reversed sharply and has been recording a series of lower highs and lower lows.
FM Summit London returns to Old Billingsgate on 24 November 2026 for its 15th edition, with a curated one-day format aimed at senior executives. LMAX Group, Plus500, oneZero and MetaQuotes are among confirmed exhibitors, with Business Connect meetings, roundtables and an opening event at The Folly on 23 November.