just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now

The performance of the dollar has seen a modest improvement, while equity markets exhibit a slight softening, influenced by the Federal Reserve's resistance to early easing and renewed attention on US regional banks. In Europe, the prevailing narrative centres around subdued CPI trends and a less assertive stance from the Bank of England, contributing to the overall strength of the dollar across various fronts.
The Federal Reserve's stance against an immediate cut in March has led to a marginal uptick in short-dated US rates, lending support to the dollar. The Fed's message underscores a movement towards a more balanced state between inflation and growth, signalling potential future rate cuts, contingent on additional data to instil confidence in initiating the cycle. Notably, the focus shifts to key dates in February, with annual CPI benchmarks revisions on the 9th and the January CPI release on the 13th capturing the attention of both the Fed and investors.
US regional banks, particularly highlighted by the significant decline in New York Community Bancorp's (NYCB) stock following disappointing quarterly earnings, have emerged as a point of concern. The connection between substantial loan loss provisions and the Commercial Real Estate sector raises questions about the robustness of the US economic narrative. This development coincides with the imminent expiration of the Fed's emergency Bank Term Funding Programme (BTFP) on March 11, prompting investors to scrutinize the situation closely. Optimists anticipate that regulatory bodies, including the FDIC, would not have permitted NYCB to acquire the assets of the failed Signature Bank unless it was financially sound.
However, a noteworthy observation is the 7-basis point widening of the 3-month EUR/USD cross-currency basis swap in response to the NYCB news. This shift, indicative of banks paying premiums for securing dollar funding, traditionally aligns with a strengthening dollar. In the event of a resurgence in the US regional bank crisis, monitoring this basis swap becomes crucial, as the dollar may experience initial strength until the Fed intervenes to stabilize funding conditions.
Looking ahead in the US, the focus turns to initial claims and ISM manufacturing data for the day. While these factors are unlikely to exert significant influence on the market, the Dollar Index (DXY) is anticipated to continue its gradual ascent toward the upper bounds of the 104.5-105 range, with the much stronger US Nonfarm Payrolls (NFP) released on last Friday this is expected to be the primary market driver, for at least the day ahead as it gets factored in.
CEE
The outlook for the Central and Eastern European (CEE) region remains uncertain as the markets prepare to open today, influenced by the volatile reactions witnessed in the global markets last Friday. Notably, the zloty and forint experienced significant rallies over the past two days, reaching levels that may be deemed sufficient for the time being. Concerns arise regarding the potential over strengthening of the Polish zloty (PLN), with indications pointing towards levels around 4.340 EUR/PLN, as highlighted in our previous assessment.
Adding to the dynamics, President Andrzej Duda has signed the new budget but has concurrently referred the proposal to the Constitutional Tribunal. While the immediate economic impact may be limited, this moves signals ongoing political turbulence. Such a development could reignite risk-off sentiment in Poland, contributing to market uncertainties.
Meanwhile, EUR/CZK briefly touched 24.90 following statements from the deputy Czech National Bank governor hinting at a possible 50 basis points rate cut in the upcoming week. Despite the decline in interest rates, the interest rate differential did not undergo significant changes. Consequently, I anticipate a period of stabilization around 24.80 EUR/CZK, with a cautious stance on further upward movement at this juncture. Monitoring the evolving situation will be crucial in navigating the dynamic landscape of the CEE region in the coming sessions.
Insights Inspired by ING: Credit to Their Analysis for Shaping Some Aspects of This Text
This content may have been written by a third party. ACY makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied by any third-party. This content is information only, and does not constitute financial, investment or other advice on which you can rely.
ACY Securities is one of Australia's fastest growing multi-asset online trading providers, offering ultra-low-cost trading, rock-solid execution, technologically superior account management and premium market analysis.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS FeedSign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
US stocks closed higher on Wednesday, with the Nasdaq gaining 1%, the S&P 500 rising 0.6%, and the Dow advancing 0.7%, as renewed enthusiasm for AI-related stocks lifted market sentiment.
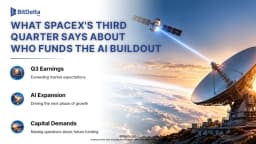
SpaceX went public in June as a rocket company. On October 20 it reported as something else entirely: an AI infrastructure business, financed by a satellite broadband network, with a launch division attached. Rockets generated 12% of third quarter revenue and lost money. The AI segment generated 52% of revenue and consumed 84% of capital expenditure. Starlink generated 85% of operating profit.
Standard Chartered has signed definitive agreements to acquire 100% of Zodia Custody UK Limited, folding its regulated digital asset custody business into Securities Services. Zodia Solutions will be set up under SC Ventures with bank investors including Northern Trust, NAB Ventures, Emirates NBD and Investcorp.
Bybit Fintech FZE has secured a Virtual Asset Service Provider licence from Dubai’s Virtual Assets Regulatory Authority for Exchange Services, covering spot trading. Bybit’s Peter Loo said the firm hopes to add derivatives, subject to regulatory approvals. Its international Dubai headquarters opened in 2022.
ATFX Connect has released its Q4 2026 Institutional Edge, examining the geopolitical, monetary policy and fiscal pressures shaping global financial markets in the final quarter of the year.
The Nasdaq 100 is trading at 29,382. After reaching a recent high of 29,957, the index reversed sharply and has been recording a series of lower highs and lower lows.
FM Summit London returns to Old Billingsgate on 24 November 2026 for its 15th edition, with a curated one-day format aimed at senior executives. LMAX Group, Plus500, oneZero and MetaQuotes are among confirmed exhibitors, with Business Connect meetings, roundtables and an opening event at The Folly on 23 November.
GCEX has launched European-style, fiat-settled options on Bitcoin and Ethereum with monthly expiries for eligible professional and institutional clients. The service runs through the GCEX OTC desk, with pricing from Tier 1 liquidity providers and reporting on XplorPortal. GC Exchange Limited is authorised by the UK FCA
Wall Street closed mostly higher on Tuesday, led by a nearly 1% gain in the Dow. In Asia, South Korea’s Kospi rebounded 2.7% and Japan’s Nikkei gained 0.8%.
Brent crude is trading at $111.70. The latest price action show the recovery continuing toward $111.70, suggesting that demand has returned after the sharp correction.