
Search Companies, News, Members & more
Terms of ServicePrivacy PolicySecurity PolicyLegal InformationCommunity GuidelinesSitemapsCookie Settings
2026 Copyright © Liquidity Finder Ltd. All rights reserved.
Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
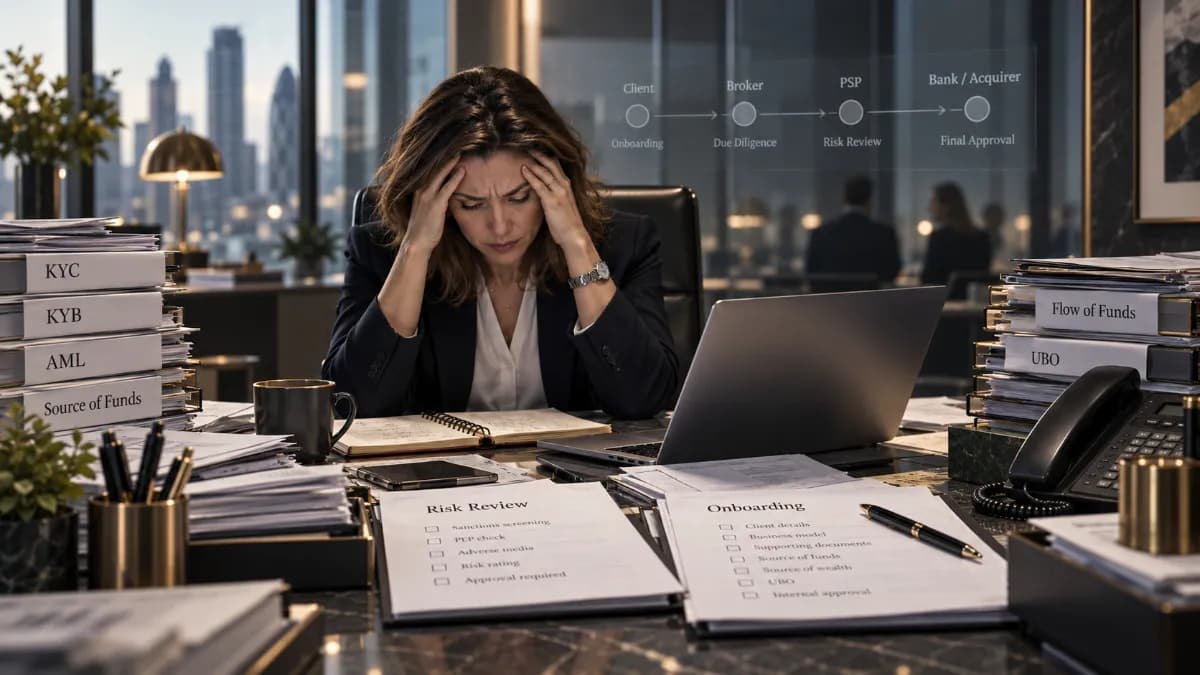
These thoughts have been brewing for a while. I have been asking around about payments for the past few weeks after hearing the same complaint from several firms: onboarding a brokerage with a payment provider has become significantly harder, and the difficulty increases again when crypto is involved.
The obvious question is whether PSPs have simply lost their appetite for CFD brokers.
I don't think they have, but their hands seem to be tied up in red tape and the machine is clogged up..
The problem seems to be that the level of scrutiny has increased dramatically. More documentation is required, more people need to approve it and, crucially, the PSP itself is often not the final decision-maker.
To understand what is happening in practice, I spoke with a Head of Operations at a retail broker who is deeply involved in payment-provider onboarding. Her group holds an ASIC licence as its senior authorisation alongside several other regulated entities. She agreed to speak anonymously and asked that individual providers not be named. (Her comments are in bold throughout.)
It Is Not A Technology Problem
The first point she made is that integration is not the bottleneck.
"From our side, I'd say the biggest payment challenge at the moment is not really integration; it's onboarding, compliance and risk allocation. Once you combine financial services/brokerage with cross-border clients and any crypto exposure, the level of scrutiny increases significantly."
PSP marketing tends to focus on APIs, checkout flows, conversion rates and speed to market.
For brokers, the real question increasingly comes before any of that: will the provider take the business, which entities will it accept, and what documentation will be required to get the transaction approved?
The Compliance Burden Has Grown
The amount of due diligence being requested has expanded, and let’s be honest, no one enjoys this part:
"We're seeing providers ask much more deeply about the exact business model and flow of funds, licences/entities involved, jurisdictions being served, source of funds/wealth, UBO structure, client acquisition channels, transaction history and expected volumes."
None of those requests is unreasonable in isolation, but the problem is the volume of information that now has to be assembled, checked and passed through several layers of approval.
And then even after providing everything, it does not mean the account is approved.
"Even where all of this can be provided, onboarding can still move very slowly because the PSP itself may then need approval from its banking, acquiring or compliance partners."
That is the crucial part that many may miss, and blame the PSP for being slow and disinterested.
The PSP salesperson may want the account. The PSP may even be comfortable with the business. But behind the PSP can sit a safeguarding bank, an acquiring bank, card schemes and specialist compliance or crypto-risk teams.
Each can have its own appetite and the result is then a queue that it seems is just getting longer and longer. This queue turns into frustration, and this frustration gets shared "on the street".
Crypto Adds Another Layer
Crypto makes the risk allocation more complicated again.
Providers broadly divide into:
(1) those that retain custody and perform their own KYT and blockchain monitoring,
and
(2) those that place more of that responsibility with the broker.
-----
(1) Under the first model, the provider controls the transaction-risk decision.
"We've seen situations where even a wallet provided for a refund cannot be used because it has historical exposure to a flagged or high-risk wallet, so the provider will refuse to process the refund to that address."
That creates an immediate operational problem. A broker may need to return a client's funds but find that the destination wallet has been rejected by a screening process the broker neither controls nor can override.
(2) Under the alternative model, more responsibility sits with the brokerage.
"This can give the broker more flexibility, but it also transfers much more of the compliance and AML risk to the merchant."
The broker therefore needs the infrastructure, processes and systems to carry that responsibility itself.
Then There Is The Price Risk
Another issue appears when a provider accepts deposits in volatile cryptocurrencies but does not automatically convert them into a stablecoin at merchant level.
"If, for example, a client deposits BTC or another volatile asset and the brokerage continues holding it in the original currency, the value can move materially before settlement or conversion, meaning the broker can effectively absorb the market risk."
Automatic conversion into USDT or USDC sounds like the obvious solution, but with some providers the conversion is controlled by the PSP and can carry meaningful fees or spreads.
"So the broker is left choosing between carrying crypto price volatility or paying a significant conversion cost."
In other words, payment architecture can inadvertently create a treasury position for the broker.
The Entity Matters More Than The Group
Licensing is another area where brokers can misunderstand how PSPs assess them.
"A number of PSPs have become very restrictive regarding offshore-regulated brokerage entities. For example, we have had providers decline to onboard us specifically because certain clients were being serviced under an SVG entity."
This group has ASIC as its senior licence. It doesn't seem to matter.
The payment provider was assessing the specific entity receiving the client and processing the payment, not the regulatory standing of the group as a whole.
A strong licence elsewhere in the structure does not necessarily compensate for a flow being booked through a jurisdiction that the PSP's bank or acquirer does not want to support.
"A PSP may technically be comfortable with the broker, but not with every entity, jurisdiction or client segment the broker serves. As a result, brokers often need multiple payment providers rather than one universal solution, which then increases operational, treasury and reconciliation complexity."
That is becoming the practical reality for international brokers: there may be no single PSP solution covering every entity, jurisdiction, payment method and client segment.
The PSP Is Only One Layer
So where is all this additional scrutiny coming from? My understanding is that much of it is further upstream. Most brokers do not deal directly with the bank ultimately holding or processing the funds. The chain is closer to:
Client → Broker → PSP → Bank / Acquirer
Everyone in that chain now wants to understand more about the parties sitting below them.
That means going beyond basic ownership and licence documentation.
The increasingly difficult part is documenting the actual flow: where the money comes from, which entity receives it, where the client sits, how the client was acquired, how funds move through the structure and who ultimately carries each element of risk.
The UK's new safeguarding regime is one example of the direction of travel. From 7 May 2026, payment firms became subject to additional safeguarding requirements, including a requirement for safeguarding account arrangements to be formally acknowledged by the bank holding the funds.
This is not just happening in the UK. In Europe, regulators have been concerned enough about banks withdrawing services from payment institutions that EU rules require access bank accounts to be provided on objective, non-discriminatory and proportionate grounds, while the forthcoming PSD3 framework explicitly recognises insufficient documentation, AML concerns and an excessive risk profile as potential reasons for a bank to refuse an account.
Australia is seeing the same pressure. AUSTRAC specifically identifies PSPs, remitters and virtual-asset businesses as sectors affected by debanking, and says banks may need detailed information about their customers, services, jurisdictions and AML controls before deciding whether they fall within the bank's risk appetite.
That inevitably creates more scrutiny further down the chain.
If the bank needs to understand the PSP's underlying exposure, the PSP needs a much more complete file on the broker.
This is why a broker can provide extensive documentation to a PSP and still wait weeks or months for an answer. The provider may be waiting too.
We Have Seen This Pattern Before
There is a useful parallel here with what happened after 2015, although the cause is very different. in 2015, an extreme market event (the Swiss SNB 'Francogedden') caused banks at the top of the FX credit chain to reassess which counterparties they were prepared to support, and to very quickly pull direct lines to this market.
The market responded by creating another layer of intermediation through the growth of prime-of-prime providers (leading to the foundation of LiquidityFinder 🙇). Today, the pressure is coming from financial-crime, compliance and regulatory risk rather than market losses, but the effect further down the chain is similar: more scrutiny, tighter access and more intermediation. A bottleneck.
Payments appears to be experiencing experiencing a tightening which, from what I am hearing, is definitely being felt far and wide now.
The requirements for documentation has become deeper, and thus approval takes longer. More counterparties want visibility into the underlying client base. Providers become more selective about which entities and jurisdictions they will support.
It does not necessarily mean the business is unwanted. It means the cost in terms of the time taken to approve it has increased.
So, Do PSPs Still Want The Business?
The Head of Operations I spoke to summed it up:
"So my general impression is that the issue is less that payment providers do not want brokerage business, and more that compliance teams, banks, acquirers and crypto-risk teams have become much more selective about exactly which part of that business they are prepared to take. In many cases, the key questions now are who carries the custody and AML/KYT risk, who carries the crypto price risk, and how much control the merchant actually has over conversion, settlement and transaction monitoring."
This is the key point. The commercial appetite for brokerage business remains very visible. Anyone attending an industry conference knows how many payment firms are actively selling to brokers, or chasing you on LinkedIn (I know, I get them too!).
But commercial appetite and compliance appetite are not the same thing.
A PSP salesperson can genuinely want your business while having very little influence over whether the final approval arrives.
Risk appetite also changes. One major PSP told me recently that it formally reviews its appetite every three months.
For a broker, the useful question when onboarding stalls is therefore not:
Does this PSP actually want our business?
It is:
Which approval are we waiting for, what documentation is missing, and who ultimately has to sign it off?
The Real Bottleneck Is Processing The Evidence
That brings me to what I think is the core issue.
The problem increasingly isn't a lack of PSPs willing to talk to brokers. It is the size and complexity of the documentation required to get through the chain.
Everyone - broker, PSP, bank and acquirer - is being asked to understand activity further down the line than they historically did.
Basic corporate and UBO documentation is usually manageable, but Flow-of-funds evidence is harder.
Source-of-wealth evidence can arrive as numerous documents containing huge amounts of unstructured information. Someone then has to read it, understand it, cross-reference it and produce something the next risk team can rely upon.
Multiply that across hundreds of onboarding cases and the bottleneck that the industry seems to be in right now is the result. The standards keep rising faster than the industry's ability to process the paperwork.
There May Be Some Light At The End Of The Tunnel - The 'Speedy Boarding' Pass
Interestingly, technology may now be available to start addressing this part of the problem.
I sent an advance copy of this newsletter to a contact in the payments market for comment. They were keen to explain to me a solution they have developed to solve the problem of unblocking their own queue. Their system processes large volumes of unstructured documentation and database records into a structured file that can be reviewed by a financial institution to decrease document processing times down to minutes/hours rather than days/week/months.The documentation queue itself is the problem it is trying to solve: not another payment rail or API, but something to unblock the whole industry.
The firm has not yet announced the product publicly, so I cannot name it.
This is not an entirely new category. Technology already exists to automate significant parts of financial-services onboarding with KYC and KYB, screening, regulatory classification, risk assessment, document collection and ongoing monitoring.
What’s interesting here is the next part of the process.
Rather than simply collecting documents and completing individual checks, this system reads across the whole case: documents, interviews, screening data, wallet intelligence and case notes and then connects the evidence to what has been asserted, identifies contradictions and missing information, and prepares a decision-ready case for the compliance officer or MLRO.
The humans still make the decision. The technology removes the enormous amount of manual work required to get the case into a state where that decision can be made.
If technology can turn weeks of assembling, reading and cross-referencing compliance material into a process measured in hours, that could remove one of the biggest practical bottlenecks currently affecting broker onboarding.
And there is another potentially important element. Once a business has been through the process, its verified information can be packaged in a way that can be shared with another institution. That does not mean one firm's approval automatically becomes another firm's approval (every PSP or bank still has its own risk appetite and responsibilities) but it could mean that the same evidence does not have to be assembled and checked from scratch every time. The client then gets the coveted 'speedy boarding' pass that you might get on EasyJet and smugly get on and off the plane ahead of everyone else in the cheap seats.
If technology can turn weeks of assembling, reading and cross-referencing compliance material into a process measured in hours, that could remove one of the biggest practical bottlenecks currently affecting broker onboarding.
I will write more about the system when I am allowed to. (If you would like an introduction before it’s formally announced, send me a message and I can point you in the right direction.)
My thanks to the Head of Operations at the unnamed broker who spent time on giving me very candid and detailed answers, and for this new service provider who is stepping in to save us all!
And if you are on the provider side and think this characterises the market unfairly, I would genuinely like to hear from you.
If you would like to review suitable payment partners for your business, you can check them out on LiquidityFinder here.
DO feel very welcome to leave your comments below 👇.
Thanks, Sam
Share this article
Comments
Most Recent
Find The Right Partners for
Your Trading Business
Sign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
Not every neobank is actually a bank. Olaf Ransome of 3C Advisory sets out the three models operating under the label, compares UK challenger scale against the incumbents, and asks why legacy institutions have almost universally failed to compete.
Independent review of the Equals BaaS solution: multi-currency accounts, payments and cards for FX brokers and digital asset firms facing debanking risk.
The Lowdown - newsletter. Something significant is happening in financial markets right now. Prediction markets are the new shiny object, and they are definitely now an institutional asset class. In the same way that brokers scrambled to add crypto to their offering a few years ago, the smartest operators in our space are already asking how they access prediction markets.
As tokenisation and digital assets move from niche curiosity to mainstream expectation, banks and financial institutions face an uncomfortable truth: their legacy core banking systems were never built for this. From order execution and pre-funding to custody, portfolio management and gas fees, Olaf Ransome explores the key infrastructure challenges FIs must navigate and asks whether to re-use, buy or build their way to a solution that actually scales.
Create Your FREE Account
Get access to latest news, updates, real-time data, brokerage and trading firm insights and customized information feeds.


Bybit has launched Perp Options, described as the first options contracts built on TradFi perpetuals, giving traders round-the-clock access to US equity options. SpaceX and Nvidia are the first underlying assets, with USDT settlement and integration into Bybit's Unified Trading Account.


Use this trading preparation checklist to plan your session, define entry rules, manage risk, and build a disciplined trading routine in seven steps.


Your Bourse expands its crypto liquidity ecosystem with Caladan, giving brokers access to broader market coverage, institutional execution capacity and streamlined settlement.

Scope Markets, the retail brokerage part of Rostro Group, has appointed Ibrahim Hossny as Head of Research and Marketing for the Middle East and North Africa.

Hantec Prime, the institutional division of Hantec Markets, has reported trading volume up more than 300% year-to-date, alongside the addition of 42 new institutional clients since December, capping one of its strongest years of growth to date.

Learn how to refine XAUUSD support and resistance on the daily chart using candle bodies, market structure and weekly gold levels for swing trading. A slug alone cannot guarantee a top Google ranking. Keep it focused rather than adding every supporting keyword.


The week in Dubai will be focused on connecting directly with the industry and discussing how technology can help modern brokerages simplify operations, automate workflows, strengthen operational control, and scale efficiently.

Devexperts has launched a turnkey solution giving brokers in South Korea access to US equity markets, combining its DXtrade trading platform, dxFeed market data, and execution services. The offering targets South Korea's growing retail demand for US stocks, worth several billion USD monthly.

Assess why WTI crude oil surged past $105 per barrel amid Saudi pipeline disruptions, record tanker charter rates, and escalating geopolitical tensions.

Bitcoin price forecast: BTC/USD retests $78,460–$80,215 resistance. Watch bearish confirmation toward $72,480 or a bullish breakout toward $86,150.
Feed