just now

Liquidity Finder Ltd is incorporated in England and Wales, company number 10610740, registered address 167-169 Great Portland Street, Fifth Floor, London W1W 5PF, United Kingdom.
Published: just now
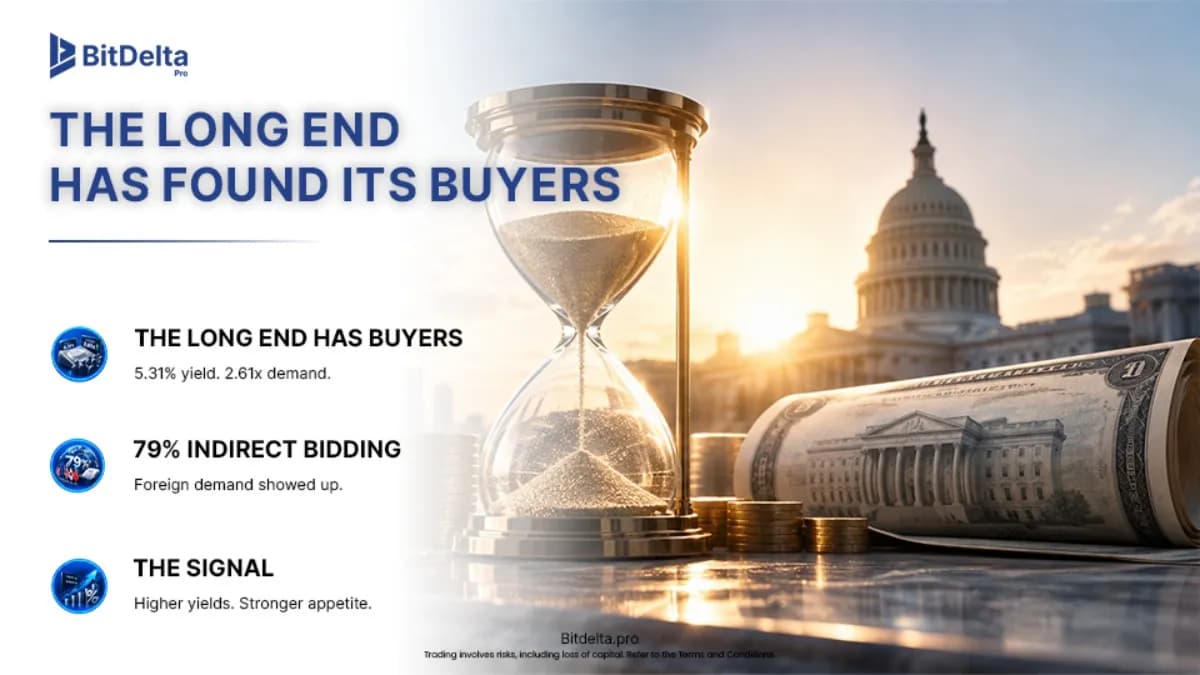
The 30-year auction cleared yesterday with results that confirm what the 10-year auction established on Tuesday: the market is willing to absorb long-dated US government debt at the highest yields in a generation, and it is showing up with genuine demand to do so.
The Results
| Metric | 30-Year (Sep 10) | 10-Year (Sep 9) |
| High yield | 5.31% | 4.834% |
| Median yield | 5.25% | 4.790% |
| Bid-to-cover ratio | 2.61x | 2.71x |
| Indirect bidders | 79% | N/A |
| Amount raised | $22 billion | $39 billion |
Combined, the Treasury raised $61 billion in long-dated debt across two days at the highest yields since 2007, with bid-to-cover ratios that rank among the strongest of the year.
What the 79% Indirect Bidding Tells You
Indirect bidders are primarily foreign central banks and international institutional investors. At 79% of total demand, foreign participants were the dominant buyers of 30-year US duration at a 5.31% yield.
The narrative that foreign holders are dumping Treasuries and fleeing US debt does not survive contact with this data point. The same institutions that the doom crowd claims are selling are, in fact, the first in line when yields reach attractive levels. The question was never about creditworthiness. It was about price. At 3.5%, foreign demand was tepid. At 5.3%, it is overwhelming. This is not a crisis. It is a market functioning exactly as markets should: higher prices (yields) attract more buyers.
The Auction Did Not "Fail"
A persistent misunderstanding circulating after both auctions is that they were unsuccessful because yields did not immediately decline following the results. This reflects a fundamental confusion about what an auction is.
A Treasury auction is a primary market mechanism where the clearing price is established through competitive bidding. The auction's success is measured by the bid-to-cover ratio (demand relative to supply), the tail (difference between the high yield and the when-issued yield), and the composition of buyers (direct, indirect, primary dealers). By every one of these metrics, both auctions this week were strong.
The expectation that yields should drop the moment an auction clears conflates the primary market with the secondary market. The auction sets the price at which new debt is issued. Secondary market trading after the auction reflects every other variable affecting bond prices: inflation expectations, geopolitical risk, Fed policy outlook, and supply-demand dynamics across the entire curve. A strong auction into a market with persistent inflation concerns and an active military conflict in the Strait of Hormuz is not going to produce an immediate yield decline. That is not failure. That is a market correctly pricing multiple simultaneous inputs.
The Bessent buyback operations are a separate mechanism operating on a different timeline. The buybacks target older, less liquid long-dated securities in the secondary market. Their purpose is to improve liquidity and compress the premium on off-the-run bonds, not to reduce the overall yield level. Evaluating buyback success by whether the 10-year yield dropped the next day misunderstands the objective entirely.
The Gold Argument Does Not Apply to Institutions with Liabilities
The gold market's response to rising yields has prompted a familiar chorus: gold is the safest asset, yields are unsustainable, the US is drowning in interest costs, and institutions should be allocating to gold instead of bonds.
This argument fails at the most basic level of institutional portfolio management. Pension funds, insurance companies, sovereign wealth funds, and endowments have liabilities. They owe money to people at specific times in the future. A pension fund that must pay a retired teacher $4,000 per month in 2036 needs an asset that generates predictable cash flows matching that obligation. A 30-year Treasury at 5.31% does exactly this. It pays a fixed coupon every six months for three decades. The cash flows are contractually guaranteed by the US government.
Gold does not do this. Gold pays no coupon. Gold generates no cash flow. Gold cannot be duration-matched to a liability schedule. Gold's return is entirely dependent on price appreciation, which is uncertain and volatile. For an institution running asset-liability management, gold is not a substitute for bonds at any yield level. It serves a different function (reserve diversification, inflation hedge) for a different type of holder (central banks, family offices, retail investors). Conflating the two reflects a misunderstanding of why institutions buy bonds in the first place.
Central bank gold buying (1,000 tonnes per year, driven by sanctions risk and reserve diversification) operates on an entirely separate logic from institutional bond demand. Both can coexist. A pension fund buying 30-year Treasuries at 5.31% and the People's Bank of China buying physical gold are not making contradictory decisions. They are solving different problems with different instruments.
The Macro Picture: Expansion with a Higher Cost of Capital
The anxiety about rising yields treats higher rates as inherently destructive. This framing ignores basic macroeconomics.
Economies can expand without excess liquidity. They have done so for most of economic history. The ZIRP era of 2009-2021 was the anomaly, not the norm. The current expansion is driven by supply-side improvements (AI productivity, reshoring, manufacturing capacity expansion) and investment-driven demand (hyperscaler capex, defence procurement, infrastructure spending). Equipment investment grew 17.2% in Q1 2026. Manufacturing PMI has been expansionary for nine consecutive quarters. These are not the characteristics of an economy that requires 0% rates to function.
Higher yields reflect three forces operating simultaneously, and distinguishing between them is essential.
Economic strength. A growing economy generates more demand for capital. More demand for capital raises the price of capital. This is healthy and self-correcting: the same growth that raises yields also generates the earnings and cash flows that service the higher cost. This component of the yield move is bullish for equities.
Inflation expectations. Oil above $90, services inflation sticky above 3%, and a tightening labour market all contribute to higher nominal yields through the inflation premium. CPI later today will provide the latest data point. This component is a headwind for equities because it raises input costs and reduces real returns.
Crowding out. The government is borrowing $61 billion in long-dated debt in a single week while running annual deficits near $2 trillion. This competes with private sector borrowing for the same pool of savings. The higher yields partly reflect this supply pressure. This component is a structural feature of the fiscal expansion, not a crisis. It is the cost of the reshoring, defence, and infrastructure investment that the administration is pursuing.
The alarmism treats all three components as the same problem. They are not. Economic strength is a tailwind. Inflation expectations are manageable if core continues to converge toward target (2.4% in the latest reading). Crowding out is the price of the policy choice, and today's auction results demonstrate that the market is willing to pay that price at current yields.
CPI Later Today
July CPI is expected this afternoon. Headline is likely to come in hot given oil above $90 during the collection period. Core CPI at 2.4% is the number that matters. If core holds steady while headline rises on energy, it confirms that the underlying inflation trend is converging toward target and that the headline noise is geopolitical, not structural.
A hot headline will likely push hike probabilities higher and add to yield pressure in the short term. But CPI is by definition a noisy, backward-looking indicator. The deflationary forces in the pipeline (AI productivity gains, supply chain normalisation, increased manufacturing capacity) have not yet fully manifested in the price data. They will, over time. The current inflationary pressures from oil and wages are real but coexist with structural forces pushing in the opposite direction. The net effect will become clearer over the next two to three quarters as the supply-side improvements translate into lower unit costs.
The Bottom Line
Two auctions. $61 billion raised. Bid-to-cover ratios of 2.71x and 2.61x. Indirect bidding at 79% on the 30-year. The highest yields since 2007.
The market is demanding a premium for holding long-dated US debt. It is also showing up in force to buy it. These two facts are not contradictory. They are the definition of a functioning market: higher prices attract more buyers.
The US economy is expanding. Corporate earnings are growing at the fastest pace this century. The AI infrastructure buildout is generating measurable revenue across the supply chain. Manufacturing is in its longest expansion in years. The cost of capital is higher. The companies and institutions that can deliver returns above that cost will thrive. The ones that cannot will be repriced.
That is how markets work. It is not a crisis. It is a market.
BitDelta Securities Financial Services LLC, regulated by the Capital Market Authority under Category 5 (Introduction Only), acts solely as an introducer and does not provide trading, execution, dealing, advisory, portfolio management, or custody services. All trading, execution, and investment-related services are provided by BitDelta Limited, Mauritius, a licensed Investment Dealer excluding underwriting. All trading and investments involve risk. The value of investments may fluctuate, and you may receive less than your initial investment.
The information contained in this article is provided for general informational purposes only and does not constitute financial, investment, legal, or professional advice, or a recommendation to buy, sell, or hold any financial product. Readers should seek independent professional advice and conduct their own due diligence before making any decisions. Neither the publisher nor the contributors accept liability for any loss arising from reliance on this content.
Institutional multi-asset market access across MT5 Ultency, CQG, Iress Pro and BitDelta Terminal, with transparent execution standards and global market coverage.
Select the categories and companies you wish to follow directly to your person rss feed.
Create Custom RSS Feedjust now
just now
just now
Sign up and join over 5,000 professional members who receive personalized news alerts, curated professional connections, and more for free!
CMC Markets has retired the CMC Connect name and will now present its institutional business as CMC Markets Institutional.
The SEC has approved Cboe's binary options tied to key performance indicators reported by 23 companies, covering more than 100 metrics such as iPhone revenue. The cash-settled contracts pay a fixed $1, Robinhood plans to be the first retail broker to offer them, and trading awaits clearing registration.
Gold is trading around $4,150, recovering sharply after falling to a recent low of $4,073.
Global semiconductor and technology stocks sold off sharply on Thursday, with South Korea’s SK Hynix plunging over 10% and Samsung Electronics falling more than 8%.
Learn gold market structure to identify bullish, bearish and ranging XAUUSD trends using higher highs, higher lows, lower highs and lower lows, support and resistance.
Axi has launched an MCP integration connecting eligible MT5 accounts to Claude, allowing clients to access live market data, track positions, execute trades and update risk parameters through the AI assistant developed by Anthropic. Available to eligible Axi clients with an active MT5 account. Setup runs via Claude.ai.
Movantis has selected Integral to extend its FX liquidity offering for institutional clients including banks, payment networks and digital asset operators, adding an institutional trading platform, direct-to-client API trading and API connectivity into a third-party multi-dealer venue, supporting regional expansion.
Running a venue around the clock is the easy part. Pricing risk when the market underneath it is shut is not. Lars Holst, CEO of GCEX explains how to manage risk in 24/7 markets.
ATFX has released its Q4 2026 Trader Magazine, offering a closer look at the macroeconomic and market forces that could shape trading conditions in the final quarter of the year.
LSEG has announced a collaboration with NVIDIA that lets financial institutions analyse years of LSEG Tick History data in seconds using NVIDIA cuDF on GPUs, without creating another full copy of the dataset. Tick History holds 110 trillion rows across 100 million instruments and more than 580 venues and contributors.